
Teledyne Technologies (TDY) Launches New Defense Tools, Is A 19% Discount Still There?
Teledyne Technologies (TDY) is back in focus after its FLIR unit rolled out Prism A-ISR software for airborne intelligence systems and introduced the Ranger R10-3DX counter-drone radar for military and security users.
The Prism A-ISR and Ranger R10-3DX launches arrive after a steady run, with Teledyne Technologies posting a 17.82% year to date share price return and a 49.06% three year total shareholder return. However, the 7 day share price return has slipped 1.77%, suggesting some short term enthusiasm has cooled while the longer record still points to investors having been rewarded for staying in the story.
Scan 92 AI infrastructure stocks to find other defense and sensor stocks using AI and advanced hardware in ways that echo Teledyne Technologies' latest airborne and counter-drone launches.
After a long stretch of gains, a softer recent patch leaves Teledyne Technologies looking finely balanced between further upside and a lot of good news already reflected. Is the current valuation still giving you enough runway?
Most Popular Narrative: 19% Undervalued
Teledyne Technologies last closed at $611.21 while the most followed narrative pegs fair value at about $758. This suggests investors are weighing a long pipeline of defense, space, and imaging contracts against what is already priced in.
Expanding defense programs in unmanned systems, missiles and munitions, and space sensing are adding multi year revenue visibility, with expected 2026 defense revenue of about US$2.15b, unmanned systems of about US$575 million, missiles and munitions components rising toward about US$240 million, and space related revenue of about US$450 million. Together, these factors support sustained growth in sales and earnings.
See why 13 investors see Teledyne Technologies as 19% undervalued.
Result: Fair Value of $758.08 (UNDERVALUED)
Still, supply chain strains or weaker margin execution around defense programs and the Varex Imaging deal could quickly challenge the upbeat narrative surrounding Teledyne Technologies.
Find out about the key risks to this Teledyne Technologies narrative.
Another View on Teledyne Technologies' Valuation
Analysts see Teledyne Technologies as about 19% undervalued using earnings forecasts and a future P/E of 35.7x. Our DCF model paints a cooler picture. On that basis, TDY at $611.21 sits above an estimated $590.49 future cash flow value, which points to a premium rather than a discount. Which lens feels more convincing to you?
Look into how the SWS DCF model arrives at its fair value.
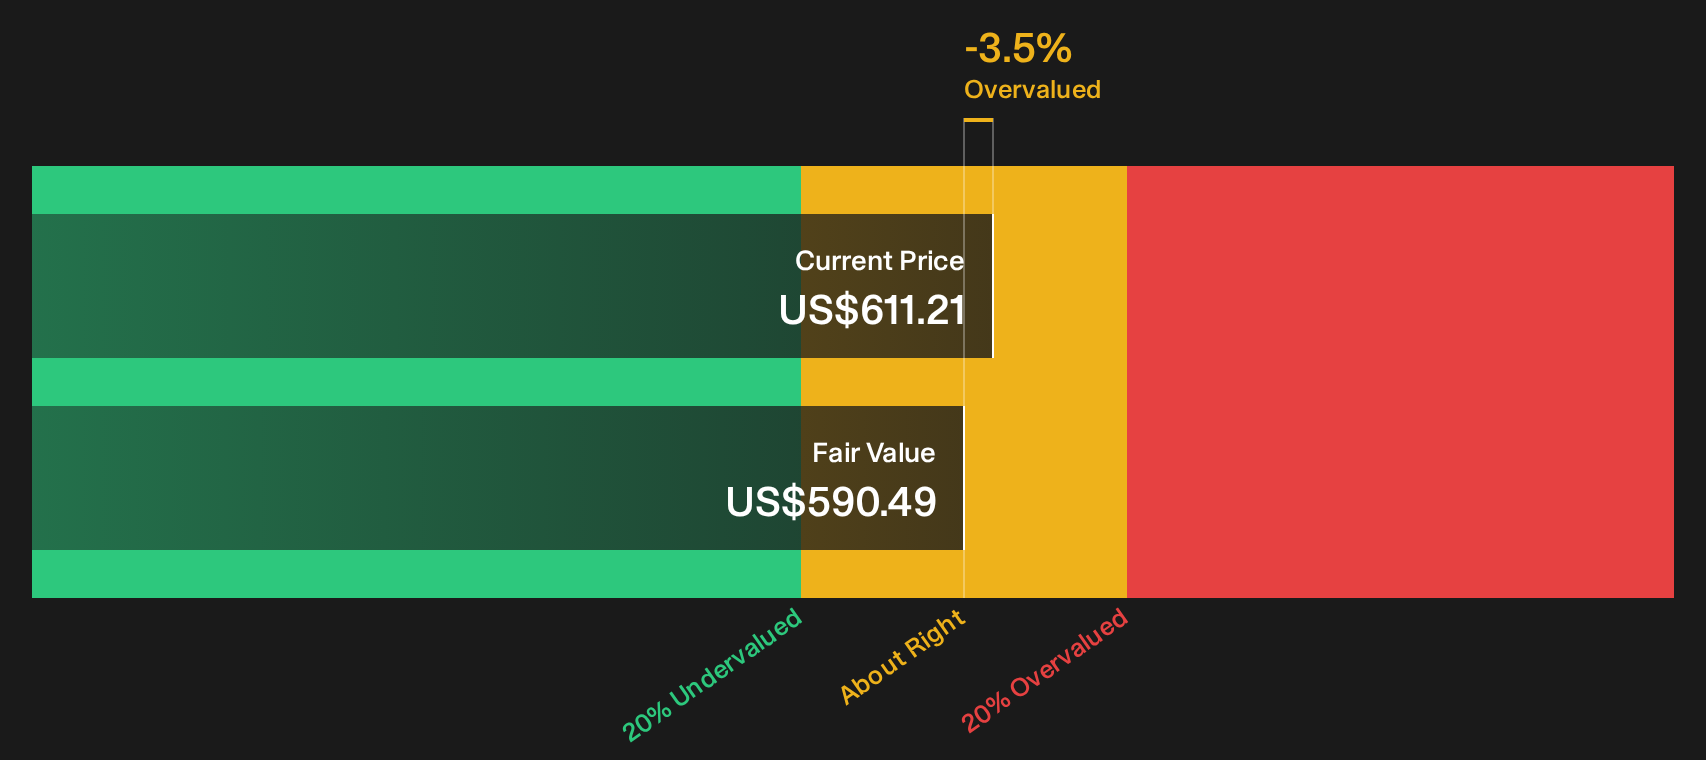
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Teledyne Technologies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals in the Teledyne Technologies story so far. Act while the data is fresh and weigh both sides by checking the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Teledyne Technologies?
If Teledyne Technologies has sharpened your thinking, do not stop here. Put that momentum to work by stress testing fresh ideas against clear, data driven filters.
- Hunt for potential bargains that combine quality with a modest price tag by scanning the 32 high quality undervalued stocks.
- Build a sturdier core for your portfolio by focusing on companies with strong finances using the list of solid balance sheet and fundamentals (25 results).
- Target cash returns while you wait for capital gains by reviewing the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com