
3 U.S. Life Insurance Stocks To Watch If Higher Rates Hold
Fed officials are hinting at a possible October rate hike, bond markets are swinging, and cash is piling up in money market funds instead of equities. When policy credibility and long term yields sit in flux, investor nerves can quickly turn into opportunity or regret. This article walks through three U.S. life insurance and annuity stocks exposed to these cross currents and helps you decide which stories to watch most closely.
The three insurers covered below are just a sample set, and the wider screen surfaced 16 more U.S. life insurance and annuity providers with equally compelling stories that are not discussed in this article.
If you want to identify and analyze which of these retirement and guaranteed income players best fits your thesis right now, head straight to the U.S. Life Insurers and Annuity Providers screener.
Samsung Life Insurance (KOSE:A032830)
Overview: Samsung Life Insurance is a major Korean insurer providing life and health cover, retirement pensions, and related financial services to households and corporates.
Operations: Samsung Life Insurance generates about ₩47.2 trillion from domestic insurance, ₩4.5 trillion from domestic card and leasing, and ₩0.2 trillion from overseas operations, almost entirely in South Korea.
Market Cap: ₩45.97 trillion
Samsung Life Insurance sits squarely in the retirement and guaranteed income theme. In a world of shifting rate expectations, its long-duration policies make interest rate swings matter far more to your outcome than for most financial stocks.
"Rising medical service usage is already widening negative operating variance in claims. If healthcare utilisation continues to trend higher, Samsung Life Insurance may struggle to contain the loss ratio despite stricter underwriting, which could pressure insurance service results and net margins."
What happens to those margins and future dividends depends heavily on how one unseen pressure within its core protection portfolio ultimately plays out.
That pressure point is exactly what the full narrative for Samsung Life Insurance unpacks in detail, including how rising healthcare usage could be masking quieter strengths in Samsung Life Insurance.
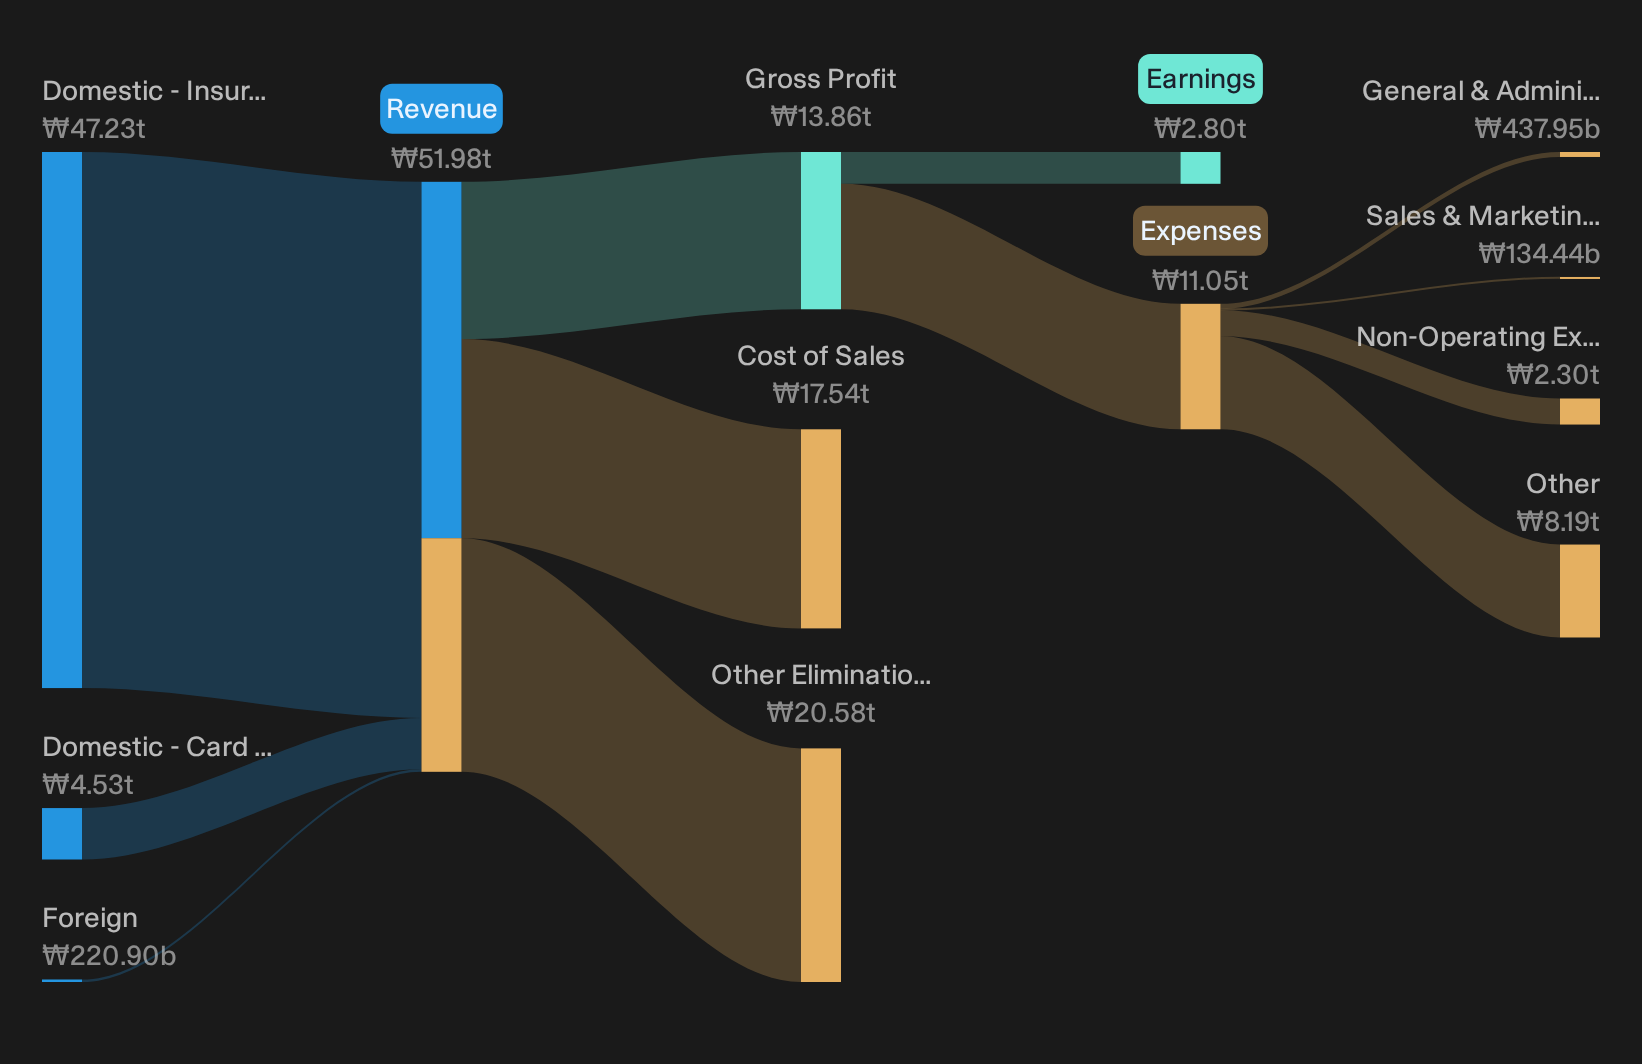
Unum Group (UNM)
Overview: Unum Group sells employee benefits such as life insurance, disability cover and related protection products tied to long term obligations.
Operations: Unum Group generates about US$8.1b from Unum US, US$2.1b from Colonial Life, US$1.7b from Closed Block and US$1.3b from Unum International, with smaller corporate items.
Market Cap: US$14.6b
For investors focused on retirement security and guaranteed income, Unum Group is a textbook interest rate sensitive insurer in which long dated promises are matched with long dated bonds. The central story is how the company is trying to make its balance sheet lighter and more focused.
"Unum Group’s ongoing work to shrink and reinsure its long term care block, including the additional US$3.8b of statutory reserves ceded and the reaffirmation that the remaining block is self supporting, keeps more capital and management focus available for employee benefits, which can support earnings stability and reduce pressure on net margins."
The way Unum Group allocates that freed up capital, together with any change in the long end of the yield curve, will influence how durable its future margins and dividend capacity may be.
That capital question is exactly what the full narrative for Unum Group unpacks, showing how Unum Group’s reshaped book could turn balance sheet repair into accelerating earnings power.

Genworth Financial (GNW)
Overview: Genworth Financial provides U.S. mortgage insurance, long term care cover, and retirement oriented life and annuity products tied to long duration obligations.
Operations: Genworth Financial generates about US$6.1b from Closed Block, US$1.3b from Enact, and US$35 million from Corporate and Other activities.
Market Cap: US$3.4b
Genworth Financial fits this screener because its long term care, life and annuity promises are backed by a large bond portfolio that can benefit when long term rates settle at higher, stable levels. Higher new money yields, recent AM Best outlook stabilization, and ongoing capital returns keep the focus on what happens if a single key assumption breaks.
If that assumption cracks, the 1 key reward and 2 important warning signs (1 is major!) explains how Genworth Financial’s potential upside could quickly separate from the main macroeconomic narratives.

Seeking Alternatives Before Momentum Flies
Fresh ideas can move from quiet to breakout while most investors are still catching up. Use that window while it matters and before momentum gets away. Act now.
- Chase early momentum in high quality companies before they are widely talked about by tracking a curated 184 high quality undervalued stocks that screens for both resilience and pricing gaps.
- Position ahead of the next wave in electricity demand by reviewing a focused 43 power grid technology and infrastructure stocks aimed at businesses tied to critical grid and transmission upgrades.
- Target durable cash generators while yields remain in flux by scanning a curated 218 dividend fortresses built around companies aiming to maintain sizeable distributions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com