
Vulcan Materials’ Q3 2026 Earnings: What to Expect
Headquartered in Birmingham, Alabama, Vulcan Materials Company (VMC) is the largest supplier of construction aggregates in the United States, providing essential materials such as crushed stone, sand, and gravel. The company also produces aggregate-based construction materials, including asphalt and ready-mixed concrete, making it a key player in the nation’s construction and infrastructure industries.
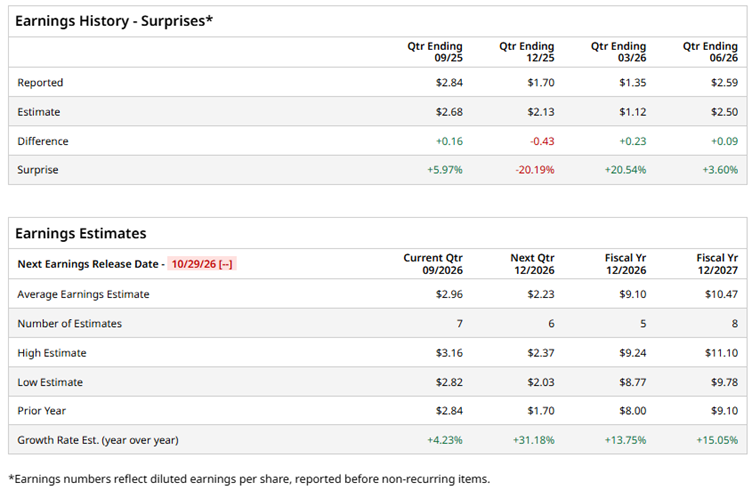
Valued at a market capitalization of $31.56 billion, Vulcan is scheduled to report its fiscal 2026 third-quarter results before the market opens on Thursday, Oct. 29. Heading into the earnings announcement, Wall Street expects Vulcan to deliver earnings of $2.96 per share, representing a 4.2% increase from the year-ago quarter. Its recent earnings track record has been mixed, with the company beating bottom-line estimates in three of the past four quarters while falling short once.
Looking further ahead, analysts expect earnings per share to reach $9.10 in fiscal 2026, up 13.8% year over year, before climbing another 15.1% to $10.47 in fiscal 2027, pointing to expectations of continued earnings growth.
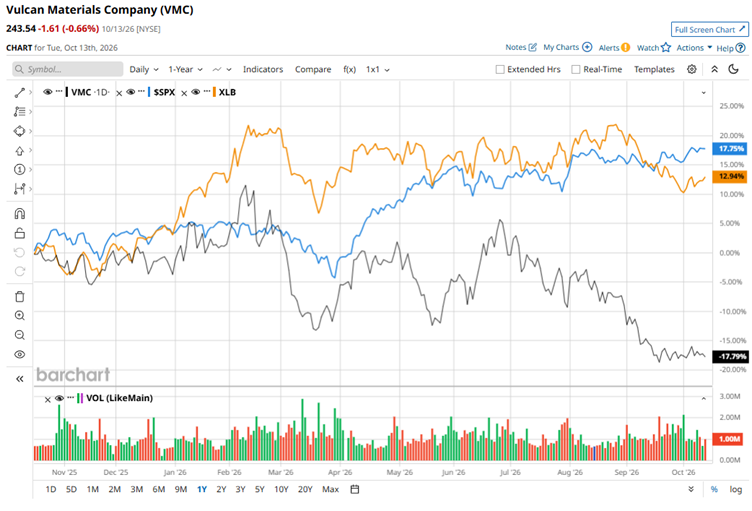
Vulcan Materials has struggled to gain traction over the past year, with its shares tumbling 19.6% and lagging well behind the broader market. In contrast, the S&P 500 Index ($SPX) has climbed 17.3% over the same period, while the State Street Materials Select Sector SPDR ETF (XLB) has advanced 12.7%, underscoring Vulcan’s underperformance against both the broader market and its materials-sector peers.
Vulcan Materials’ underperformance over the past year reflects a combination of uneven quarterly results and broader macroeconomic headwinds weighing on the construction and materials sector. Still, the company delivered a resilient fiscal 2026 second-quarter performance on Jul.29, supported by disciplined commercial execution and steady pricing gains across its core construction aggregates business.
Revenue rose 2.6% year over year to $2.16 billion, edging past Wall Street’s estimate of $2.14 billion. Net earnings attributable to Vulcan reached $323.4 million, while adjusted diluted earnings per share came in at $2.59, slightly ahead of analysts’ expectations of $2.50.
Despite Vulcan Materials’ disappointing share-price performance over the past year, Wall Street remains cautiously optimistic about a potential rebound. Of the 24 analysts covering VMC, 14 recommend a “Strong Buy,” one assigns a “Moderate Buy,” eight maintain a “Hold,” and one issues a “Strong Sell,” translating into an overall “Moderate Buy” consensus rating. The Street also sees considerable room for recovery, with an average price target of $309.39 implying roughly 27% upside from current levels.
On the date of publication, Anushka Mukherji did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.