
Princes Group (LSE:PRN) Stock Still Looks Expensive Following Its 24% Slump
Princes Group has seen its share price move around this year, and that swing puts a spotlight on a simple question for you as an investor. Are you paying a sensible price for the earnings this business is currently producing?
- The stock is down 24.4% year to date, which puts earnings under the microscope because a weaker share price does not automatically mean the underlying profit story has changed in the same way.
- The group’s ability to convert its operations into consistent earnings, through its pricing power, cost control and product mix, may support or constrain what investors are willing to pay for each pound of profit.
- There is a second opinion on Princes Group worth weighing. See what analysts think Princes Group's shares could be worth.
For investors, the debate is whether Princes Group’s current share price fairly reflects what its earnings justify today.
If you want to sanity check Princes Group’s earnings valuation against a wider field, line it up alongside companies in the 8 high quality undervalued stocks
Has Princes Group Run Too Far on Earnings?
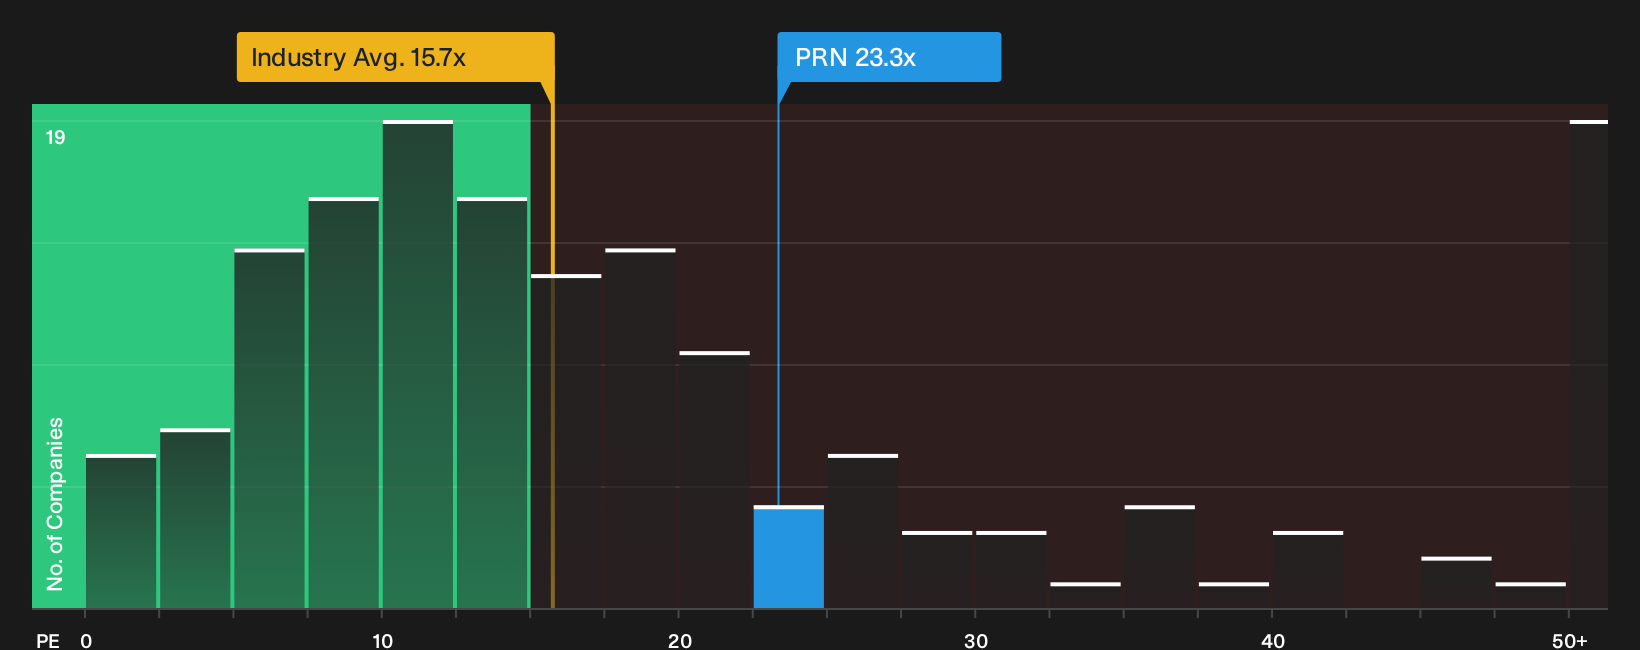
The P/E ratio fits Princes Group because the story here is very much about what investors are paying for each pound of profit today. The stock trades on a P/E of 23.3x, which is meaningfully higher than the wider Food industry average of 14.9x and also above the peer group on 18.4x. That gap indicates that buyers are already accepting a richer ticket price for the earnings on offer.
A tailored fair-value multiple that blends growth expectations, profitability, sector backdrop and size points to a lower P/E than where Princes Group is currently priced. As a result, the shares screen as overvalued on this yardstick. For anyone weighing an entry or adding to an existing position, the key question is whether the quality and resilience of those earnings really merit paying more than both the industry and that modelled fair range is suggesting. Explore the numbers behind Princes Group's P/E valuation.
The Princes Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take that P/E puzzle for Princes Group and spell out what would need to happen to growth, margins and earnings for the shares to look meaningfully higher or lower than today’s price. Each scenario links a fair value to a specific storyline about Princes Group's possible catalysts and pressure points, so you can watch over time which version of events appears to be taking shape on the Community page.
A clear, number-driven narrative on Princes Group gives you a single place where your assumptions on growth, margins and execution are written down and easy to test against what the company actually delivers over time. As new results arrive, that framework lets you compare the original story with how Princes Group’s earnings profile and valuation really evolve in practice.
Share your own Narrative for Princes Group and set out the assumptions behind your valuation.
Princes Group: why the next few years on paper could change how you see today's price
Share prices move in real time, but analyst models try to sketch where a business might be a few years from now. This gives you a different lens to compare with the current valuation. Explore where analysts expect Princes Group to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com