
Is Azenta (AZTA) Fully Valued As Its Recovery Narrative Lifts Shares?
Azenta (AZTA) has drawn attention after a recent move in its share price, with the stock closing at $37.87 on 14 October 2026. That shift now sits against mixed short and longer term returns.
Recent trading tells a mixed story for Azenta. The 30 day share price return of 22.76% and 90 day gain of 41.78% point to building momentum, even though the 3 year total shareholder return declined 27.30% and the 5 year figure fell 63.96%.
Scan beyond Azenta and spot other life sciences and healthcare stocks showing strong recent moves with our hand picked 32 high quality undervalued stocks.
Bulls see Azenta as a recovery play after sharp recent gains, while bears point to the long term share price damage and current losses. Which case does the valuation math lean toward next?
Most Popular Narrative: 7% Overvalued
Azenta's most followed valuation storyline pegs fair value at $35.25, which sits below the recent $37.87 close and frames the latest rally as richer than that model implies.
The company's streamlined cost structure, as a result of structural realignment and deployment of the Azenta Business System (ABS), has already yielded substantial G&A reductions and improved working capital. Together, these enable sustainable free cash flow generation and margin stability even amid near-term macro headwinds. Significant ongoing investments in R&D, sales, and infrastructure are required to drive innovation and growth. If improvements in top-line growth do not materialize, these elevated expenses risk compressing net margins and free cash flow over the long term.
See why 3 investors see Azenta as 7% overvalued.
Result: Fair Value of $35.25 (OVERVALUED)
Still, Azenta faces real pressure if delayed orders in higher margin equipment deepen or if sustained weakness in Gene Synthesis and Sanger Sequencing reduces profitability.
Find out about the key risks to this Azenta narrative.
Another View: What Azenta's Sales Multiple Signals
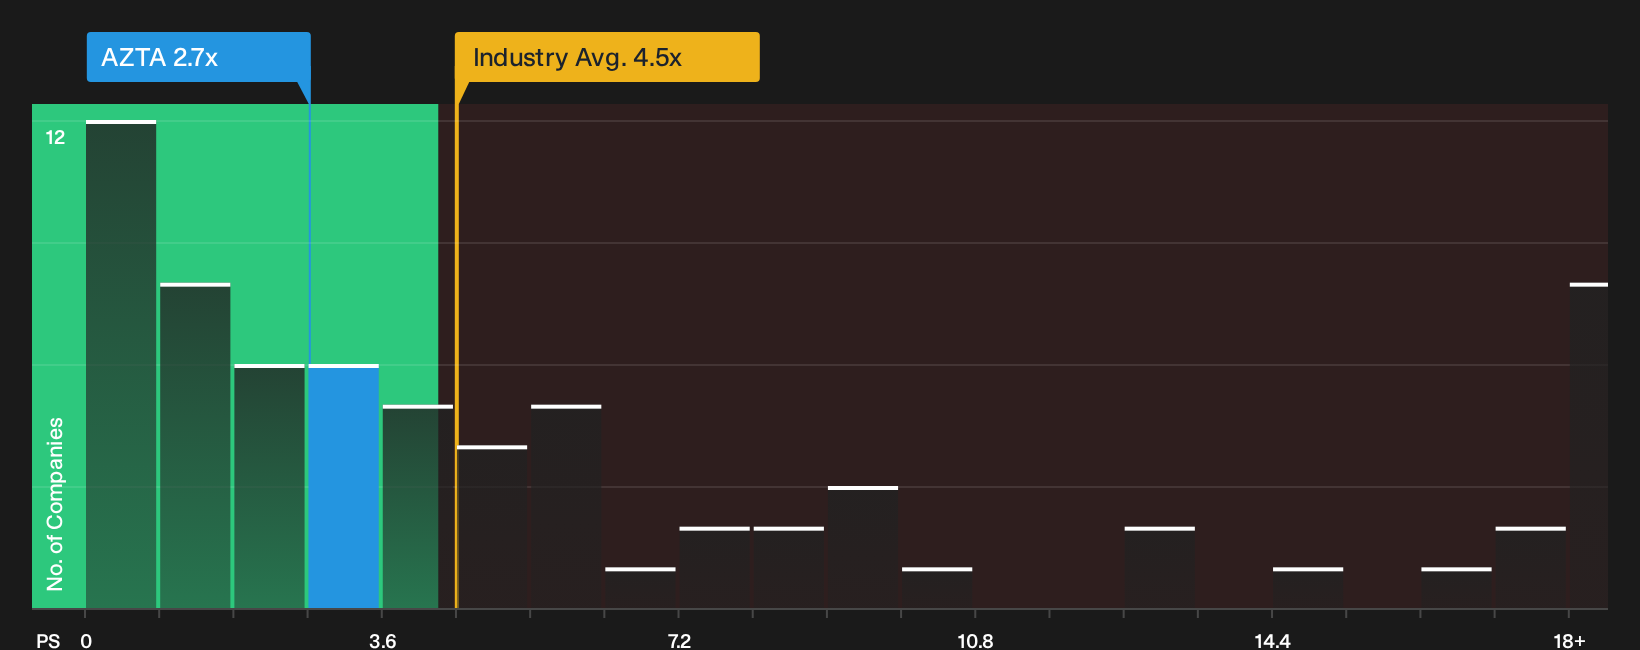
Azenta looks expensive against its own fair value models, yet its current P/S ratio of 2.7x tells a different story. That figure sits well below the US Life Sciences peer average of 4.5x and slightly under the 2.9x fair ratio, which suggests the market is not pricing this stock aggressively. Is the crowd underestimating the potential, or are the lower multiples simply a cushion for execution risk and past losses?
For a closer look at how this pricing gap compares with detailed valuation work, including peer checks, see See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
The debate around Azenta is already heated, so treat this as a prompt to check the numbers yourself and decide if the optimism holds up. Move quickly, review the key positives, and pressure test your own thesis with the 2 key rewards.
Looking for more investment ideas beyond Azenta?
Do not stop with Azenta. Use this momentum to widen your watchlist with fresh opportunities that match your risk appetite and income goals.
- Target resilient potential by scanning a 32 resilient stocks with low risk scores that keeps financial stability front and center while you assess future prospects.
- Hunt for mispriced quality using the 20 high quality undiscovered gems built to surface under-the-radar companies with strong underlying fundamentals.
- Build a sturdier core portfolio by focusing on balance sheet strength through the list of solid balance sheet and fundamentals (25 results) that filters for cleaner finances and healthier cash positions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com