
Kroger (KR) Stock Looks Fairly Valued As Merger Lawsuit Questions Build
Kroger has delivered a 73.3% share price gain over the past 5 years, and recent legal and regulatory headlines now put a fresh spotlight on what investors are paying for its earnings. With the stock at US$60.74 after mixed shorter term returns, the question is whether that price still lines up with what the grocery group is actually earning today.
- The 73.3% return over 5 years raises the stakes for anyone asking if Kroger's current valuation is fully supported by its profit stream.
- Albertsons' more than US$9.3b lawsuit and scrutiny over the planned US$1.65b Giant Eagle acquisition can influence Kroger's future legal costs, integration spending and the timing of any earnings growth investors are hoping for.
- The analysts covering Kroger have run their own numbers. See what analysts think Kroger's shares could be worth.
The issue now is whether Kroger's present share price is justified by its earnings when judged against the Fair Ratio benchmark.
If this news has you reassessing what you are paying for Kroger's earnings, it can help to compare it with a wider set of 32 high quality undervalued stocks.
Is Kroger Fairly Priced on Earnings?
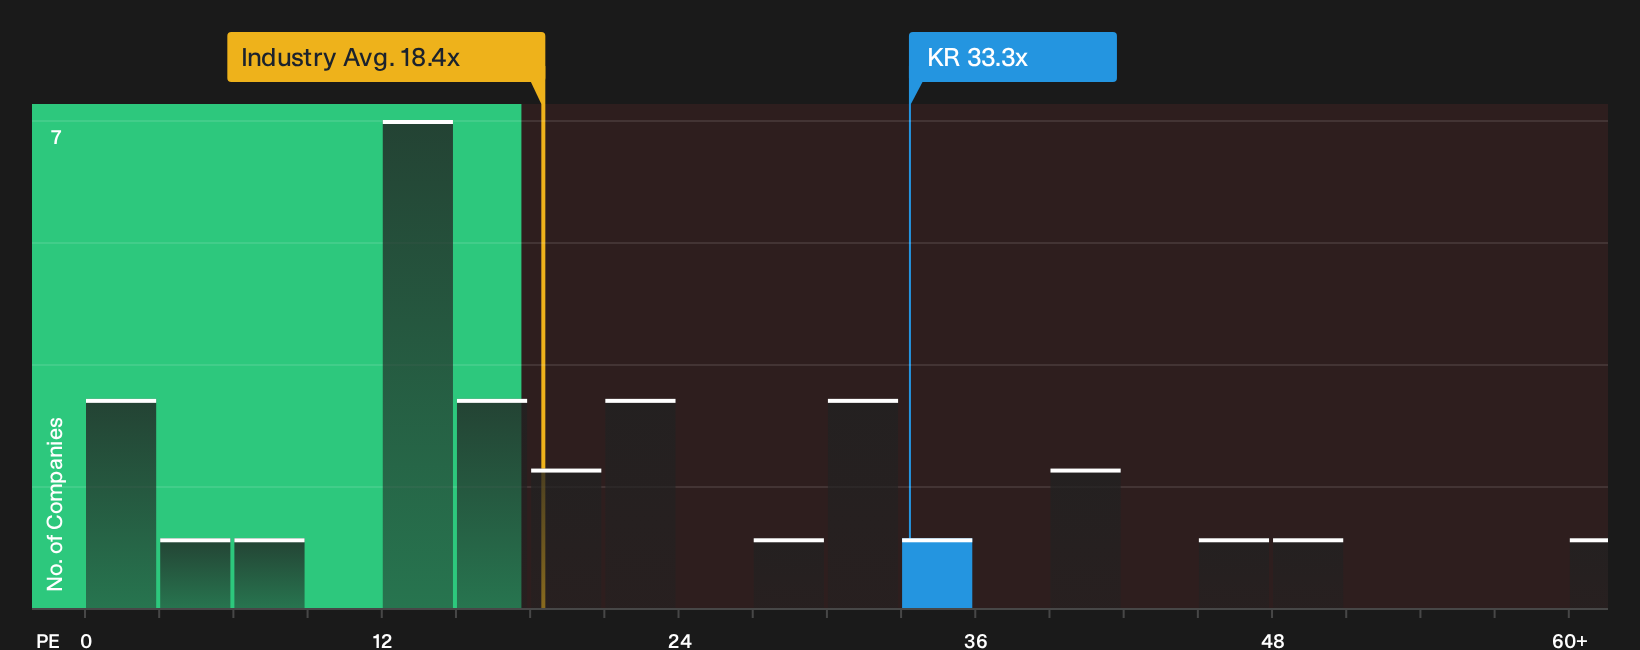
P/E fits Kroger because earnings are the main anchor for how investors usually appraise a mature supermarket chain. On this lens, the stock trades on a P/E of about 33.3x, which is higher than the Consumer Retailing sector average of roughly 18.4x but below the peer group marker of about 40.2x. That places Kroger in a kind of middle ground, where the market is willing to pay more than for the typical retailer, yet not at the very top of the peer range.
The Fair Ratio model, which gauges the multiple you might expect given Kroger's size, margins, sector and risk profile, puts the current P/E close to what that framework would imply. Despite the over US$9.3b Albertsons lawsuit hanging over the story, the earnings multiple still lines up broadly with that tailored benchmark rather than flashing an extreme premium or discount. Explore the numbers behind Kroger's P/E valuation.
The Kroger Narrative: What Would Justify Today's Price?
Narratives pick up where Kroger's valuation puzzle leaves you by spelling out which future paths for growth, margins and earnings would need to play out for the stock to look meaningfully richer or cheaper than today on Simply Wall St's Community page. Each one turns Kroger's fair value into a clear, trackable hypothesis about the business so you can see how that idea holds up as new information arrives.
Community views on Kroger are split between a cost-driven upside story and a more cautious read on how much of that progress reaches margins.
Bull case: 11% undervalued
"A multiyear cost optimization program, with cost of goods sold savings running about 30% ahead of plan, gives Kroger room to keep investing..."
Discover why this Narrative puts Kroger at 11% undervalued.
Bear case: 7% overvalued
"Although Kroger is seeing strong growth in e-commerce and has reached profitability in this channel, including media, continued higher transportation and fuel costs could limit how much of this progress flows through to net margins and earnings..."
Explore why this Narrative puts Kroger at 7% overvalued.
The Kroger share price is only one piece of the decision
Before you treat Kroger's valuation as the whole story, it is worth asking who is actually steering the business, how their rewards are structured and whether that lines up with your expectations. See who runs Kroger and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com