
TeraWulf (WULF), What Is Behind The Fresh Attention?
TeraWulf expands Muskie power capacity and timeline
TeraWulf (WULF) stock is back in focus after the company amended its electric service agreement with Kentucky Power, doubling contracted capacity at its Muskie Data Campus and pulling forward the second phase of development.
The latest Muskie announcement lands after a choppy run for TeraWulf, with the share price down 21.09% over the past month and 31.80% over 90 days, yet still showing a 3.69% year to date share price gain and a very large 3-year total shareholder return of 965.32%. This indicates that longer term performance has been strong, while shorter term sentiment has cooled as investors reassess growth expectations and risk around large scale power and infrastructure commitments.
Compare TeraWulf's Muskie build out with other power hungry AI infrastructure plays by scanning our hand picked 92 AI infrastructure stocks that are also racing to lock in long term capacity.
TeraWulf has secured significantly more power at Muskie while the share price has eased. Does it make more sense to increase exposure now, or wait for a potentially lower entry point for the same growth plan?
Most Popular Narrative: 61% Undervalued
TeraWulf's most followed narrative pegs fair value at $33.69 against a last close of $13.21, so the story leans heavily toward mispricing driven by long term lease economics and contracted power.
TeraWulf's recent multi-billion-dollar, multi-year hyperscale hosting agreements (for example, with Fluidstack and Google), mark a significant shift from a pure bitcoin mining model toward diversified, contracted revenue streams in high-demand digital infrastructure. This supports higher revenue visibility and reduces sensitivity of earnings to bitcoin price volatility.
See why 146 investors see TeraWulf as 61% undervalued.
Result: Fair Value of $33.69 (UNDERVALUED)
Still, the TeraWulf narrative leans heavily on capital intensive AI and HPC buildouts, and on tenants like Anthropic delivering on very large, long term lease commitments.
Find out about the key risks to this TeraWulf narrative.
Another View: What TeraWulf’s P/S Ratio Is Telling You
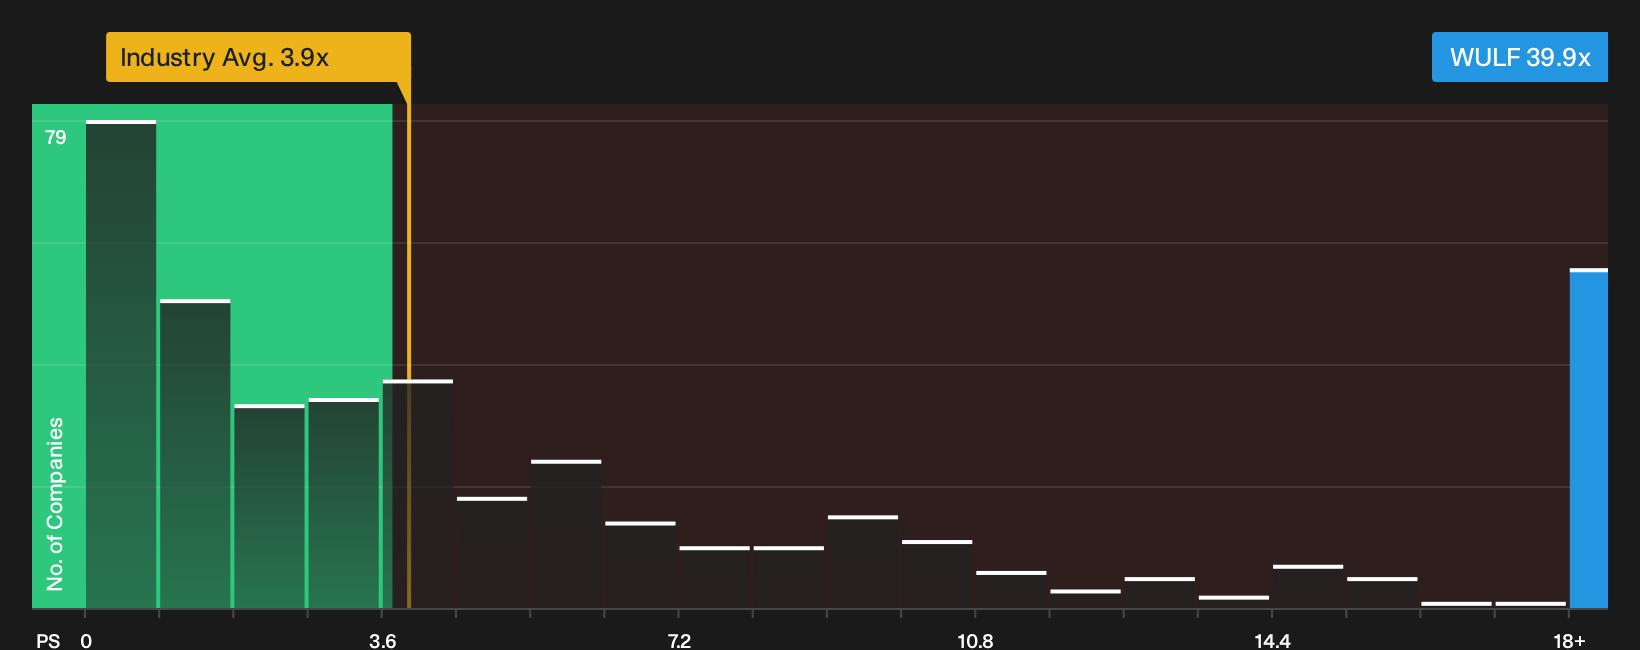
Look away from fair value for a moment and the simple sales multiple paints a much tougher picture for TeraWulf. The stock trades on a P/S of 39.9x, compared with 3.9x for the wider US Software sector, 11.5x for peers, and a fair ratio of 16.9x that the market could move toward over time.
That kind of premium implies investors are already paying up heavily for the AI and data center story. This raises the question of how much execution risk is really priced in if expectations around growth or leasing ever cool.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around TeraWulf is clearly split, which is exactly why it pays to move early and test the numbers yourself instead of just following the crowd. To weigh the upside story against the areas that are causing concern, start with the 1 key reward and 5 important warning signs.
Looking for more TeraWulf-size ideas?
If you like the TeraWulf story but want a wider watchlist, use the Simply Wall Street Screener to explore opportunities aligned with your approach.
- Use the 32 high quality undervalued stocks to find higher quality candidates that combine solid fundamentals with what may be discounted prices.
- Use the 32 resilient stocks with low risk scores to focus on companies that appear to have more resilient characteristics and lower overall risk profiles.
- Use the 20 high quality undiscovered gems to look for under the radar opportunities with strong financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com