
Wyndham Hotels & Resorts (WH) Expands Sports Illustrated Resorts, Is The 25% Upside Justified?
Travel + Leisure Co. is expanding its Sports Illustrated Resorts concept through a deeper collaboration with Wyndham Hotels & Resorts (WH), with the goal of building and scaling sports themed hotels and mixed use destinations.
For Wyndham Hotels & Resorts, this Sports Illustrated Resorts tie up comes after a mixed run on the market. The 30-day share price return of 5.93% contrasts with a 90-day share price decline of 7.11% and a 1-year total shareholder return decline of 4.09%. Taken together, these figures indicate that recent momentum has picked up again, even as longer term performance has been subdued.
Spot emerging hospitality plays alongside Wyndham Hotels & Resorts by screening for 20 high quality undiscovered gems that could be quietly building similar growth platforms around powerful consumer brands.The rebound in Wyndham Hotels & Resorts after a weaker stretch can look like a clean vote of confidence in the Sports Illustrated Resorts tie up, or just a sentiment swing chasing headlines. The valuation tells you which story fits better.
Most Popular Narrative: 25% Undervalued
On the most followed view, Wyndham Hotels & Resorts carries a fair value of about $97.59 against a last close of $73.42. This frames the Sports Illustrated Resorts partnership inside a wider story about mix, fees and capital-light earnings.
Record net room growth and a development pipeline of about 261,000 rooms with roughly a 30% FeePAR premium over the current system create ongoing mix uplift toward higher fee hotels, which can support faster growth in fee-related revenue and EBITDA for Wyndham Hotels & Resorts.
See why 2 investors see Wyndham Hotels & Resorts as 25% undervalued.
Result: Fair Value of $97.59 (UNDERVALUED)
Still, the Wyndham Hotels & Resorts story can crack if a weaker U.S. RevPAR cycle lingers or if legal and reputational issues escalate into heavier costs.
Find out about the key risks to this Wyndham Hotels & Resorts narrative.
Another View: What Wyndham Hotels & Resorts’ P/E Is Really Saying
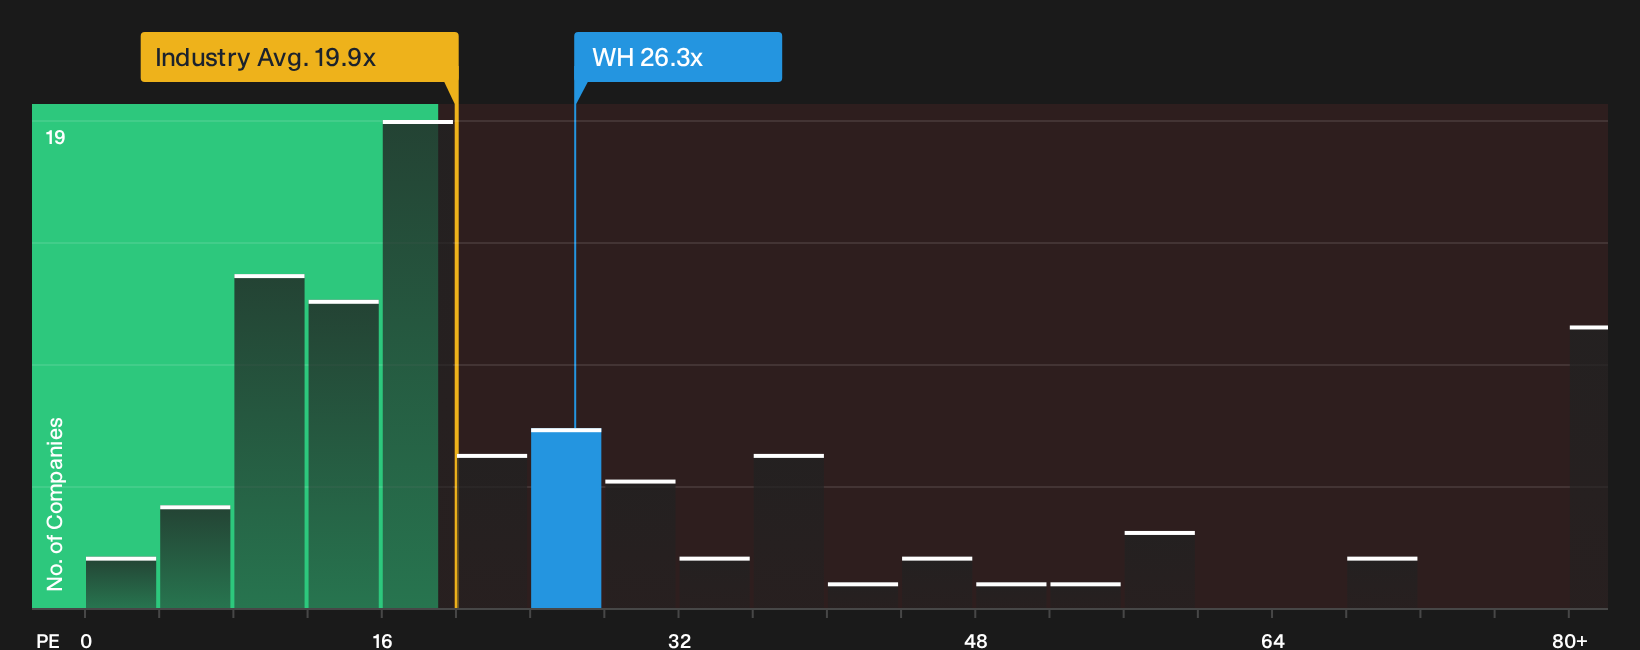
The first story paints Wyndham Hotels & Resorts as about 25% undervalued on fair value. The P/E picture is trickier. At 26.3x, the shares trade above both the US Hospitality industry on 19.5x and a fair ratio of 21.2x, even though they sit below a 40.6x peer average. That mix points to both downside risk if sentiment cools and upside if the market leans toward richer peers. Which scenario do you think is more realistic for a franchise-heavy hotel group with uneven recent earnings?
To pressure test that P/E view against the rest of your watchlist, compare it with companies on the same footing using our valuation breakdown, then decide whether you see a margin of safety or a premium you are comfortable paying See what the numbers say about this price — find out in our valuation breakdown..
For a visual snapshot of how Wyndham Hotels & Resorts screens against its industry on this metric today, review the latest relative valuation chart
Next Steps
With sentiment on Wyndham Hotels & Resorts clearly divided between risks and rewards, use the data to move quickly and build your own conviction around 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Wyndham Hotels & Resorts?
If you stop with Wyndham Hotels & Resorts, you miss a wider set of opportunities that could fit your goals even better. Consider widening your search intelligently.
- Target potential mispricing by scanning companies that combine strong fundamentals with attractive valuations using the 32 high quality undervalued stocks.
- Focus on income-oriented opportunities by reviewing companies offering resilient payouts and higher yields through the 8 dividend fortresses.
- Prioritize resilience by filtering for businesses with robust balance sheets and solid fundamentals via the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com