
Greencore Group (LSE:GNC) On Its Profit Upgrade And The Case For More Value
Greencore Group (LSE:GNC) caught investor attention after management lifted its full year profit outlook again, pointing to volume growth ahead of the wider market and improving margins.
Greencore Group’s upgraded outlook has arrived alongside a sharp shift in sentiment, with the share price climbing 27.2% over the past 90 days and a 3-year total shareholder return of about 3x, suggesting momentum has been rebuilding after a tougher earlier period.
Scan how Greencore Group’s profit upgrade compares with other potential breakout ideas in our hand picked list of 5 high quality undiscovered gems.
After a 27.2% rise in 90 days and a profit upgrade, Greencore Group now trades at a wide gap to both analyst targets and intrinsic estimates. So where does a reasonable fair value anchor actually land?
Most Popular Narrative: 25% Undervalued
Greencore Group’s most followed valuation story pegs fair value at £3.60, above the last close of £2.68. This framing puts the current rally in a different light.
The targeted £80m of annual cost synergies from the Bakkavor acquisition by January 2029, with specific interim milestones through January 2028, creates further headroom for structural reduction in unit costs that can contribute to higher net margins and operating profit as these benefits phase in.
See why 2 investors see Greencore Group as 25% undervalued.
Result: Fair Value of £3.60 (UNDERVALUED)
Still, the bullish Greencore Group story can crack if subdued U.K. grocery demand lingers or if working capital outflows continue to squeeze free cash flow.
Find out about the key risks to this Greencore Group narrative.
Another View: Greencore Group On Sales-Based Valuation
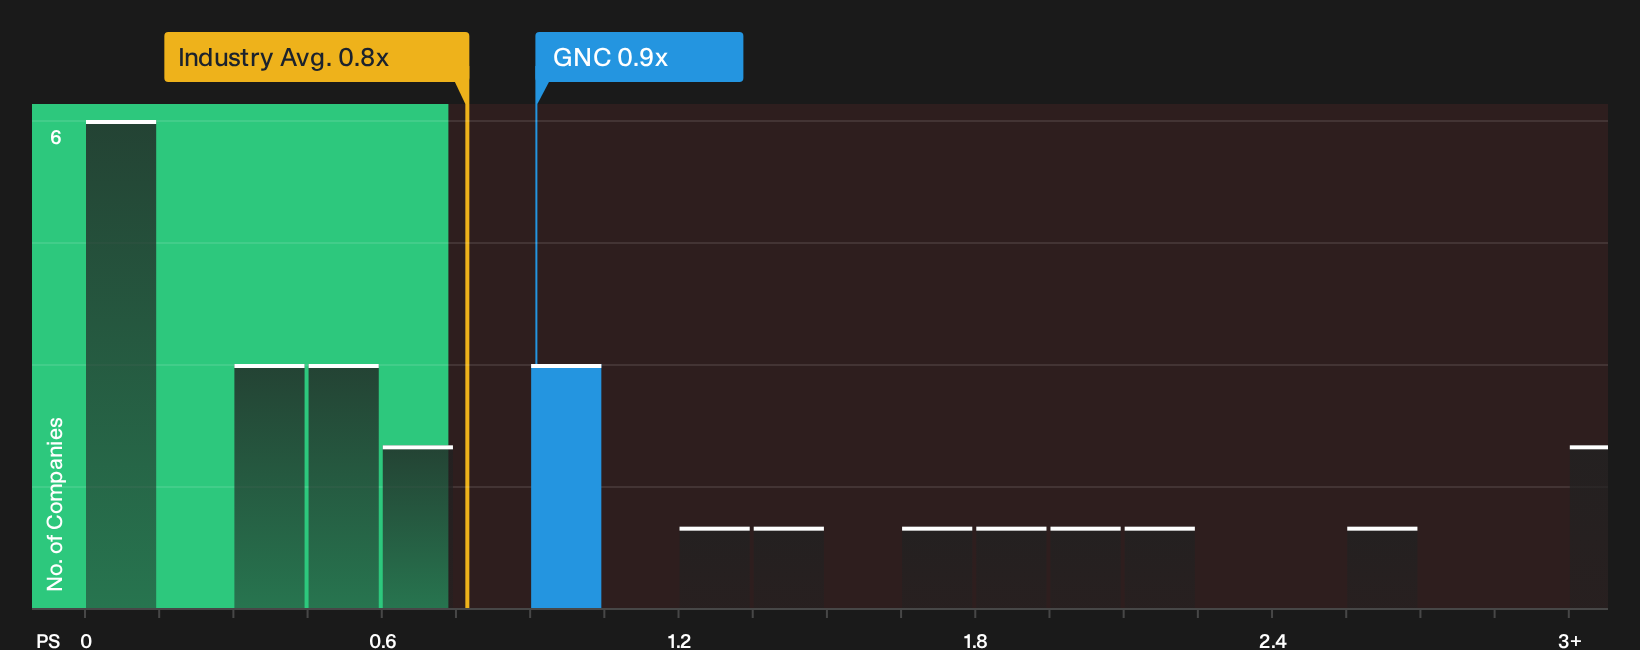
Greencore Group might look inexpensive on cash flow models, yet the picture changes when you focus on its P/S ratio. The shares trade on 0.9x sales, which is slightly above the European Food industry at 0.8x, but below a fair ratio of 1.7x that the market could eventually lean toward. That combination of a mild premium to the sector and a discount to the fair ratio highlights both valuation risk and scope for repricing. Which side of that trade-off do you think is more important today?
See what the numbers indicate about this price in our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages in the data so far, with both concerns and bright spots around Greencore Group, mean you should move quickly and test the numbers against your own expectations. To weigh both sides in one place, start with the 3 key rewards and 4 important warning signs.
Want more ideas beyond Greencore Group?
If Greencore Group has sharpened your focus on valuation and momentum, now is the moment to widen your watchlist using targeted stock screens.
- Target income resilience by reviewing companies in the 2 dividend fortresses that may help support a steadier cash return profile.
- Hunt for quality at a discount with the 8 high quality undervalued stocks and see which businesses pair stronger fundamentals with prices that lag their underlying metrics.
- Reduce portfolio stress by scanning the 4 resilient stocks with low risk scores and highlight shares with more robust balance sheets and lower risk scores before others catch on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com