
What Lincoln Electric Holdings (LECO)'s Raised Sales Guidance Means For Shareholders
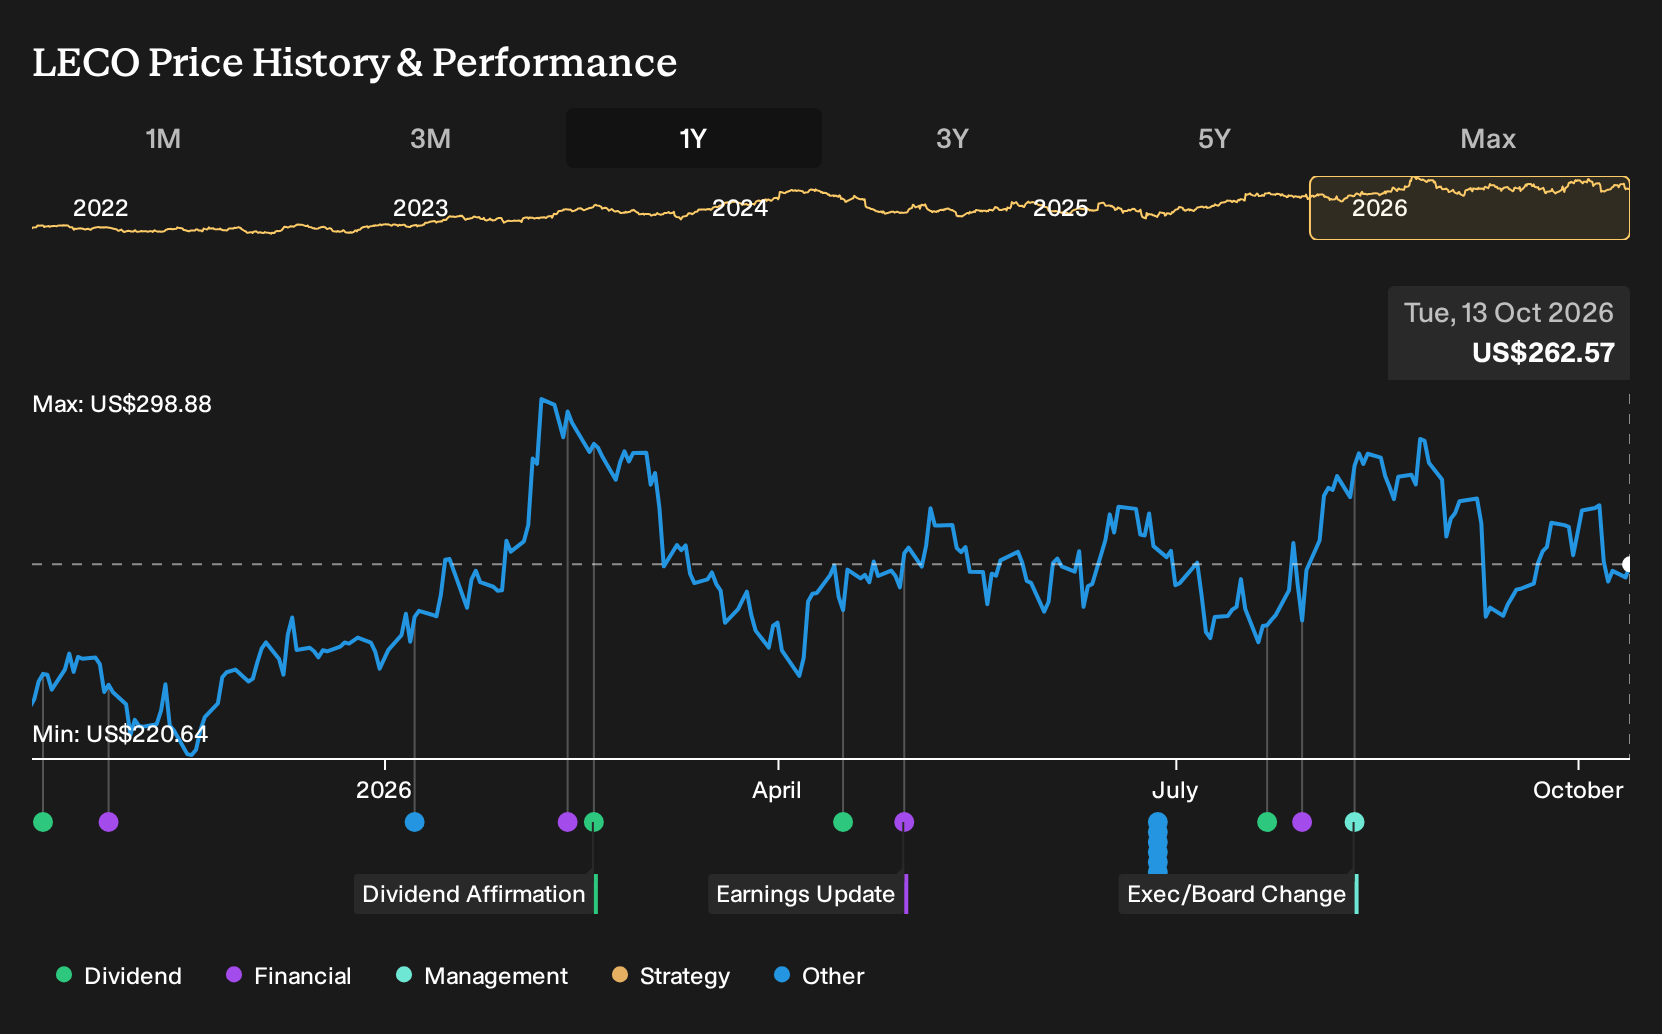
- Lincoln Electric Holdings recently reported revenue that was 12% higher year on year and ahead of analyst expectations by 4.6%, raised full year 2026 net sales growth guidance, and highlighted strong demand in the Americas alongside a record order backlog and rapidly expanding automation sales.
- The company paired these results with a focus on its RISE efficiency model, tight capital spending, a quarterly dividend, and a target of 100% cash conversion, which together indicate management attention on both profitable growth and disciplined balance sheet management.
- This article examines how Lincoln Electric's investment narrative is influenced by stronger Americas demand and raised full year growth guidance.
Scan how Lincoln Electric Holdings fits into the broader industrial story by comparing it with a hand picked set of 90 robotics and automation stocks that are riding the same push toward automation and efficiency.
Lincoln Electric Holdings Investment Narrative Recap
For a shareholder in Lincoln Electric Holdings, the core belief is that welding, cutting and automation demand can support steady earnings growth while the RISE efficiency model lifts profitability. The recent revenue beat, raised 2026 net sales growth guidance and strong Americas demand reinforce that operating backdrop. The key near term swing factor is execution in automation and the broader RISE program, which still carry integration and delivery risk.
The biggest operational worry right now remains cost inflation and pricing. Management is leaning on disciplined price actions to stay neutral on metal and logistics costs. If that balance tilts or automotive demand stays weak, margins could come under pressure even with a record backlog in place.
The most relevant datapoint to watch is the raised full year 2026 net sales growth guidance, tied to strengthening Americas demand and a record order book. That update sits directly on top of the existing catalyst around a growing automation backlog with six to nine months of visibility into higher value systems and cobots.
As long as Lincoln Electric Holdings keeps converting that backlog into higher margin automation revenue while holding incremental margins in the low 20% range or better, the RISE framework and automation push remain the central drivers. If persistent inflation, Middle East project delays or sustained automotive softness drag on that conversion, the path to higher international and automation margins becomes harder and execution risk rises.
Lincoln Electric Holdings is currently framed around analysts expecting its revenue to rise 6.9% per year and earnings to move from US$553.6 million today to US$778.7 million by 2029, a gain of about US$225 million. That profile is underpinned by a forecast for US$5.5b of revenue and US$778.7 million of earnings in 2029.
Uncover why Lincoln Electric Holdings' fair value indicates a 16% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses heavily on Lincoln Electric Holdings’ automation story. The most bullish analysts were already modeling 8.8% annual revenue growth and earnings of US$846.9 million by 2029 before this latest guidance shift. That is far more optimistic than consensus, and the new results could easily push those projections, or the caution around them, in a different direction. Readers like you can use that range in expectations to assess which version of the future feels more realistic.
Explore 4 other Lincoln Electric Holdings fair value estimates, including one that suggests as much as 39% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your independent analysis and research.
- A great starting point for your Lincoln Electric Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Lincoln Electric Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lincoln Electric Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Lincoln Electric Holdings?
Once you have formed a view on Lincoln Electric Holdings, it can help to compare those conclusions with other companies that match your preferred style of investing using the Simply Wall St Screener.
- If you prioritize quality at a discount, scan through 32 high quality undervalued stocks that combine strong fundamentals with prices that may not fully reflect their financial profile.
- If income and consistency matter most to you, review 8 dividend fortresses that offer higher yields while aiming to keep payouts supported by underlying cash flows.
- If balance sheet resilience is your focus, explore the list of solid balance sheet and fundamentals (25 results) to compare financially robust companies that may better match your risk tolerance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com