
Penguin Solutions (PENG) Lifts 2027 Guidance On A Valuation Story Still Up For Debate
Penguin Solutions guidance hike puts 2027 expectations in focus
Penguin Solutions (PENG) has moved into the spotlight after management raised earnings guidance for fiscal 2027. The company updated investors on expected net sales and diluted EPS that are above prior internal projections.
The raised 2027 outlook has arrived alongside a sharp re-rating in Penguin Solutions, with the share price up 52.85% over the past month and 285.60% year to date. The 3-year total shareholder return of 427.67% points to strong longer term momentum.
Scan other AI infrastructure players showing similar guidance momentum with our hand-picked list of 92 AI infrastructure stocks as you assess how Penguin Solutions fits into the broader theme.
After a move like this and with a richer 2027 earnings outlook in hand, does Penguin Solutions still offer enough upside to compensate for the fresh risks buyers are taking on at today’s price?
Most Popular Narrative: 6% Undervalued
Against a last close of $78.20, the most followed narrative places Penguin Solutions fair value at $83.57, suggesting the recent guidance lift still leaves some headroom once future growth, margins and risk are evaluated through a discounted cash flow lens using a 12.48% discount rate.
Accelerating adoption of AI and high-performance computing across major enterprise verticals (financial services, energy, biotech, federal, and neo-cloud providers) is associated with robust demand for turnkey compute infrastructure, as evidenced by rising customer bookings and a diversified pipeline, which may support revenue trends.
See why 27 investors see Penguin Solutions as 6% undervalued.
Result: Fair Value of $83.57 (UNDERVALUED)
Still, the narrative can crack if margin pressure persists in Advanced Computing, or if large, lumpy AI deals in Penguin Solutions, in terms of timing and size, disappoint expectations.
Find out about the key risks to this Penguin Solutions narrative.
Another View: SWS DCF Signals Caution On Penguin Solutions
Analysts see Penguin Solutions as about 6% undervalued based on future earnings and a P/E of 19.6x. The SWS DCF model paints a very different picture, with a future cash flow value of $37.49 versus a $78.20 share price, which points to an overvalued stock instead.
Both lenses use reasonable inputs, yet they arrive at opposite conclusions on upside and risk. For your own work, the key question is simple: Do you put more weight on cash flows discounted over time, or on earnings power a few years out and the multiple the market might be willing to pay for it?
Look into how the SWS DCF model arrives at its fair value.
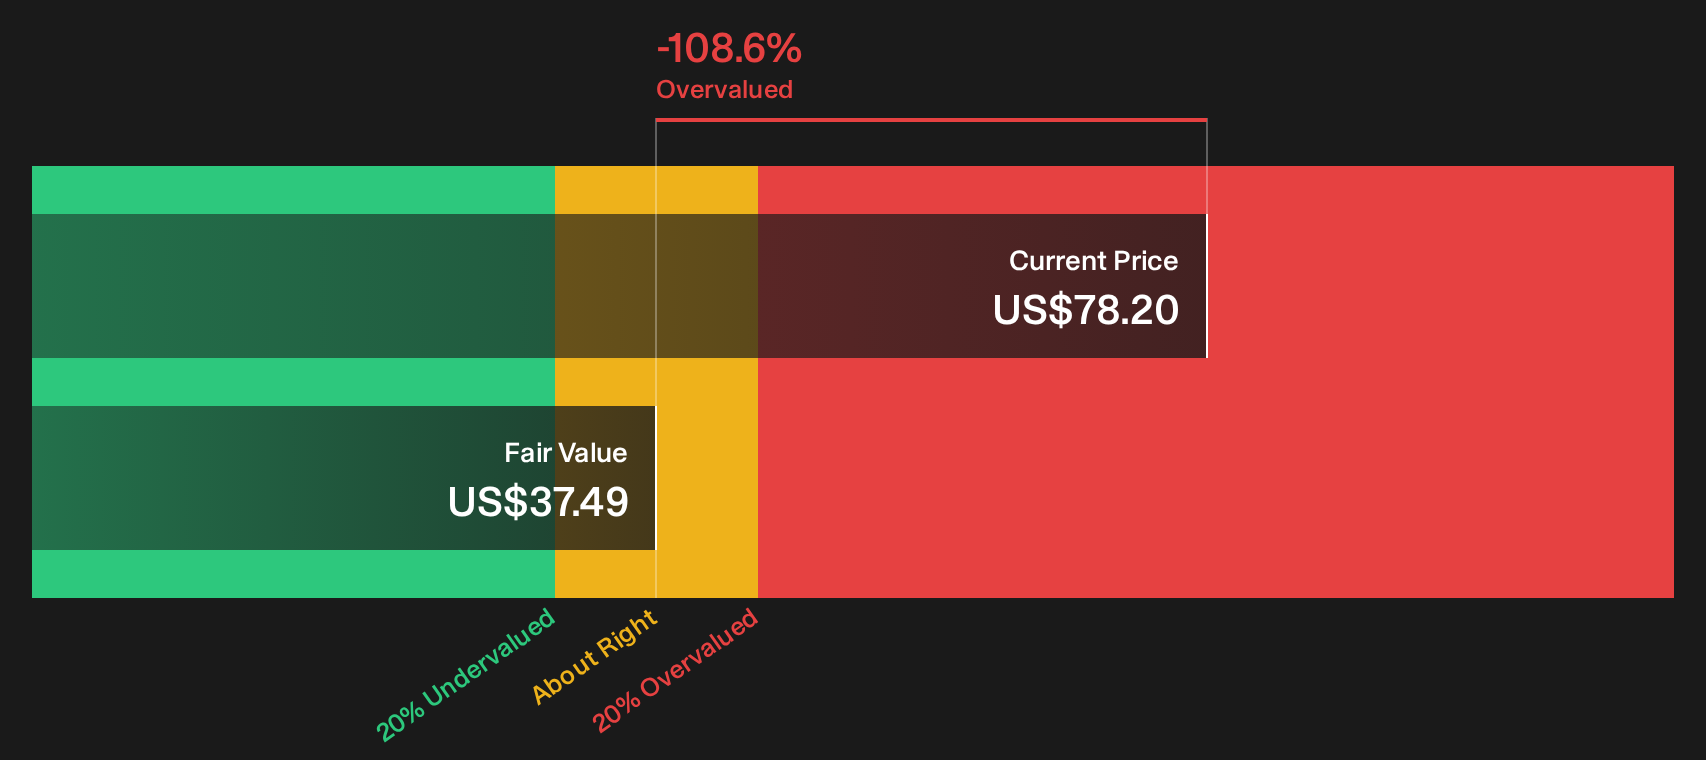
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Penguin Solutions for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Penguin Solutions is split, and that is exactly when doing your own homework matters most, so move fast, review the data and weigh both the 4 key rewards and 2 important warning signs.
Looking for more Penguin Solutions style ideas?
If Penguin Solutions has sharpened your appetite for focused opportunities, do not stop here. Use the Simply Wall St Screener to surface fresh ideas that match your risk and return preferences.
- Target potential mispricing across the market and shortlist companies that combine quality fundamentals with appealing valuations using our curated 20 high quality undiscovered gems.
- Strengthen your core holdings by filtering for businesses with cleaner finances and sturdier funding profiles through the analytical lens of the list of solid balance sheet and fundamentals (25 results).
- Lock in more predictable income streams by zeroing in on companies with higher yields that still aim for resilience using the focused universe of 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com