
Jiangxi Copper (SEHK:358) Secures A Three Year Supply Deal, Is It 48% Below Fair Value?
Jiangxi Copper (SEHK:358) has signed a three-year agreement to supply JCC Group with key copper, lead, zinc and related materials, alongside industrial services, starting January 2027. Investors now have fresh information on contracted demand.
Recent trading has been softer for Jiangxi Copper, with the share price down 3.67% over the past month and 25.41% lower year to date, while a 0.80% 3 month share price gain alongside a 3 year total shareholder return of 224.51% suggests long term momentum remains strong, even as shorter term sentiment cools around the latest contract news.
Compare Jiangxi Copper’s new long-term supply visibility with peers by scanning our hand picked 16 top copper producer stocks that are also tied into global demand for the metal.
Recent weakness in Jiangxi Copper’s share price sits against a long run of strong shareholder returns and a fresh multi year supply deal that tightens revenue visibility. Is the latest move about fundamentals or mood, and what does current pricing imply?
Preferred P/E of 8.3x: Is it justified for Jiangxi Copper?
On Simply Wall St’s checks, Jiangxi Copper trades on a P/E of 8.3x, which screens as good value relative to both its peers and the wider Hong Kong Metals and Mining group. That multiple sits against a share price of HK$32.58 and an SWS DCF value estimate of HK$62.01. This implies the stock is trading at a 47.5% discount to that cash flow based fair value and below several benchmark comparison points.
The P/E ratio compares what the market is willing to pay today for each unit of earnings. For a miner such as Jiangxi Copper, where profits can be sensitive to commodity pricing and operating costs, the P/E is one of the cleanest shortcuts for how investors are pricing the current earnings run rate relative to other Metals and Mining businesses.
Jiangxi Copper’s 8.3x P/E is lower than the Hong Kong Metals and Mining sector average of 9.6x and below the peer group average of 10.3x. The valuation is also beneath an estimated fair P/E of 9.1x that the SWS model suggests the market could rationally move toward based on fundamentals. This points to investors applying a clear discount compared with both sector norms and that fair ratio reference point. Result: Price-to-Earnings of 8.3x (UNDERVALUED)
Explore the SWS fair ratio for Jiangxi Copper.
Still, any pressure on copper pricing or higher operating costs could keep Jiangxi Copper’s P/E subdued and challenge the idea of a simple valuation catch up.
Find out about the key risks to this Jiangxi Copper narrative.
Another view on Jiangxi Copper’s value
The SWS DCF model points to a fair value of HK$62.01 for Jiangxi Copper, almost double the current HK$32.58 share price. This suggests the stock may be materially undervalued on future cash flows. If earnings or cash conversion shift, could that gap close or widen from here?
Look into how the SWS DCF model arrives at its fair value.
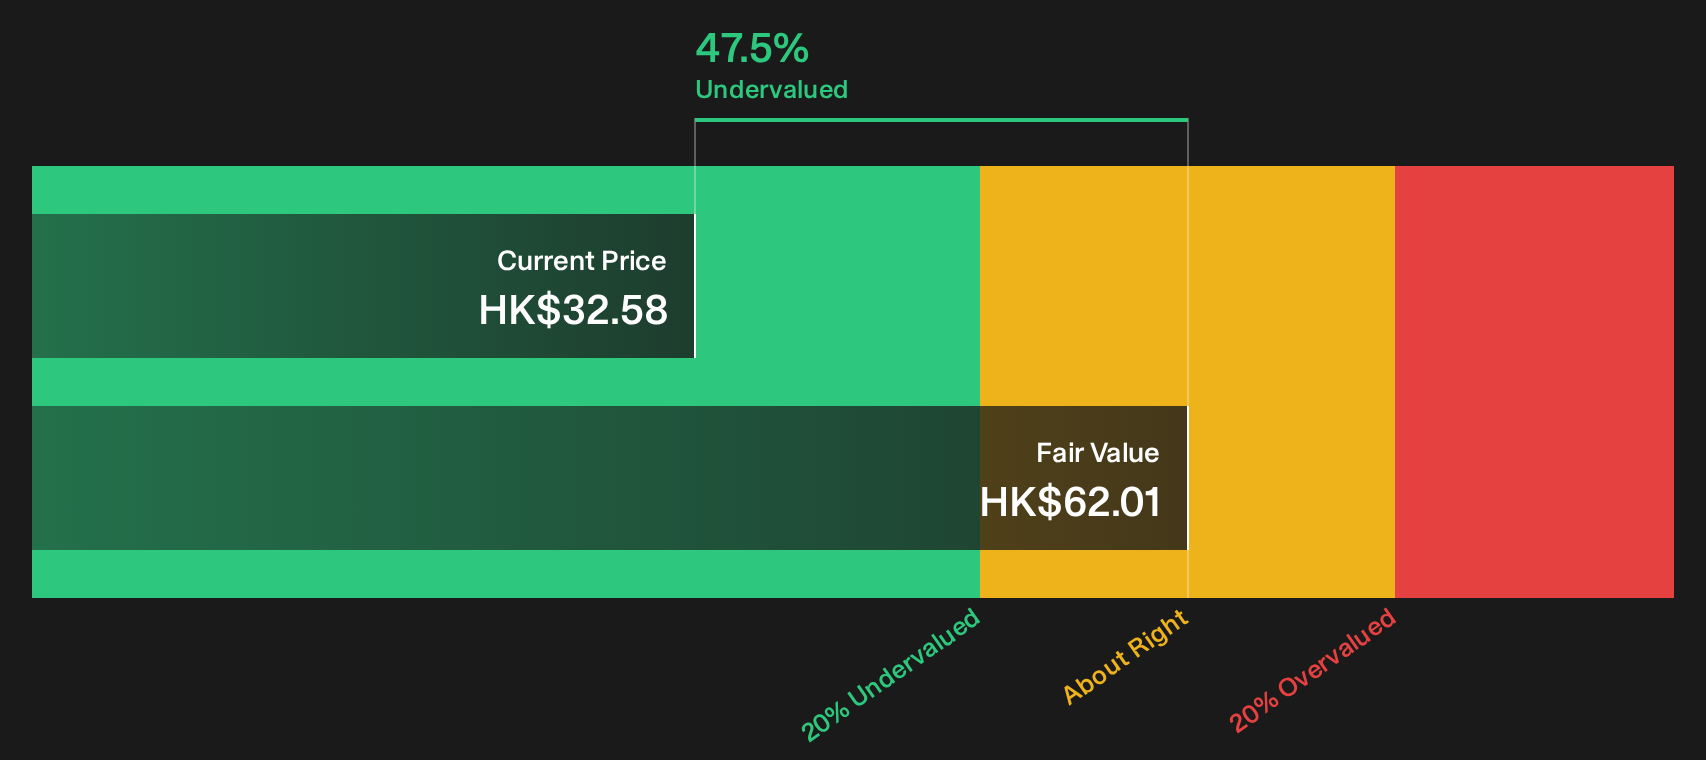
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Jiangxi Copper for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 183 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Jiangxi Copper looks mixed. Treat this as a starting point and move quickly to form your own view using the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Jiangxi Copper?
If you stop at Jiangxi Copper, you risk missing other opportunities that fit your style. Let the data do the heavy lifting on your shortlist.
- Target potential mispricings by scanning a 183 high quality undervalued stocks that filters for quality alongside attractive valuations.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (203 results) that keeps balance sheet strength front and center.
- Hunt for tomorrow’s leaders early by checking a 617 high quality undiscovered gems built around strong fundamentals before the crowd pays attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com