
Here's Why We're Not Too Worried About Eagle Nuclear Energy's (NASDAQ:NUCL) Cash Burn Situation
We can readily understand why investors are attracted to unprofitable companies. For example, biotech and mining exploration companies often lose money for years before finding success with a new treatment or mineral discovery. But the harsh reality is that very many loss making companies burn through all their cash and go bankrupt.
So, the natural question for Eagle Nuclear Energy (NASDAQ:NUCL) shareholders is whether they should be concerned by its rate of cash burn. In this article, we define cash burn as its annual (negative) free cash flow, which is the amount of money a company spends each year to fund its growth. The first step is to compare its cash burn with its cash reserves, to give us its 'cash runway'.
How Long Is Eagle Nuclear Energy's Cash Runway?
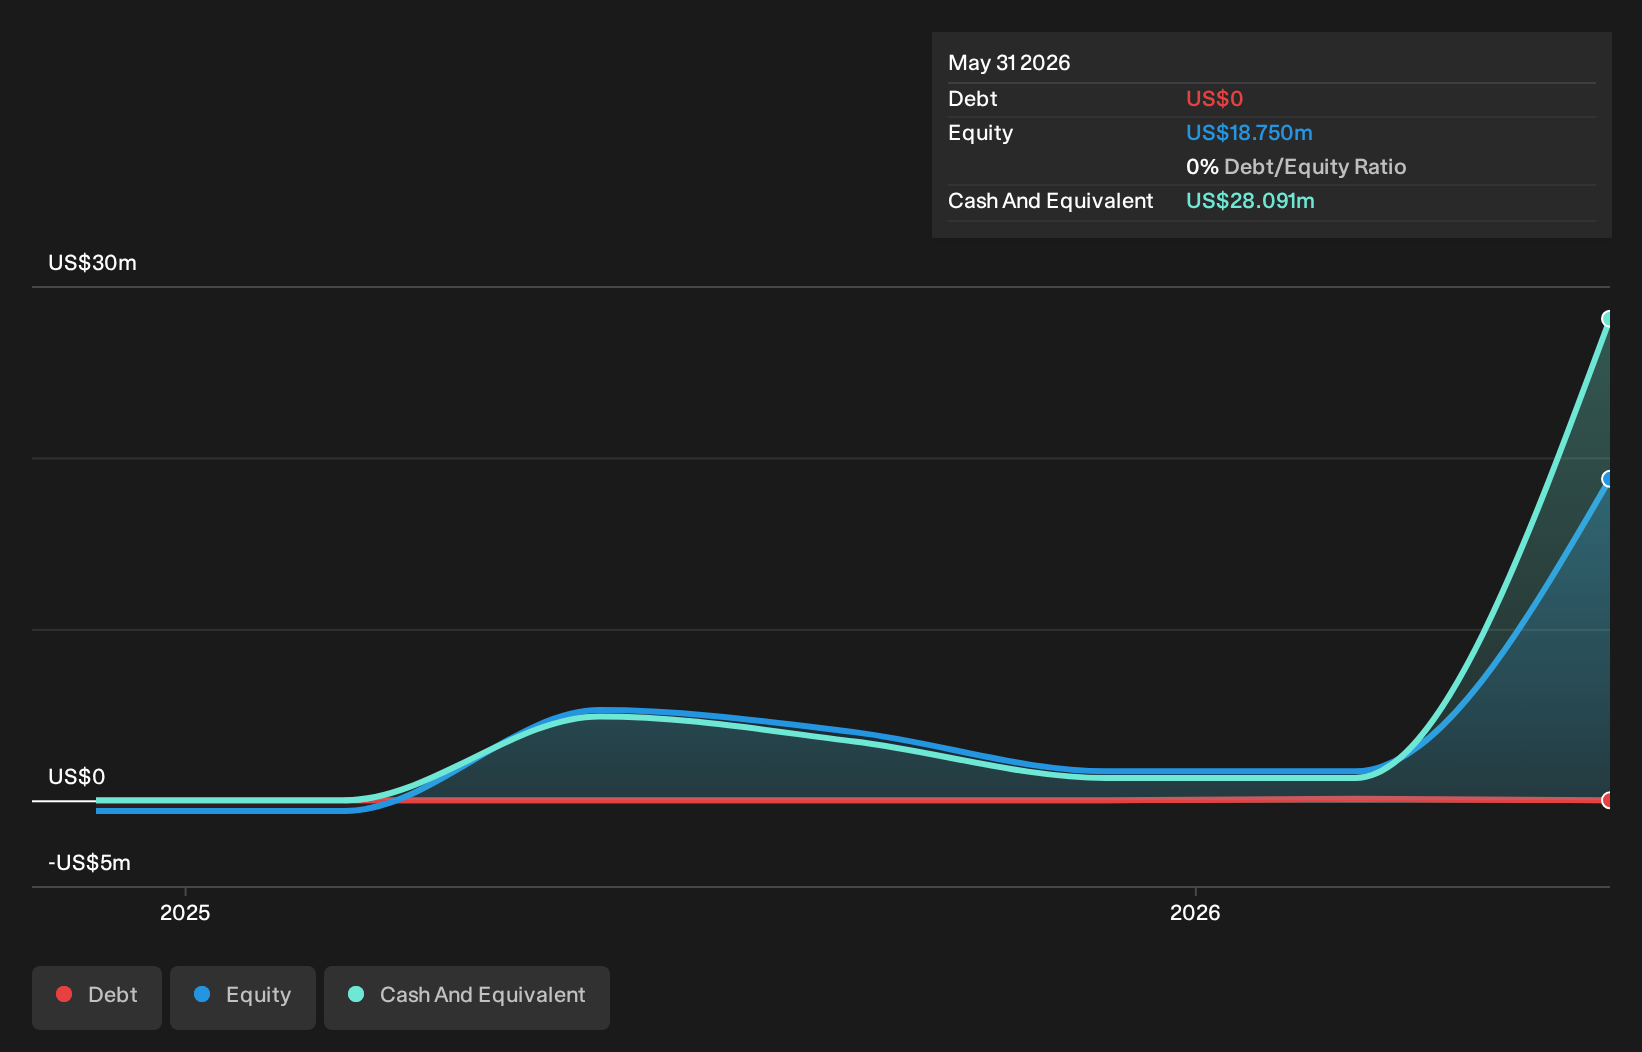
A cash runway is defined as the length of time it would take a company to run out of money if it kept spending at its current rate of cash burn. As at May 2026, Eagle Nuclear Energy had cash of US$28m and no debt. In the last year, its cash burn was US$8.7m. So it had a cash runway of about 3.2 years from May 2026. There's no doubt that this is a reassuringly long runway. You can see how its cash balance has changed over time in the image below.
Check out our latest analysis for Eagle Nuclear Energy
How Is Eagle Nuclear Energy's Cash Burn Changing Over Time?
Because Eagle Nuclear Energy isn't currently generating revenue, we consider it an early-stage business. Nonetheless, we can still examine its cash burn trajectory as part of our assessment of its cash burn situation. Remarkably, it actually increased its cash burn by 221% in the last year. Given that sharp increase in spending, the company's cash runway will shrink rapidly as it depletes its cash reserves. Eagle Nuclear Energy makes us a little nervous due to its lack of substantial operating revenue. We prefer most of the stocks on this list of stocks that analysts expect to grow.
How Hard Would It Be For Eagle Nuclear Energy To Raise More Cash For Growth?
While Eagle Nuclear Energy does have a solid cash runway, its cash burn trajectory may have some shareholders thinking ahead to when the company may need to raise more cash. Companies can raise capital through either debt or equity. Commonly, a business will sell new shares in itself to raise cash and drive growth. By looking at a company's cash burn relative to its market capitalisation, we gain insight on how much shareholders would be diluted if the company needed to raise enough cash to cover another year's cash burn.
Since it has a market capitalisation of US$167m, Eagle Nuclear Energy's US$8.7m in cash burn equates to about 5.2% of its market value. That's a low proportion, so we figure the company would be able to raise more cash to fund growth, with a little dilution, or even to simply borrow some money.
Is Eagle Nuclear Energy's Cash Burn A Worry?
As you can probably tell by now, we're not too worried about Eagle Nuclear Energy's cash burn. In particular, we think its cash runway stands out as evidence that the company is well on top of its spending. Although we do find its increasing cash burn to be a bit of a negative, once we consider the other metrics mentioned in this article together, the overall picture is one we are comfortable with. Considering all the factors discussed in this article, we're not overly concerned about the company's cash burn, although we do think shareholders should keep an eye on how it develops. Taking a deeper dive, we've spotted 3 warning signs for Eagle Nuclear Energy you should be aware of, and 2 of them are significant.
Of course Eagle Nuclear Energy may not be the best stock to buy. So you may wish to see this free collection of companies boasting high return on equity, or this list of stocks with high insider ownership.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.