
Iridium Communications (IRDM) Faces A Fresh Valuation Test On Cooling Momentum
Iridium Communications (IRDM) has drawn attention after a stretch of mixed share performance, with the price near US$46.73 and returns over the past month and past 3 months both in decline.
Short term momentum for Iridium Communications has cooled, with the share price down 4.7% over the past week and lower over the past quarter. However, the year to date share price return of 163.1% and 1 year total shareholder return of 150.7% still point to a stock where earlier optimism and changing views on future prospects have already played a major role in recent gains.
Scan beyond Iridium Communications and size up other high momentum movers and potential pullbacks with our hand picked 32 high quality undervalued stocks embedded with solid fundamentals.
The real question now is whether Iridium Communications’ sharp longer term gains and recent cooling spell still mirror the underlying satellite business, or mostly reflect sentiment that has already run ahead of fundamentals.
Most Popular Narrative: 11% Overvalued
Iridium Communications last closed at $46.73 compared with a narrative fair value of $42.00. This frames the current price against relatively demanding expectations on growth, margins and execution.
The current Rocket Lab transaction value of about $8 billion, or $54 per Iridium share, implies the market is already pricing in continued strong cash flow through 2030 and meaningful benefit from spectrum assets and new growth projects. This leaves limited room for upside if those expectations are not met.
See why 31 investors see Iridium Communications as 11% overvalued.
Result: Fair Value of $42.00 (OVERVALUED)
Still, the Iridium Communications story could shift quickly if assured PNT revenue rolls in more slowly than hoped or if IoT usage underwhelms early expectations.
Find out about the key risks to this Iridium Communications narrative.
Another View: Cash Flows Paint a Very Different Picture
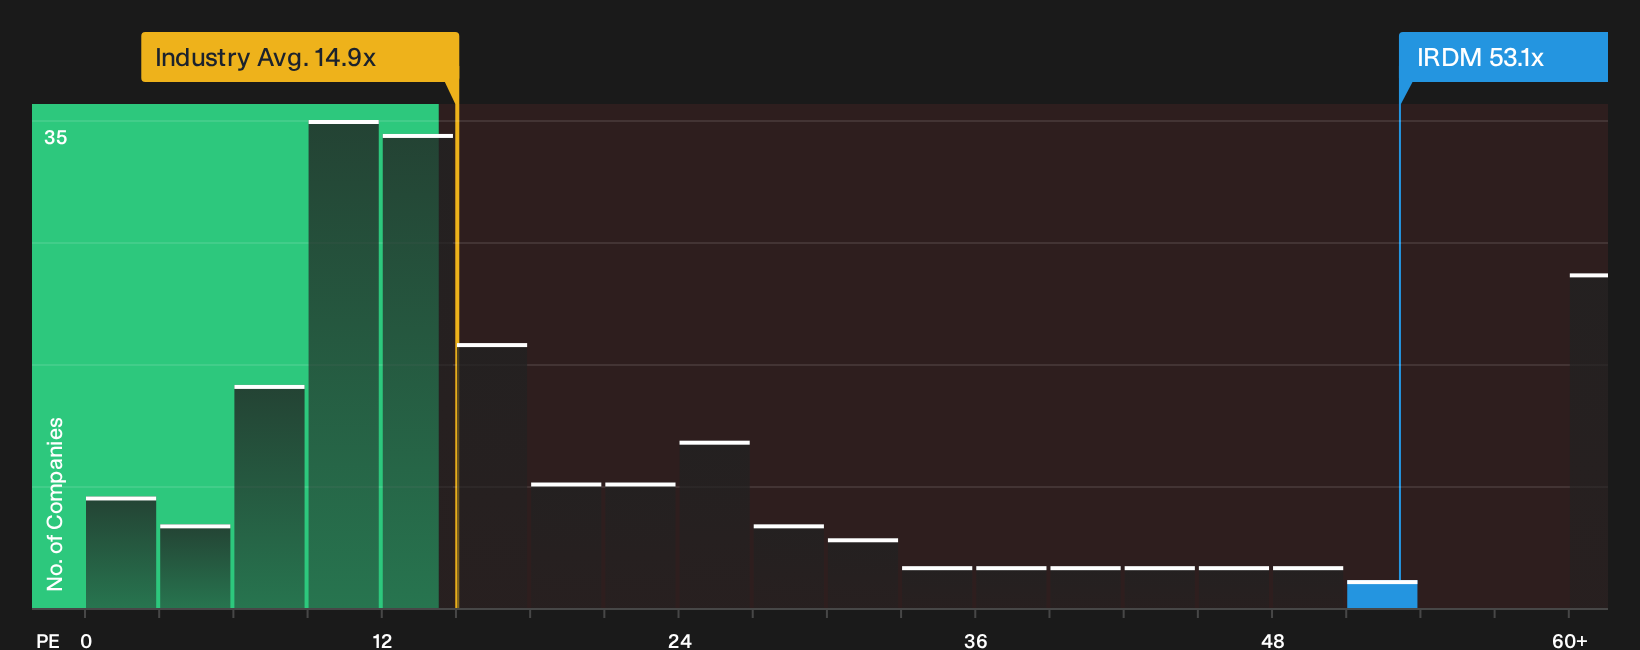
Iridium Communications screens as expensive on earnings based measures, with a P/E of 53.1x against a peer average of 37.1x and a Global Telecom mark of 15x, while the estimated fair ratio sits at 24x. That gap points to meaningful valuation risk if sentiment cools or growth disappoints.
For investors weighing what this richer P/E could mean in practice, it helps to unpack the assumptions baked into those multiples and how quickly they might compress if expectations reset, which is where our valuation breakdown on See what the numbers say about this price — find out in our valuation breakdown..
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Iridium Communications for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether the current mood on Iridium Communications lines up with your own reading of the risk and reward balance? Take a few minutes to dig into the data, review both sides of the argument, and ground your stance in the 2 key rewards and 2 important warning signs.
Looking for more Iridium Communications investment ideas?
If you are serious about finding your next opportunity, use the Simply Wall Street screener to quickly surface ideas that actually fit your investing checklist.
- Target potential mispricing by scanning companies that combine strong fundamentals with value style pricing using our 32 high quality undervalued stocks.
- Zero in on financial resilience by focusing on businesses with robust balance sheets through the list of solid balance sheet and fundamentals (25 results).
- Hunt for overlooked potential by tracking a 20 high quality undiscovered gems that the broader market may not be paying attention to yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com