
Is Home Depot (HD) Undervalued Following Early Holiday Sales And Tech Push?
Home Depot (HD) is kicking off early Black Friday promotions and leaning on tech and supply-chain upgrades to keep shoppers engaged as the housing market stays frozen and affordability pressures linger.
Recent early holiday headlines around Home Depot sit against a tougher tape, with the stock logging a 1-day share price return of 1.14% and a 7-day gain of 2.52%. However, the 90-day share price return is down 13.92% and the 1-year total shareholder return has declined 22.05%, pointing to fading momentum even as management leans on tech upgrades, supply-chain tweaks and Pro-focused services to reset the risk and growth story.
Spot opportunities around Home Depot's setup by scanning a hand-picked 32 high quality undervalued stocks that combines solid cash generation with balance sheets built to handle frozen housing conditions.Home Depot shares have slipped over the past quarter even as management pushes tech, Pro services and early holiday deals. Is this pullback enough to justify stepping in now, or is patience on price still worth more?
Most Popular Narrative: 24% Undervalued
Home Depot's most followed storyline pegs fair value at $385 against a last close of $293.92, framing a sizable valuation gap that hinges on how well the Pro ecosystem shift plays out.
Home Depot is evolving from a traditional big-box home improvement retailer into a comprehensive supplier ecosystem for professional contractors (“Pros”), while continuing to serve DIY customers through stores, digital tools, and faster fulfillment. Recent acquisitions (including SRS Distribution and GMS) expand its reach into specialty distribution for roofing, drywall, HVAC, and other complex project categories and enlarge the addressable market toward roughly $1.2 trillion, with the Pro segment opportunity near $700 billion.
See why 8 investors see Home Depot as 24% undervalued.
Result: Fair Value of $385 (UNDERVALUED)
Still, the Home Depot narrative can break if housing activity stays weak for longer, or if recent acquisitions drag on margins and integration costs.
Find out about the key risks to this Home Depot narrative.
Another View: Home Depot Through The Earnings Lens
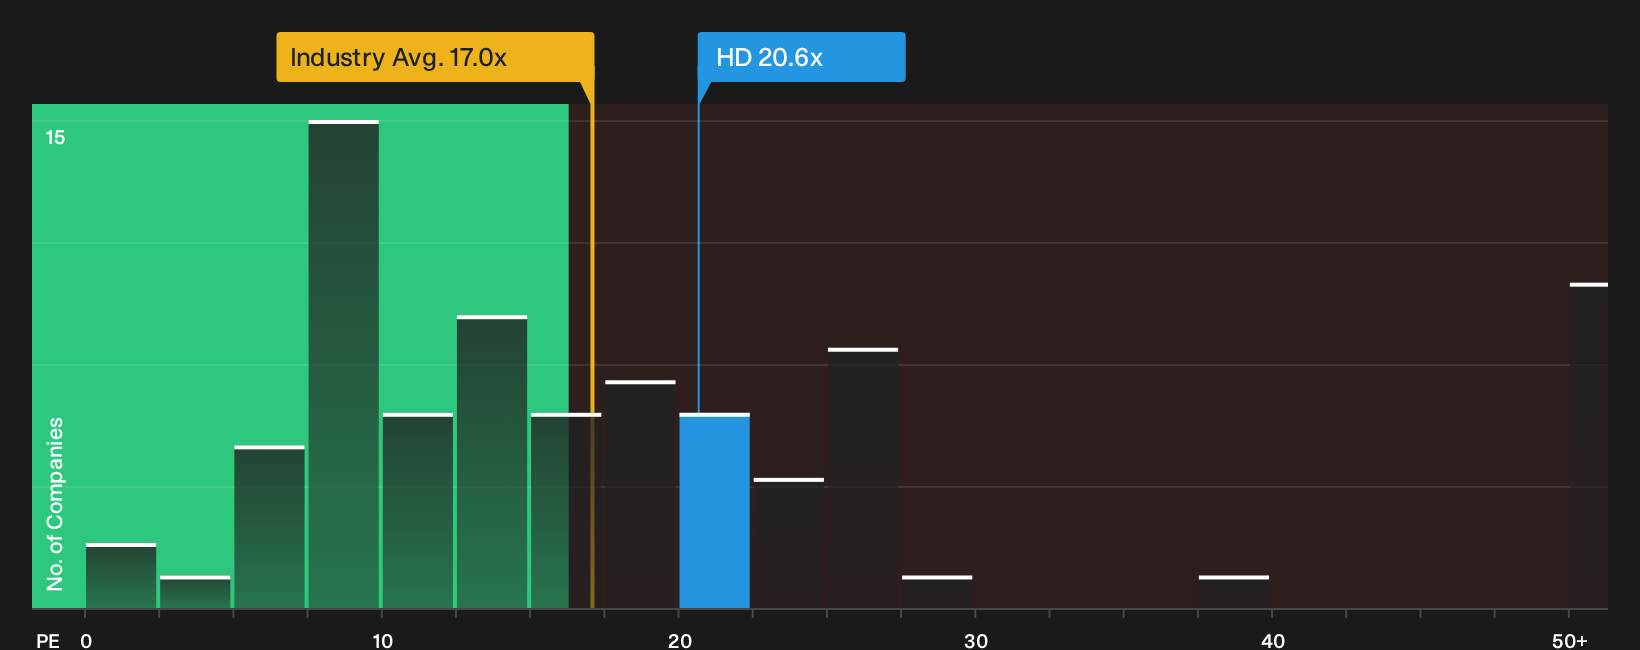
The user narrative frames Home Depot as 24% undervalued at a fair value of $385, yet the market is already paying a P/E of 20.6x. That sits above the US Specialty Retail average of 17x, while sitting slightly below a peer average of 21.8x and close to a fair ratio of 21.5x.
In plain terms, the stock trades at a richer earnings tag than the wider industry but roughly in line with what similar peers and the fair ratio suggest. That points to less obvious bargain territory and more of a pay up for quality question.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Home Depot's setup so far. If you want to move fast and build your own view on the balance of risks and upsides, start by weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Home Depot?
Do not stop with Home Depot. Broaden your watchlist now so you are not relying on a single storyline when fresh opportunities line up.
- Target dependable compounding by scanning for strong payers using the 8 dividend fortresses.
- Hunt for quality at a discount through the 20 high quality undiscovered gems before the wider market pays attention.
- Prioritise peace of mind by focusing on resilient balance sheets with the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com