
This Analyst Just Met Micron’s Investor Relations Team. He Thinks It’s a $3,000 Stock.
On Oct. 7, D.A. Davidson analyst Gil Luria raised his Micron Technology (MU) price target from $2,100 to $3,000 while keeping a Buy rating. What’s interesting is that the old target was already the highest on Wall Street, and that’s now been raised by nearly 43%. The new target implies the stock could nearly triple from its current price. Luria made the call after meeting with Micron’s investor relations team. He came away believing investors are still early in understanding what Micron is worth. In his view, AI has turned memory into a critical part of AI systems, and demand should stay ahead of supply through 2027 and 2028.
The key detail is where the upside comes from. Luria’s target values Micron at 19 times his fiscal 2027 EPS estimate of roughly $158. That estimate is actually below the Wall Street consensus. So Luria isn’t counting on bigger earnings than everyone else. He’s betting investors will pay a much higher multiple for them. BofA, for comparison, expects slightly higher earnings than Luria but has a $1,550 target. In other words, Micron's path to $3,000 depends as much on investor confidence as it does on earnings.
The case for a higher multiple rests on how Micron now sells its chips. Its strategic customer agreements are multi-year take-or-pay deals, so customers have to pay for the capacity they’ve committed to. Luria pointed out that Micron’s key partners include Amazon (AMZN), Microsoft (MSFT), Google (GOOG),(GOOGL), Nvidia (NVDA), and Apple (AAPL), companies that rarely walk away from contracts. As I covered earlier, Micron’s mix of DRAM, NAND, and high-bandwidth memory also leaves it less exposed than pure NAND players. The latest quarter showed the momentum, with revenue up 379% year-over-year to a record $54.2 billion. Micron expects about $61.5 billion next quarter.
Why Micron Still Trades Like a Cyclical Stock
Micron’s valuation explains the gap between Luria and the rest of Wall Street. The forward non-GAAP P/E of 5.94x sits about 92% below its five-year average of 74.26x. The average is inflated by years of weak earnings, but the low multiple still stands out. The forward Price-to-sales ratio of 4.29x is roughly in line with its five-year average of 4.17x. To me, that suggests the market expects today’s record margins to shrink. Analysts expect EPS to jump 133% in fiscal 2027 and 17% in 2028. After that, they see earnings slipping marginally in 2029 and falling about 32% in 2030. The balance sheet is clean. Micron holds $43.43 billion in cash against just $5.18 billion in debt. For Micron to reach $3,000, though, investors would need to believe that the 2030 decline never comes.
About Micron Stock
Micron Technology is a semiconductor company that designs and manufactures memory and storage products for consumer, enterprise, and industrial applications. Its product portfolio includes DRAM, NAND flash memory, high-bandwidth memory, and solid-state drives. Micron is the only major American-owned manufacturer of computer memory chips. Founded in 1978, the company is headquartered in Boise, Idaho, and is led by CEO Sanjay Mehrotra.
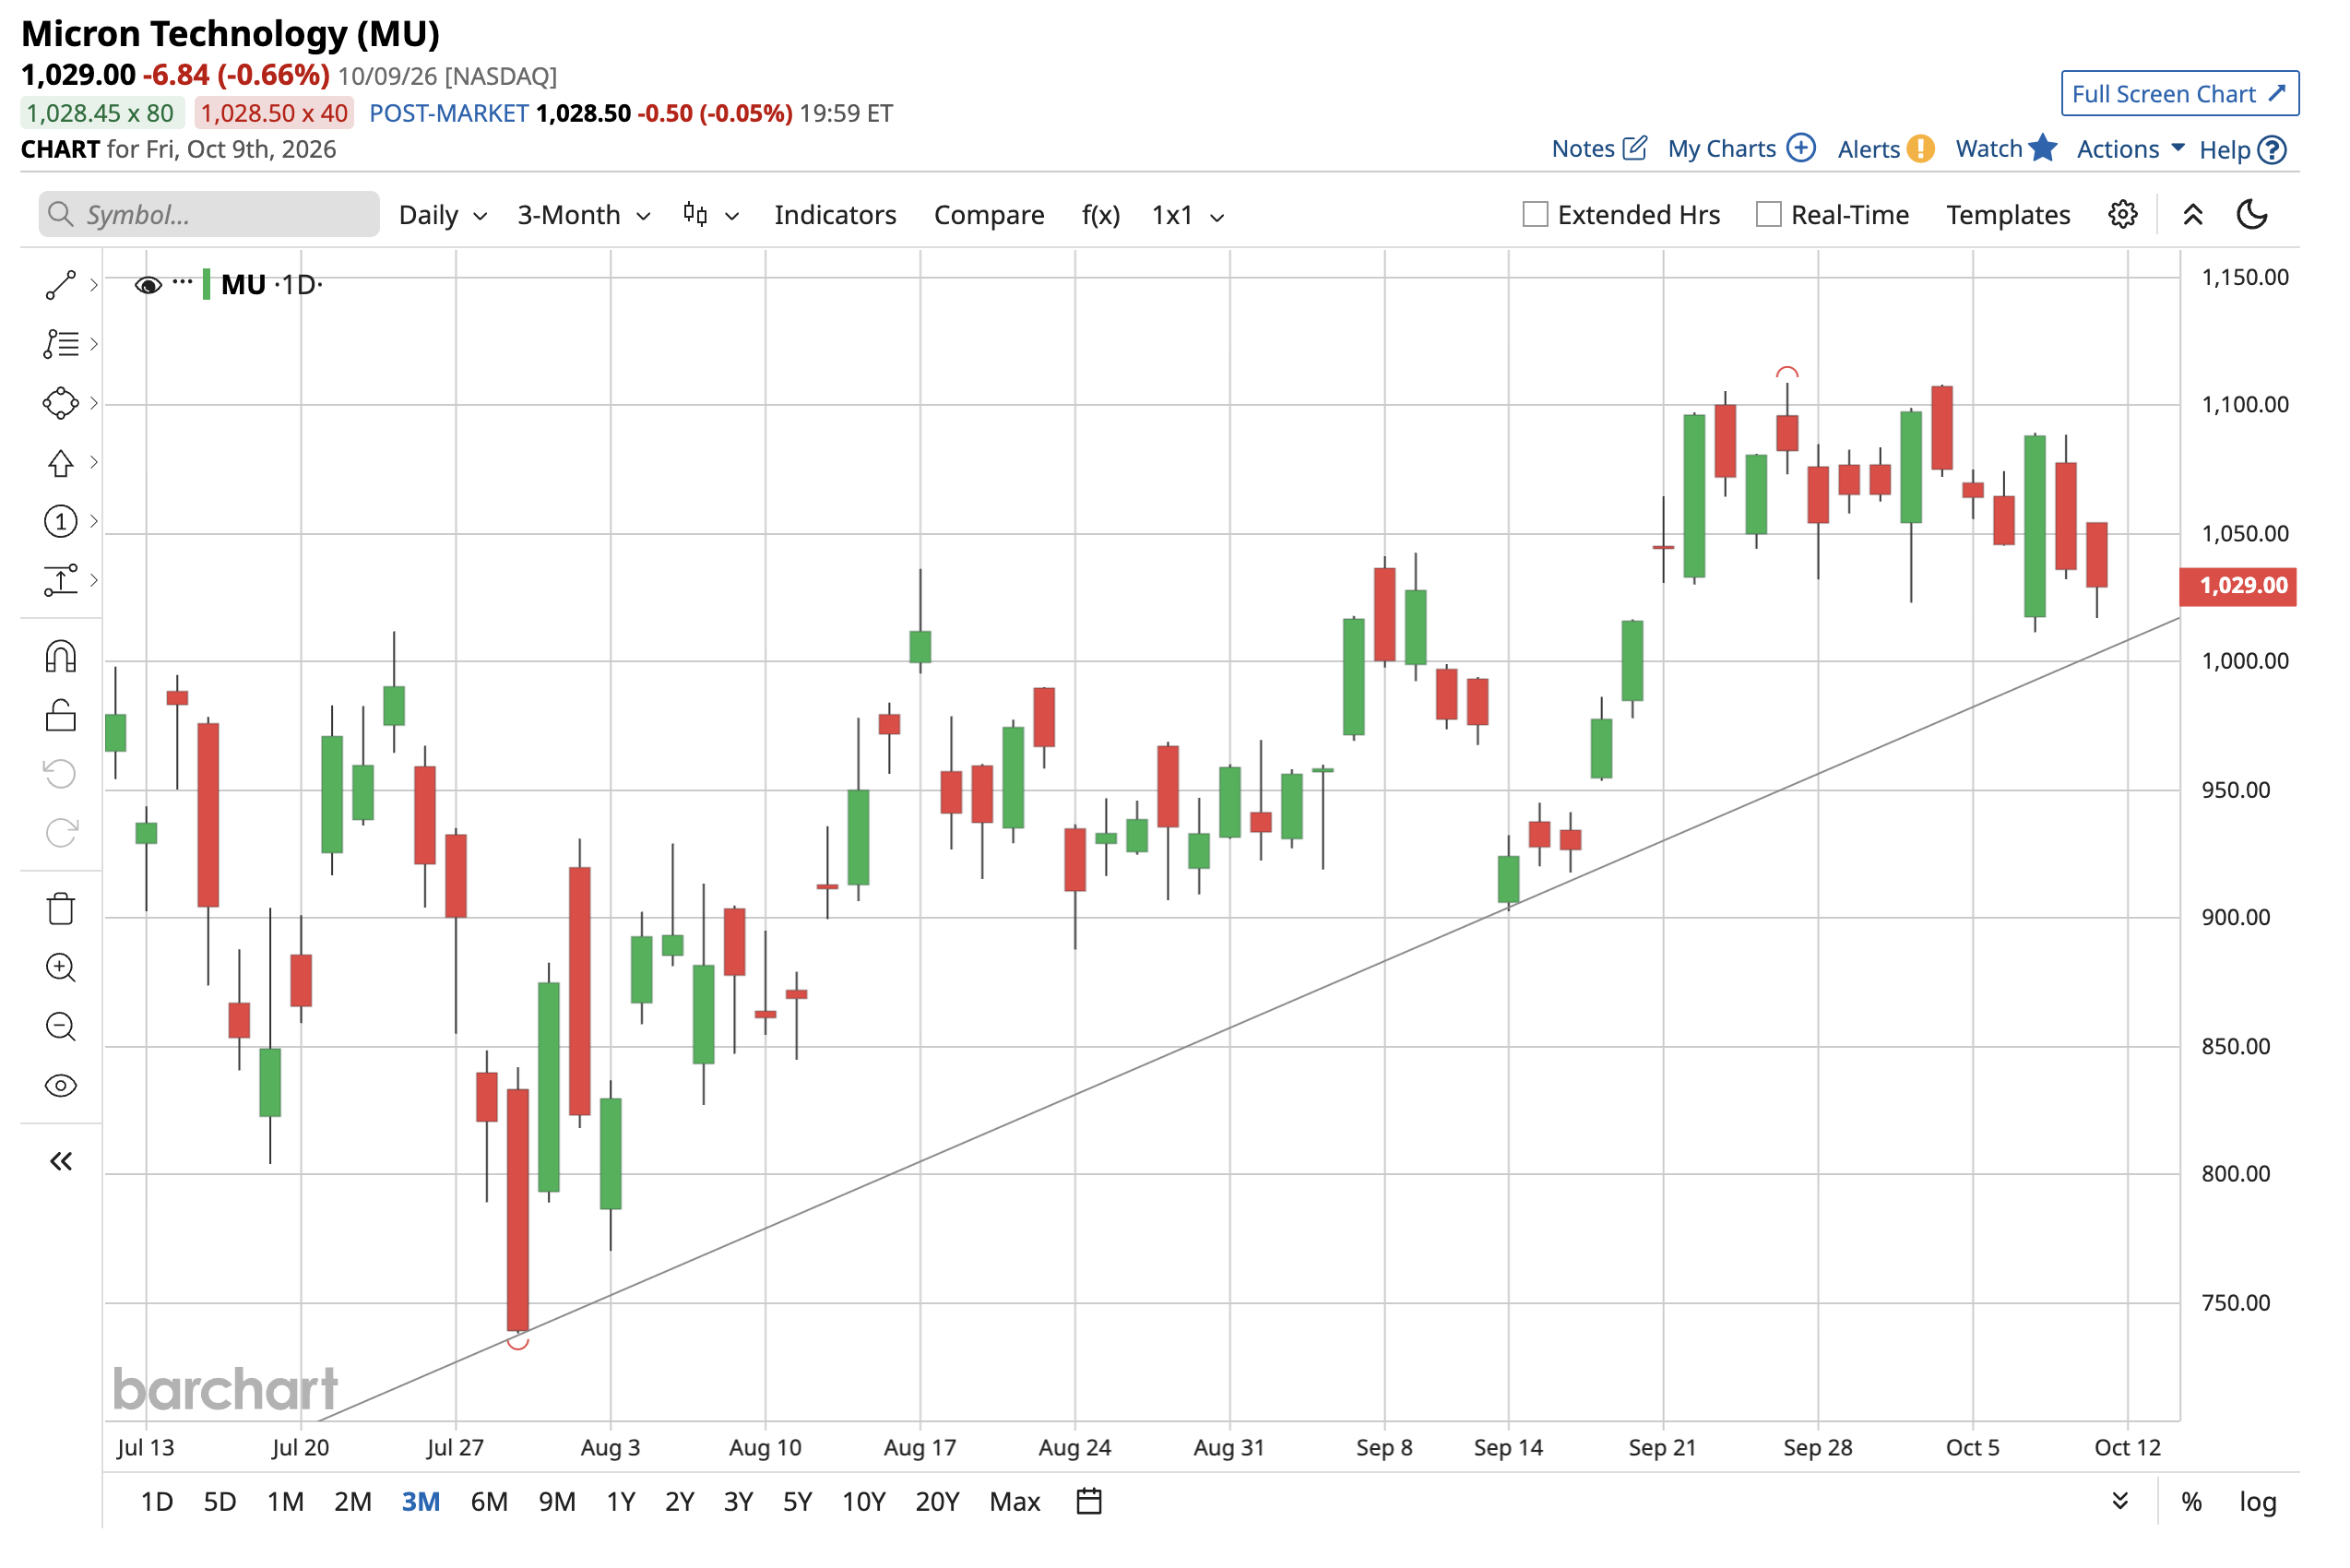
Over the past year, the stock has significantly outperformed the broader semiconductor sector. It surged around 536%, well above the iShares Semiconductor ETF (SOXX), which gained about 109% during the same period. The trend has continued this year as well, with Micron shares up 237% year-to-date. The iShares Semiconductor ETF gained 81% over the same period. Growing demand for high-bandwidth memory (HBM) used in AI servers played a major role in the stock’s strong performance.
What Do Analysts Expect for MU Stock?
Wall Street remains bullish on Micron. Morgan Stanley reiterated a Buy rating and set a price target of $1,200. The firm believes the near-term conditions are still good and the company will benefit from strong demand. Similarly, Mark Li from Bernstein maintained a Buy rating with a price target of $1,300.
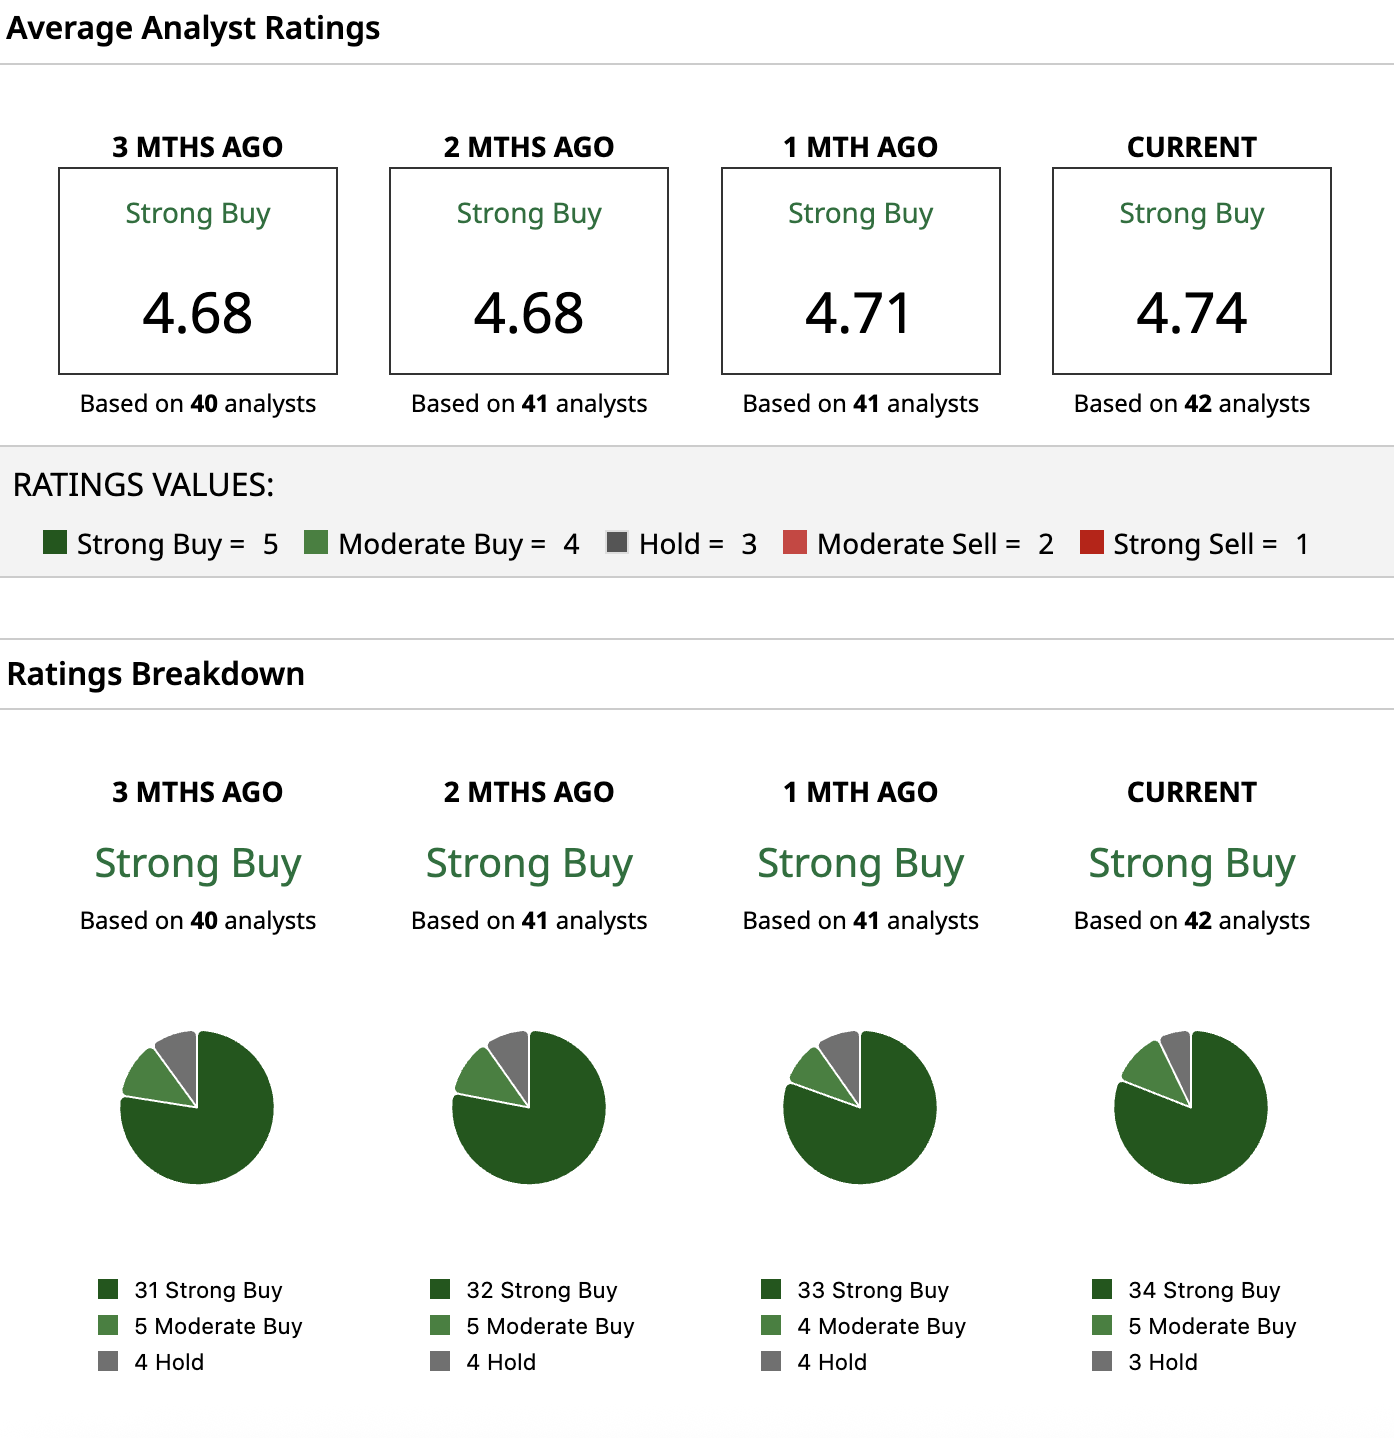
Based on 40 Wall Street analysts covering the stock, MU holds a consensus “Strong Buy” rating. Out of those, 32 have a “Strong Buy” rating, four have a “Moderate Buy” rating, and four have a “Hold” rating. The mean price target of $1,479 reflects 39% upside from current levels. The high price target of $2,000 is quite impressive, implying 88% upside from the current share price. With no “Sell” rating and an impressive high price target, it is clear Wall Street remains confident in the company's long-term growth prospects.
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.