
Is Enterprise Products Partners (EPD) Below Fair Value After 110% Gains?
Enterprise Products Partners has delivered a strong multi‑year run for unitholders, so the key issue now is whether the current price is still in line with what its earnings can reasonably support. Recent unit price weakness sits against a longer period of solid gains, which makes the earnings valuation lens especially important for anyone considering the stock today.
- Over the past 5 years, Enterprise Products Partners has returned 109.9%, which puts real pressure on the question of whether its present earnings base and outlook are enough to back that move.
- Recent coverage highlighting a fee-based pipeline model, long-term contracts and a raised cash distribution suggests earnings and distributable cash flow can remain central to how investors assess what counts as a fair multiple for the units.
- There is a second opinion on Enterprise Products Partners worth weighing. See what analysts think Enterprise Products Partners's shares could be worth.
The issue now is whether Enterprise Products Partners' current unit price is justified by its earnings when judged against the Fair Ratio benchmark.
If you want to test the same earnings question that hangs over Enterprise Products Partners across a wider set of dividend-heavy infrastructure plays, take a look at 8 dividend fortresses.
Is Enterprise Products Partners a Bargain on Earnings?
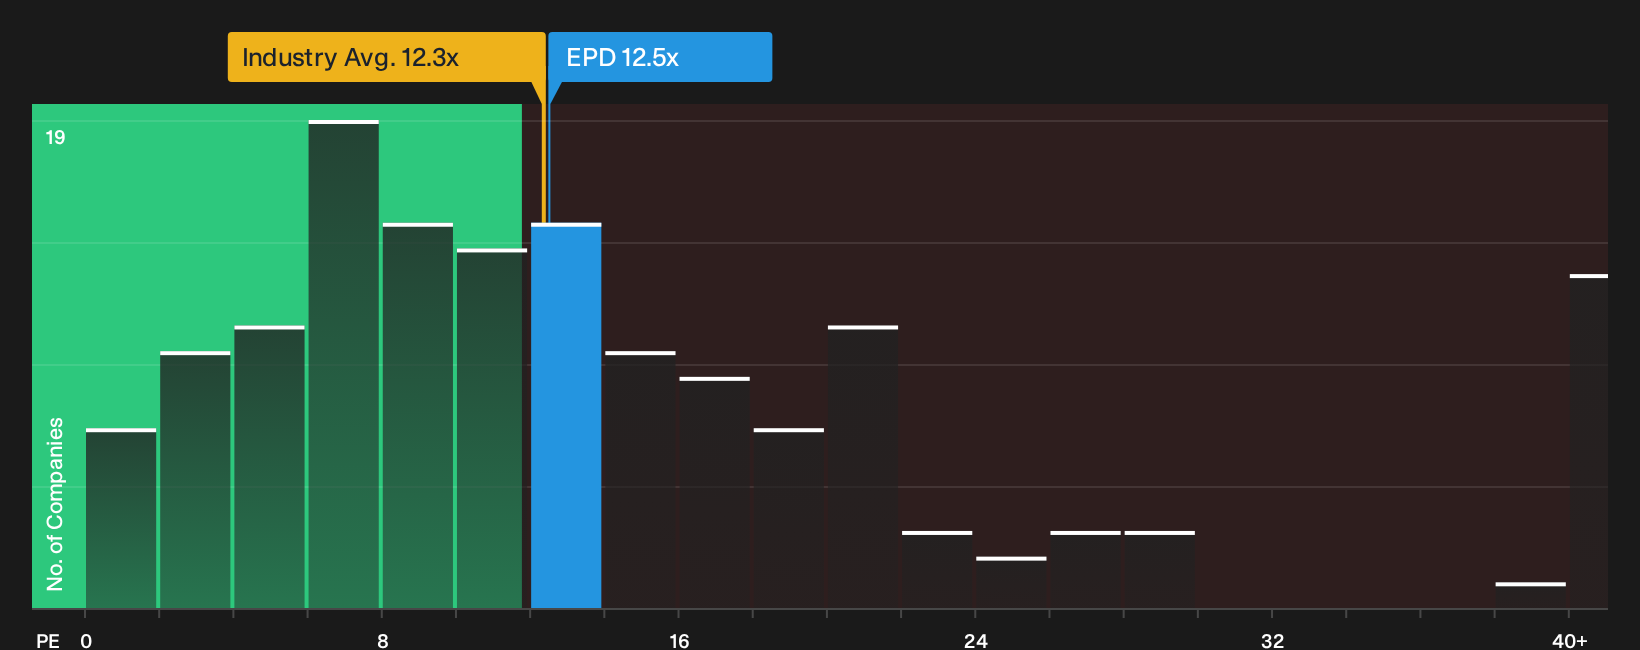
The P/E ratio works well for Enterprise Products Partners because earnings are a key lens for a fee-based pipeline partnership. On this yardstick, the units trade at about 12.5x earnings, which is very close to the Oil and Gas sector average of roughly 12.3x.
Against similar infrastructure peers, where the average P/E is around 23.3x, Enterprise Products Partners is priced at a sizeable discount. The Fair Ratio, which reflects what you might expect for a business with this mix of cash flows, capital intensity and risk, also sits higher than the current multiple, so the units screen as undervalued on earnings. Because the partnership has continued to grow its distribution stream according to recent coverage, the gap between the market P/E and those benchmarks suggests investors are still pricing the stock cautiously. Explore the numbers behind Enterprise Products Partners's P/E valuation.
The Enterprise Products Partners Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Enterprise Products Partners valuation puzzle leaves off. They spell out what kind of growth, profitability and earnings path would need to occur for the units to be worth materially more or less than today’s price on the Community page. Each scenario anchors a fair value to a clear story about Enterprise Products Partners' potential catalysts and risks so you can track which version of events appears to be unfolding over time.
One of the top community narratives on Enterprise Products Partners: 13% undervalued
"The main thing that has to go right is that higher growth capex in the Permian and related NGL infrastructure converts into sustained, high-utilization volumes..."
Discover why this Narrative puts Enterprise Products Partners at 13% undervalued.
Before you log off, one more Enterprise Products Partners check belongs next to the price tag
Unit pricing is only part of the story, because the people directing Enterprise Products Partners and the way their incentives are set up can tilt risk and reward in very different directions. See who runs Enterprise Products Partners and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com