
Is CACI International (CACI) Undervalued As Congressional Buying Draws Fresh Attention?
Representative Lisa McClain’s recent purchase of CACI International (CACI) stock, disclosed on October 12, 2026, has drawn fresh attention to the defense IT contractor and its role in markets watched for congressional trading activity.
CACI International shares trade at US$609.66, with the price down 0.8% over the last session but up 29.2% over three months, while the 1-year total shareholder return of 18.5% and 5-year total shareholder return of 116.7% point to momentum that has been strong rather than fading.
Scan how CACI International compares with other defense and government IT contractors by reviewing the hand picked list of solid balance sheet and fundamentals (25 results).
Bulls see CACI International’s recent run and congressional interest as confirmation of a quality defense IT compounder. Bears see a hot stock at risk of overpayment. Which story does the current valuation support?
Most Popular Narrative: 17% Undervalued
Against CACI International’s last close at $609.66, the most followed narrative pegs fair value at about $735.21. This frames the stock as trading at a meaningful discount while analysts model steady, not explosive, growth.
Accelerated adoption of software defined platforms, cyber solutions, and enterprise software modernization is now visible in CACI International's portfolio mix. Roughly 60 to 70% of its nearly US$10b revenue is characterized as defense tech like work, and EBITDA margins have been reported in the low to mid teens. This supports the case for structurally higher future margins and cash flow.
Expanding positions in electronic warfare, counter UAS, and space, highlighted by programs such as Spectral entering low rate initial production with deployments planned for the second half of FY27, Domestic Shield moving into full rate production, and NITE STAR and Enterprise Space Terminal progressing, point to additional contracted revenue and potential uplift to EBITDA and earnings as these awards convert.
See why 27 investors see CACI International as 17% undervalued.
Result: Fair Value of $735.21 (UNDERVALUED)
Still, the bullish CACI International story leans heavily on executing a US$32b backlog and on turning higher capital spending into stronger free cash flow and returns.
Find out about the key risks to this CACI International narrative.
Another View: What CACI International’s P/E Ratio Signals
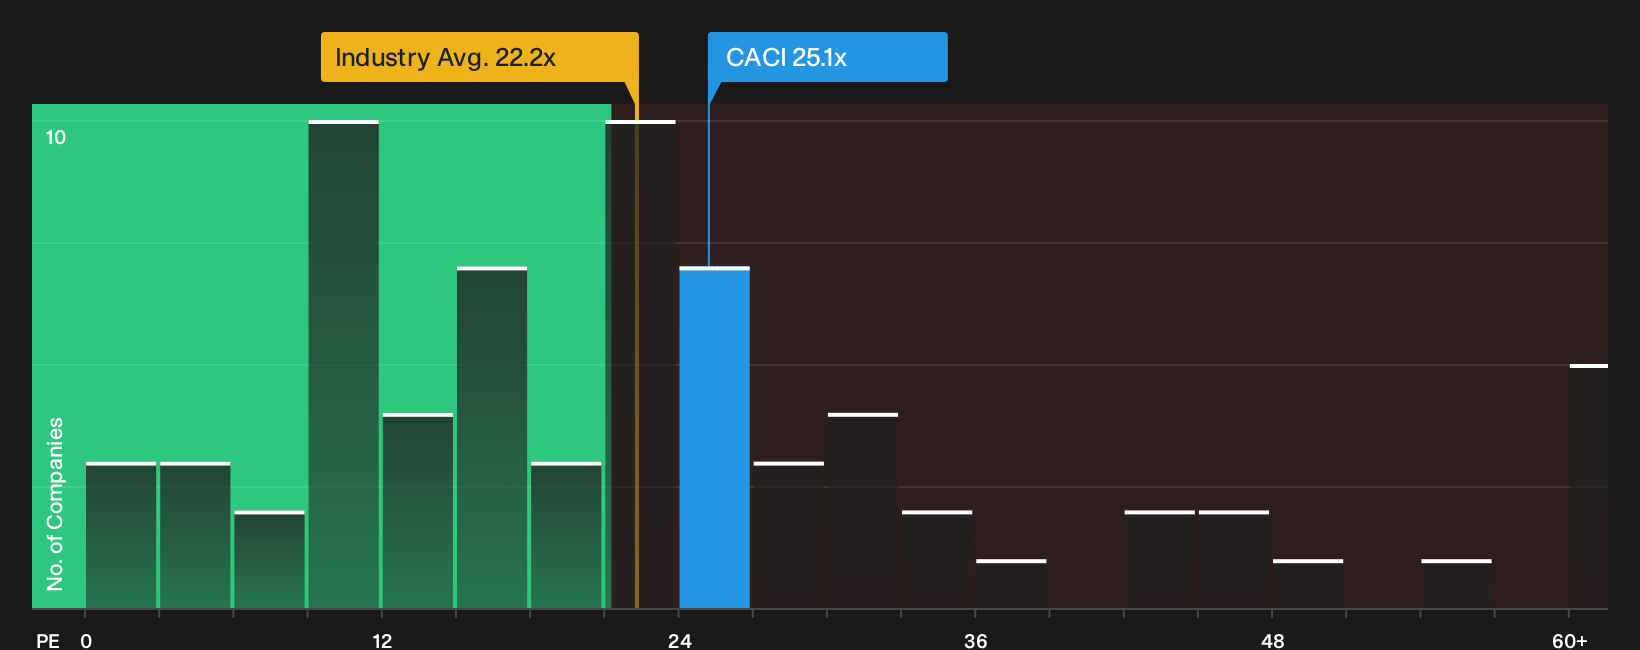
There is a catch. CACI International trades on a P/E of 25.1x while the fair ratio is 21x, the US Professional Services average is 22.3x, and peers sit near 25.8x. That richer multiple could limit upside if the market drifts closer to the fair ratio.
To pressure test whether that richer multiple is justified, take a closer look at how the numbers stack up in our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Then put that premium side by side with sector pricing and earnings outcomes using the latest relative valuation snapshot for CACI International, shown in
Next Steps
Mixed on CACI International after all that. If you want to move from headline takes to hard evidence, weigh up its 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond CACI International?
Do not stop at one ticker. Broadening your watchlist with fresh ideas can sharpen your judgement, highlight better trade offs, and stop you chasing crowded stories.
- Target resilient returns first by scanning companies that show strong balance sheets and reliable fundamentals through the list of solid balance sheet and fundamentals (25 results).
- Hunt for value opportunities by reviewing the 32 high quality undervalued stocks that combine quality fundamentals with prices that still look reasonable.
- Prioritise cash in hand by checking out income focused ideas across the 8 dividend fortresses before yields move away from you.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com