
What Is Drawing Attention To Coca Cola Consolidated (COKE) Today?
Coca-Cola Consolidated (COKE) drew fresh attention after its board declared a fourth-quarter 2026 cash dividend of $0.25 per share, payable on November 6 to holders of record on October 23.
Despite the dividend announcement, Coca-Cola Consolidated’s share price has eased 1.6% over the past day while still holding a 9.7% 90 day share price return and a 29.6% year to date share price return, with a 1 year total shareholder return of 54.2%.
Spot opportunities beyond Coca-Cola Consolidated by scanning our hand picked 20 high quality undiscovered gems with similar momentum and solid fundamentals.Coca-Cola Consolidated has cooled slightly after a strong run, yet the valuation gap between its recent share price and several fair value estimates is still wide enough to matter. Where does a reasonable price actually land now?
Preferred P/E of 23.5x: Is it justified?
Coca-Cola Consolidated trades on a P/E of 23.5x, which puts a clear valuation hurdle in front of anyone looking at the recent $194.16 share price and asking whether the strong 1 year return aligns with underlying earnings power.
The P/E ratio compares what investors pay for each dollar of profit to what those earnings currently are. For a beverage bottler with a long operating history and established brands, that simple yardstick often captures how much optimism is being priced into future cash generation.
On one side, COKE screens as expensive relative to the broader Global Beverage industry, where the average sits at 16.6x. That is a meaningful premium and suggests the market is willing to pay more for each dollar of Coca-Cola Consolidated earnings than for many global peers. On the other side, the same 23.5x P/E looks cheap against a narrower peer set on 55.3x, and the stock is assessed as trading at 23.3% below an internal fair value estimate and below an SWS DCF model output of $253.17 per share. That mix of signals points to investors weighing high quality earnings and a strong 5 year earnings growth record against more recent pressure on profit margins and earnings, while also keeping an eye on the high debt load and negative shareholder equity.
Compared with the Global Beverage industry average P/E of 16.6x, Coca-Cola Consolidated carries a strong valuation premium that implies higher expectations than the sector as a whole. Yet compared with its closer peer group on 55.3x, the same multiple is framed as good value, which underlines how concentrated investor enthusiasm can be in this corner of the market and how differently similar tickers can be priced when momentum, balance sheet risk and earnings quality line up in specific ways.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 23.5x (ABOUT RIGHT)
Still, Coca-Cola Consolidated carries meaningful debt and negative shareholder equity, so any earnings setback or funding squeeze could quickly challenge the current valuation story.
Find out about the key risks to this Coca-Cola Consolidated narrative.
Another View: SWS DCF signals undervaluation
The P/E asks whether Coca-Cola Consolidated looks expensive against earnings today. The SWS DCF model instead looks at estimated future cash flows and discounts them back to today’s $194.16 share price to see what those streams might be worth.
On that score, the result is clear. The stock is assessed as trading at $194.16 against an SWS DCF value of $253.17 per share, which implies a 23.3% discount to that cash flow based fair value estimate. For investors, the practical question is simple. If the earnings wobble and balance sheet risks are already in the price, is the cash flow gap an opening or a warning?
Look into how the SWS DCF model arrives at its fair value.
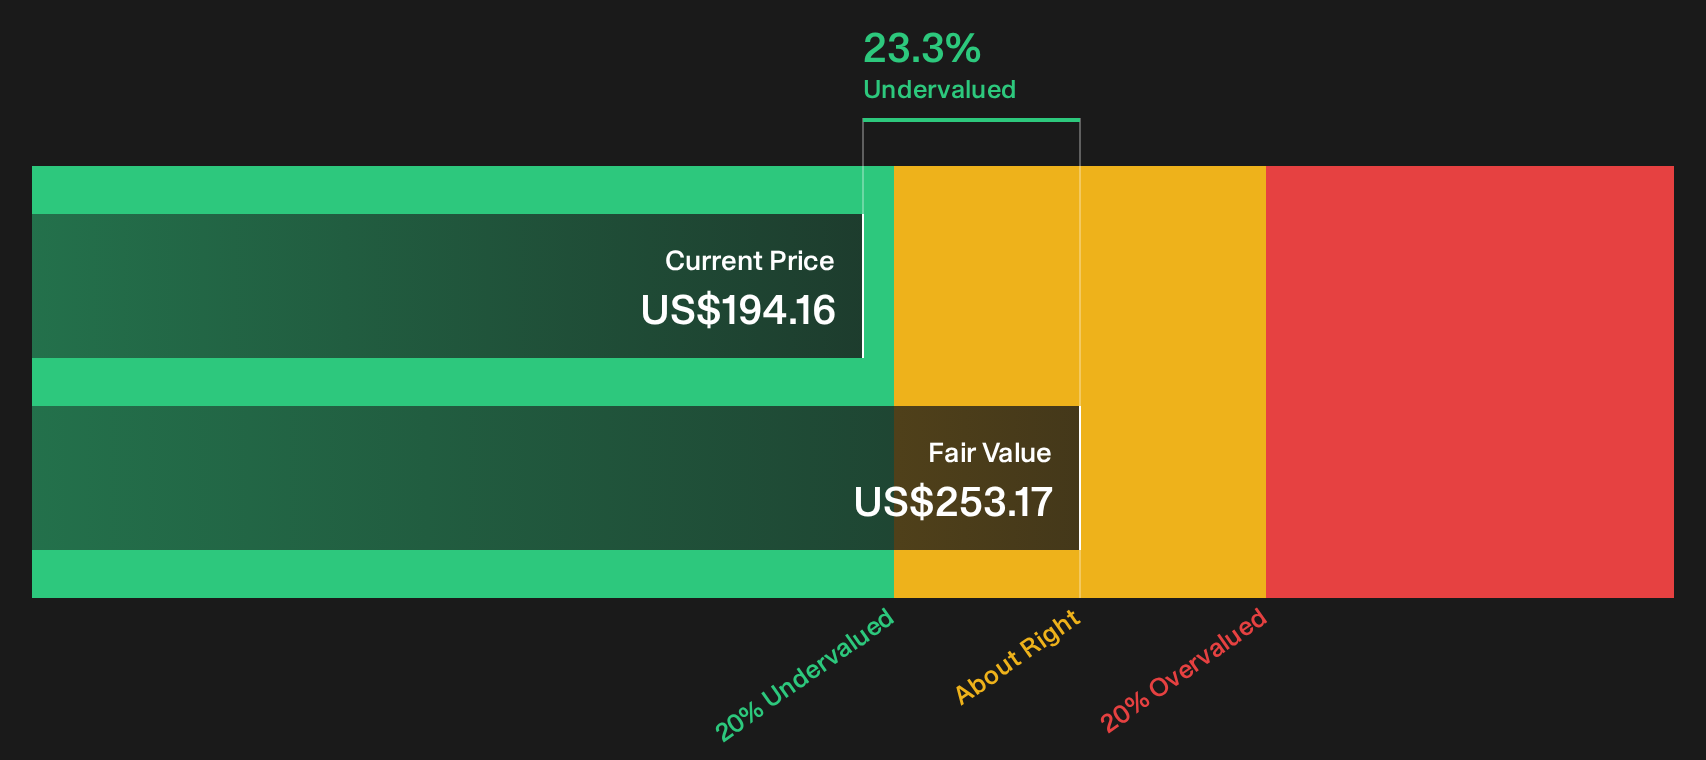
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Coca-Cola Consolidated for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Cautious optimism runs through the Coca-Cola Consolidated story, so now is the moment to check the numbers yourself and pressure test the thesis. Weigh both sides of the equation by lining up the 1 key reward and 2 important warning signs.
Looking for more Coca-Cola Consolidated investment ideas?
Do not stop with Coca-Cola Consolidated. Broaden your watchlist now with fresh ideas surfaced by Simply Wall St screeners that spotlight quality, value and resilience across the market.
- Target stronger balance sheets by reviewing the list of solid balance sheet and fundamentals (25 results) to find financially robust businesses built to handle tougher conditions.
- Zero in on potential mispricing by working through the 32 high quality undervalued stocks that combine quality metrics with attractive valuations.
- Prioritise capital protection by scanning the 32 resilient stocks with low risk scores that focus on resilient businesses with lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com