
Albertsons (ACI) Stock May Trade Above Fair Value Following Turnaround Review
Albertsons Companies has seen its share price fall sharply over the past few years, and the latest boardroom changes now put a fresh spotlight on whether the current US$12.72 price is in line with what its earnings can support. With management pushing a turnaround plan and stepping up cost cuts, a key consideration is how much of that effort is already reflected in the valuation.
- Over the past 3 years, Albertsons has delivered a total return that declined 38.3%, which puts the focus squarely on whether the current earnings stream justifies staying invested after such a drawn out hit to capital.
- The ACI Edge overhaul and the push for leaner operations may support earnings stability if cost savings outweigh pressure on comparable store sales, which directly matters for how much profit the business can generate on each dollar of revenue.
- There is a second opinion on Albertsons Companies worth weighing. See what analysts think Albertsons Companies's shares could be worth.
A central question now is whether Albertsons' current earnings profile is strong enough to support the share price after several years of weak returns and ongoing restructuring efforts.
If you are questioning whether Albertsons Companies at US$12.72 is really supported by its earnings, it can help to compare that same dilemma across 32 high quality undervalued stocks.
Is Albertsons Companies Getting Expensive on Earnings?
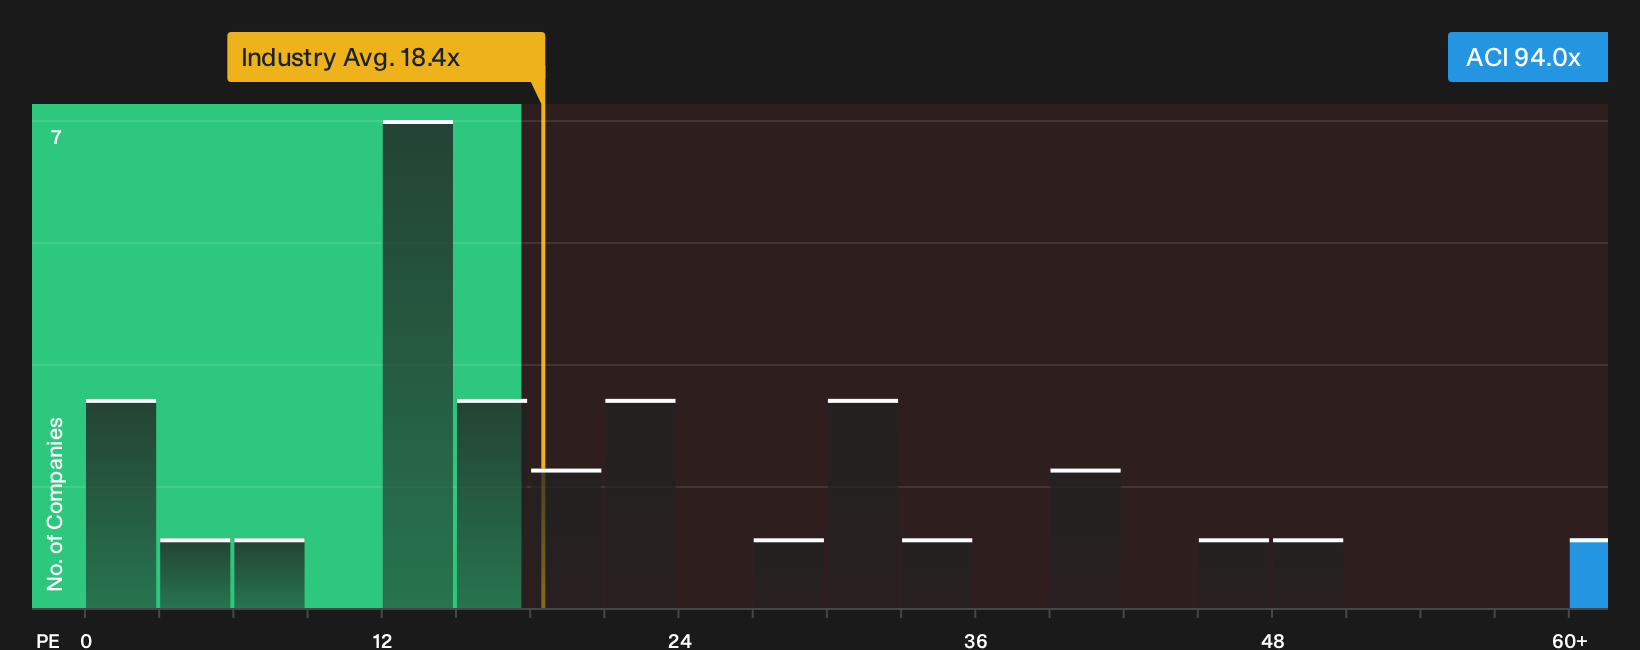
The P/E ratio suits Albertsons Companies because recent earnings are the main anchor investors have while the turnaround under Meg Whitman plays out. At roughly 94.0x earnings, the stock trades at a very large premium to the broader Consumer Retailing sector, where the typical P/E sits closer to 18.4x, and it also screens well above a peer average of about 17.5x. That gap means each dollar of Albertsons’ profit is currently priced far more richly than profits at many comparable grocers.
The fair P/E level implied by the valuation framework is lower than where Albertsons Companies trades today, so the current multiple screens as overvalued on this earnings lens. Because the ACI Edge cost program and broader restructuring are still in progress, the rich P/E already asks a lot of the future profit story. Despite the ongoing review and cost cutting aimed at lifting performance, investors are paying a high headline multiple for the recent earnings base. Explore the numbers behind Albertsons Companies's P/E valuation.
The Albertsons Companies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Albertsons Companies valuation puzzle leaves off by spelling out the kind of growth, margin profile, and earnings path that would need to hold for the share price to end up meaningfully higher or lower than it is today, and each one treats fair value as a thesis about how the business might evolve over time that you can track as new information comes through. They sit on Simply Wall St's Community page as structured prompts for your own judgment, not conclusions.
Albertsons Companies now splits opinion between investors who see a cost and digital reset setting up value, and others who think execution risk still dominates the story.
Bull case: 10% undervalued
"Modernization through technology investments such as automation, AI-driven inventory/pricing, and centralized buying are streamlining operations, reducing labor and supply chain costs..."
Discover why this Narrative puts Albertsons Companies at 10% undervalued.
Bear case: 27% overvalued
"The ACI Edge restructuring and centralization are intended to deliver about US$200m of run rate savings by fiscal 2027, but the concurrent leadership uncertainty increases execution risk..."
Explore why this Narrative puts Albertsons Companies at 27% overvalued.
One more Albertsons Companies check that sits beyond the P/E
Price and earnings only tell you so much about Albertsons Companies. The real steering comes from the people in charge and how their pay is structured, which is a separate piece worth checking. See who runs Albertsons Companies and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com