
Mihama Reactor Restart Could Be A Game Changer For Kansai Electric Power Company (TSE:9503)
- Kansai Electric Power Company reported that Mihama Nuclear Power Station Unit 3 was manually shut down in September 2026 after a small leak was detected. The issue was then repaired by replacing corroded piping and updating maintenance procedures ahead of a planned restart and return to full operation in November 2026.
- The group is also working with SkyDrive and Osaka Metro on a Super City feasibility study to repurpose Osaka rooftop emergency landing sites into eVTOL vertiports. This project links Kansai Electric Power Company directly to future urban mobility power demand and charging infrastructure planning.
- The next step is to consider how Kansai Electric Power Company's investment narrative could be influenced by the Mihama Unit 3 restart plan.
Scan how Kansai Electric Power Company fits into the broader grid upgrade story by comparing it with our hand picked 43 power grid technology and infrastructure stocks focused on future electricity infrastructure demand.
Kansai Electric Power Company Investment Narrative Recap
To own Kansai Electric Power Company you need to be comfortable with a utility leaning on heavy capital spending and nuclear availability, while guiding to a three year plateau in profitability. The Mihama Unit 3 leak and manual shutdown highlight that safe, consistent nuclear output is still the key short term catalyst as management works to keep recurring profit near guidance.
Because the issue was traced to older installation work and corrective measures are now in place, the direct financial impact around the restart schedule looks contained. The bigger swing factor remains whether nuclear capacity factors, fuel costs and regulated tariffs pressure margins more than planned, alongside debt and free cash flow coverage.
The most relevant fresh datapoint on these topics is the planned restart and commissioning timeline for Mihama Unit 3 and the linked maintenance update. That schedule runs through to a planned return to full operation on 4 November 2026. Investors are watching execution risk, inspection findings and any further timetable changes very closely.
In the background, the analyst and investor day framing still matters. Management is committing to ¥15t of investment out to 2040 and ¥2.5t over the next three years, with targeted ROIC above WACC and an 8% ROE ambition. Delivery on nuclear reliability, including Mihama, is directly tied to whether those capital plans support returns without stretching the balance sheet.
Kansai Electric Power Company's current analyst narrative points to forecast revenue of ¥4,547.8b and earnings of ¥345.8b by 2029, built on an assumed 3.1% yearly revenue growth rate and an earnings decline of ¥72.1b from earnings today of ¥417.9b.
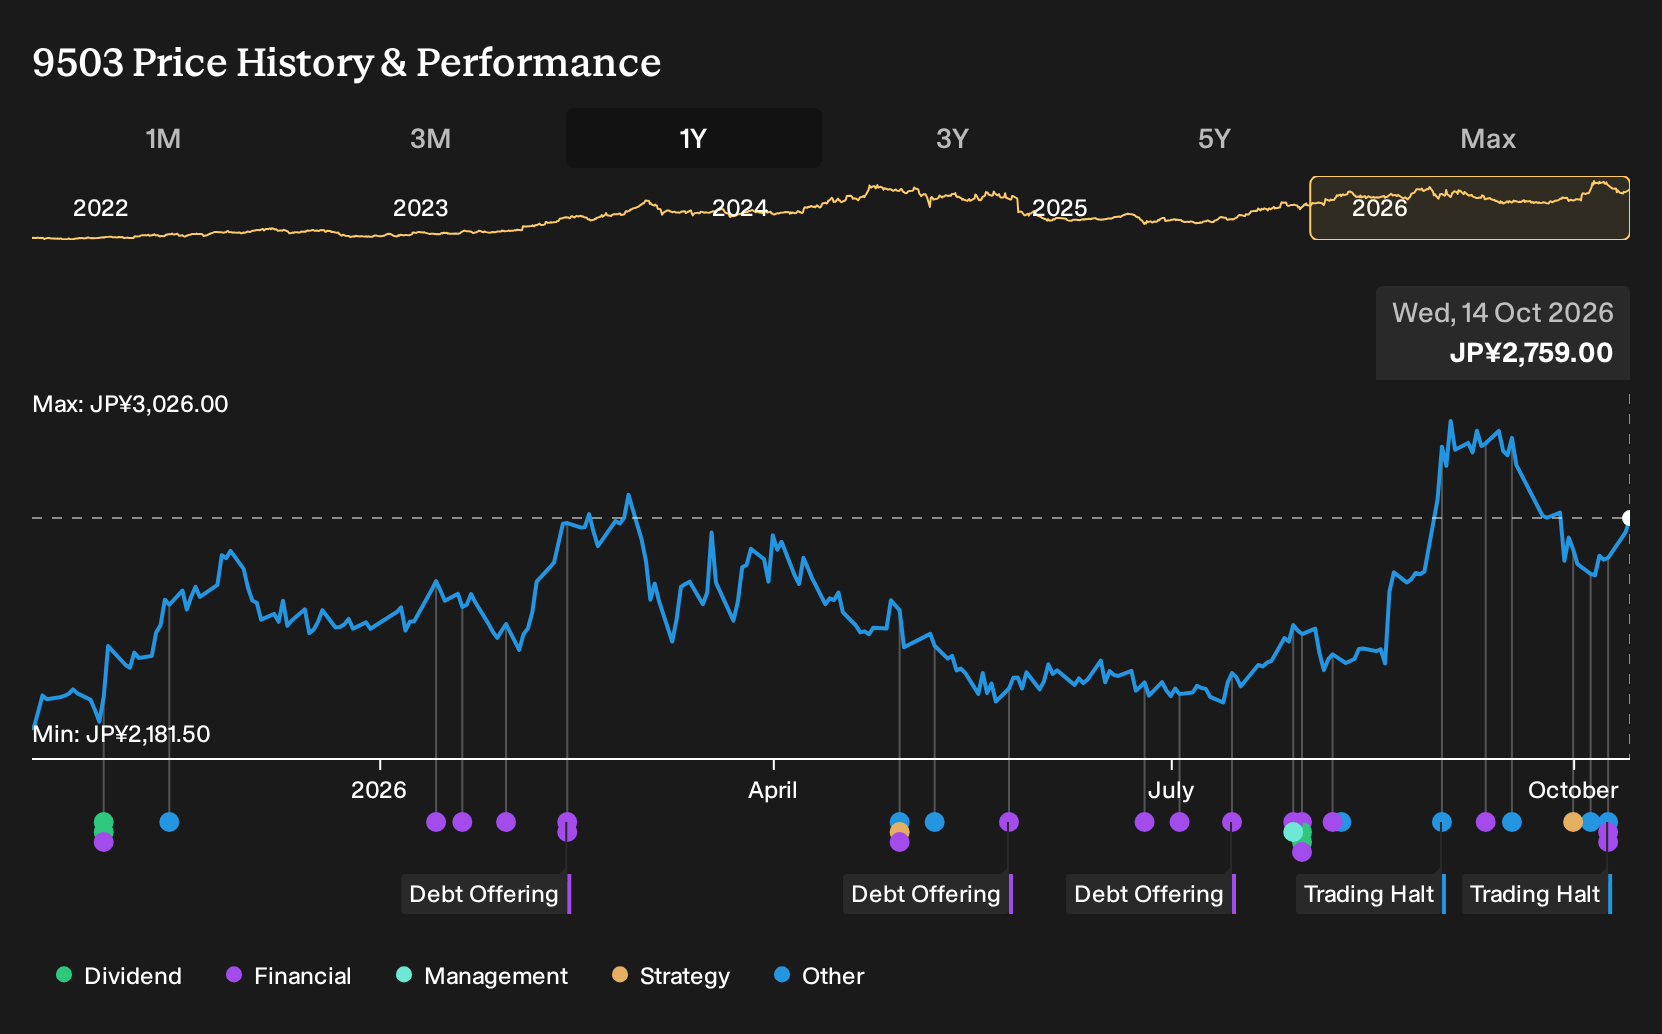
Uncover why Kansai Electric Power Company's fair value indicates a 7% potential upside to its current price that could close faster than investors expect.
Exploring Other Perspectives
Some of the lowest Kansai Electric Power Company forecasts lean hard into the risk that nuclear maintenance keeps earnings under pressure. Those analysts were pencilling in revenue of ¥4,029.1b and earnings of about ¥208.4b by 2029, well below consensus. The Mihama Unit 3 leak and restart plan could push those views to evolve, so treat this as a prompt to compare several narratives before making up your mind.
Explore 2 other Kansai Electric Power Company fair value estimates, including one that suggests as much as 11% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Kansai Electric Power Company research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Kansai Electric Power Company. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kansai Electric Power Company's overall financial health at a glance.
Looking for more Kansai Electric Power Company style investment ideas?
If the Kansai Electric Power Company story has sharpened your thinking, broaden your watchlist by using screeners that surface prospects with clear, testable investment cases.
- For investors who want potential upside with a quality filter, scan a focused set of 73 high quality undiscovered gems that pair solid fundamentals with lower market attention.
- If capital preservation is front of mind, narrow your search to 22 resilient stocks with low risk scores that score well on balance sheet strength and risk metrics.
- Income focused readers can zero in on cash return potential by reviewing 27 dividend fortresses that combine higher yields with business resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com