
Orion Oyj (HLSE:ORNBV) Expands In Oncology Following Qilu Deal As Fair Value Questions Linger
Orion Oyj (HLSE:ORNBV) has moved deeper into oncology by signing a European commercialisation deal with Qilu Pharma for an IV pembrolizumab biosimilar and by dosing the first patient in its ODM-216 immuno-oncology trial.
For investors watching Orion Oyj, these oncology moves arrive on the back of strong momentum, with a 90 day share price return of 20.8% and a year to date share price gain of 30.73%. The 5 year total shareholder return of 164.71% points to sustained investor confidence around the longer term story.
Scan beyond Orion Oyj and compare its oncology push with hand picked peers using the 127 healthcare AI stocks shaping the next wave of cancer and healthcare treatments.
Orion Oyj now trades above the average analyst target, yet screens at a sizeable discount to one estimate of fair value. Is the market prudently fading oncology excitement or mispricing the broader business?
Most Popular Narrative: 7.9% Overvalued
On the most followed view, Orion Oyj screens at a fair value of €76.67 compared with a last close of €82.75, which raises questions about how much oncology momentum is already priced in. That gap sits alongside solid earnings, high returns on equity and a clinical pipeline that is leaning harder into cancer therapies.
Healthy growth in the base business, where net sales reached €1.2b for the first nine months of 2025 and operating profit and cash flow also rose, together with balanced division contributions from Innovative Medicines, Generics, Branded Products and Animal Health, can support more resilient earnings and net margins.
See why 7 investors see Orion Oyj as 8% overvalued.
Result: Fair Value of €76.67 (OVERVALUED)
Still, Orion Oyj could see that overvaluation gap challenged if oncology trials deliver strong data or if Nubeqa related milestones and royalties surprise on timing.
Find out about the key risks to this Orion Oyj narrative.
Another View on Orion Oyj’s Value
The analyst narrative pegs Orion Oyj at a fair value of €76.67, which frames the stock as 7.9% overvalued versus the €82.75 share price. The SWS DCF model tells a very different story. On that approach, Orion screens as deeply undervalued, with the current price sitting 48.7% below an estimated future cash flow value of €161.23. Which lens do you trust more when the gap between them is this wide?
Look into how the SWS DCF model arrives at its fair value.
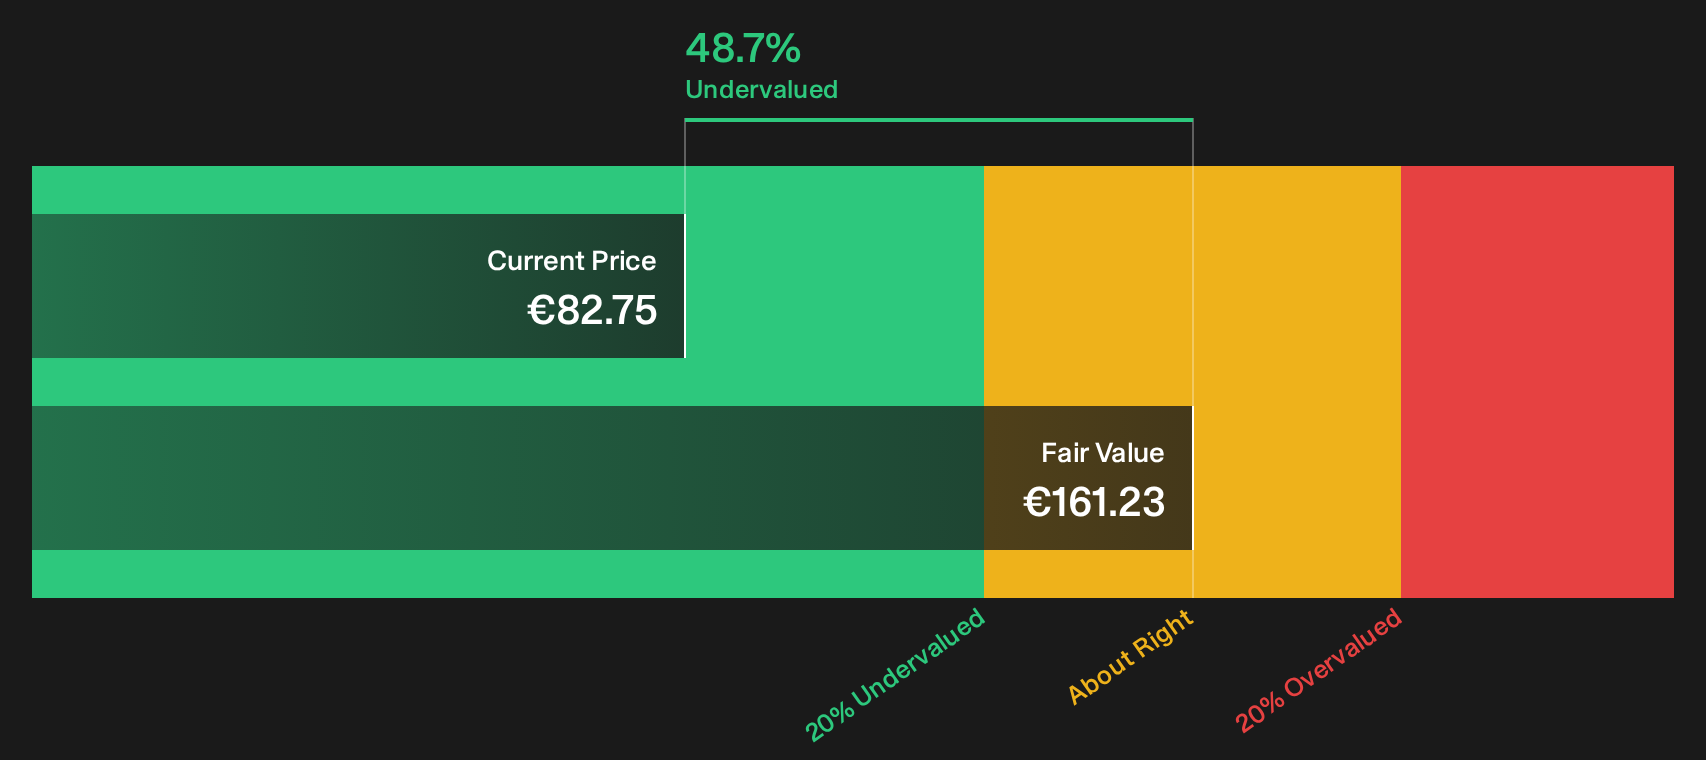
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Orion Oyj for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 185 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Orion Oyj is clearly split, which is exactly when independent thinking matters most. Move quickly, dig into the underlying data, and then weigh the 3 key rewards.
Looking for more Orion Oyj style investment ideas?
Do not stop your research at Orion Oyj. Use the Simply Wall Street Screener to uncover fresh opportunities that fit your portfolio and time horizon.
- Target resilient cash generators by scanning a list of solid balance sheet and fundamentals (204 results) that can better handle shocks and still support long term compounding.
- Hunt for value by focusing on a 185 high quality undervalued stocks where fundamentals and pricing look out of sync.
- Stack potential income streams by reviewing a 221 dividend fortresses that can help anchor your returns with regular cash payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com