
CME Group (CME) Stock Could Be 12% Overvalued On New AI Futures Plans
CME Group has quietly built a long track record of stock gains, and the recent price around US$278 a share keeps attention on what those returns say about the efficiency of the capital sitting behind its exchanges and clearinghouse. With the stock now reflecting years of compounding, the live question is whether that tag still lines up with the returns the business earns on the money invested in it.
- Over the past 5 years, CME Group has returned 57.7%, which puts pressure on investors to decide if the company’s return on capital justifies that kind of compounding from here.
- The planned futures tied to AI computing power using Nvidia chips and the ongoing cloud migration of CME Globex may support expectations for how much incremental return on capital the group can generate from new products and more efficient infrastructure.
- If you'd rather focus on earnings, this one's for you. See what CME Group's 23.4x P/E says about the price.
The issue now is whether the returns CME Group earns on its capital are strong enough to make the current share price look sensible on that measure.
If you are evaluating CME Group based on the returns it earns on its capital, it can be useful to compare it with other companies that have been screened for 32 high quality undervalued stocks
.Is CME Group Getting Expensive on Excess Returns?
The Excess Returns model looks at how much profit CME Group can generate above its cost of equity on each dollar of book value. On this view, the business is built on a relatively rich equity base of about $73.82 per share, with analysts expecting a stable book value closer to $85.01 per share over time. That capital is forecast to support stable earnings of roughly $13.65 per share, which points to an average return on equity of 16.06% against a cost of equity of $6.74 per share.
The gap between that earnings power and the equity charge feeds an excess return of $6.91 per share. This helps explain why the market is comfortable valuing the stock at around $278.03 today, even though the Excess Returns projections put CME Group's estimated intrinsic value modestly below the current share price. Because the planned futures tied to AI computing power using Nvidia chips broaden the product set around CME Group's existing franchise, the pricing gap may reflect investors already baking in additional growth from new contracts. Find out what CME Group could be worth using our Excess Returns estimate.
The CME Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the excess returns puzzle for CME Group leaves off and spell out what assumptions on growth, margins and earnings would need to hold for the stock to be worth materially more or materially less than today’s price. Each narrative ties a specific fair value to a single storyline about CME Group's potential catalysts and risks so you can track over time which version of the future seems to be taking shape on the Community page.
One of the top community narratives on CME Group: roughly fairly valued
"New product introductions, such as single stock futures, compute futures on NVIDIA H100 rental costs, wind power contracts and leveraged loan index futures, give CME Group more ways to grow..."
Discover why this Narrative puts CME Group at roughly fairly valued.
One more CME Group signal to check before you move on
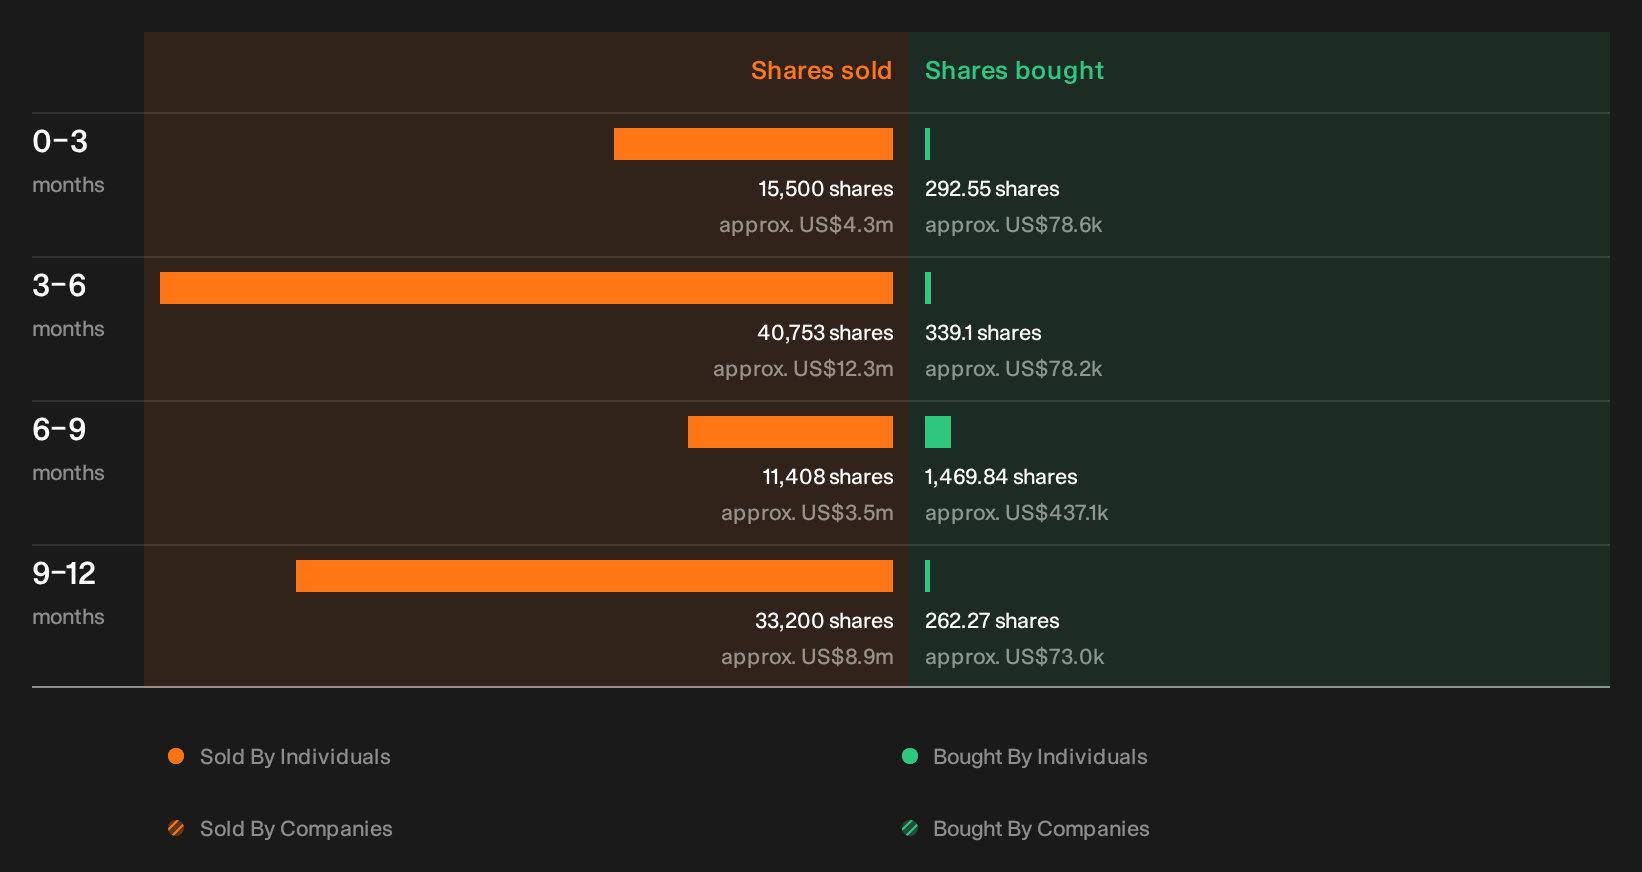
Before acting on any view of CME Group, it helps to know that recent transactions by people inside the business have been flagged, with the sellers, sizes and possible readthroughs left for you to review in detail. See the recent insider selling flagged for CME Group.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com