
Should Downtime Saving AI Require Action From Alfa Laval (OM:ALFA) Investors?
- Alfa Laval’s Clariot AI condition monitoring was highlighted in a Britvic case study, where early pump fault detection avoided six hours of downtime and protected 288,000 bottles of product during a planned maintenance stop.
- In the same period, commentary on solar district heating noted that Alfa Laval holds a 12% share of a sector projected to reach $7.01b by 2030, underlining how its heat transfer equipment is tied to long term decarbonization projects.
- We will examine how Alfa Laval's investment narrative is influenced by AI driven condition monitoring that helped Britvic avoid major downtime.
Scan 92 AI infrastructure stocks that, like Alfa Laval’s Clariot system, are applying AI to keep industrial assets running and critical production lines protected from costly downtime.
Alfa Laval Investment Narrative Recap
To own Alfa Laval, you need to be comfortable with an equipment maker that is tightly linked to long term energy transition, data center cooling and process industry projects, and that still carries meaningful exposure to shipping and oil and gas cycles. The Britvic case study around AI condition monitoring sits neatly in that picture. It reinforces the push toward higher value service, uptime guarantees and software infused offerings rather than changing the near term direction.
The near term swing factor remains how efficiently Alfa Laval converts its large project order book in Energy and Ocean into profitable execution without further mix pressure in big projects. Key risk sits in slower than expected clean energy and biofuel project activity or a cooling in marine capex, which could leave parts of the Ocean and Energy divisions less utilized and keep margins from improving.
The Britvic example of Alfa Laval’s Clariot AI system speaks directly to one of the clearest internal catalysts. Management has been leaning into a higher share of service and transactional business, with service already around 30 to 32% of group orders and close to 40% in Ocean. Condition monitoring that helps a beverage line avoid six hours of downtime is exactly the kind of use case that can support that shift.
For you as an investor, the interesting link is operational rather than promotional. If Alfa Laval can replicate similar Clariot deployments across food, pharma and marine customers, that can deepen the installed base, create more recurring diagnostics and maintenance work and make earnings less sensitive to lumpier equipment cycles. Execution discipline still matters a lot, especially in Energy where project mix and utilization have been pressure points, but the direction of travel toward more service heavy solutions is clear in this case study.
Alfa Laval Forecasts Tied To AI And Energy Transition
Alfa Laval's narrative projects SEK 91.2b revenue and SEK 11.6b earnings by 2029. This assumes 9.0% yearly revenue growth and an earnings increase of SEK 3.4b from SEK 8.2b today.
Uncover why Alfa Laval's fair value indicates that Alfa Laval is roughly in line with its current price.
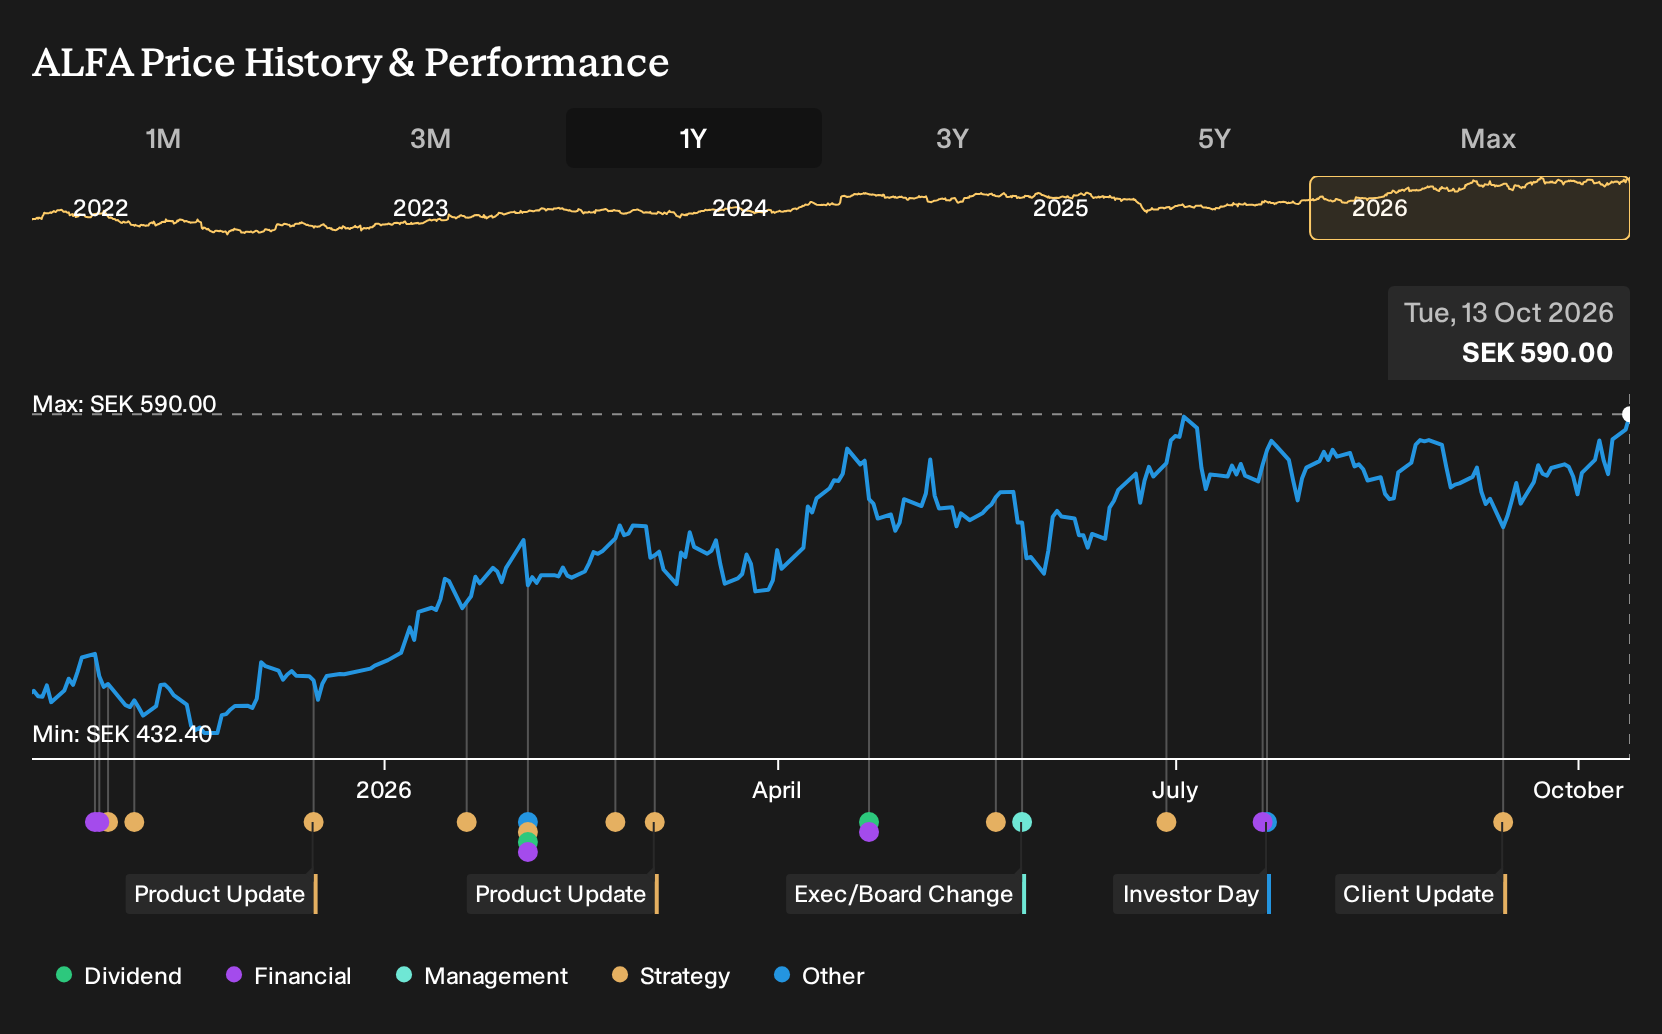
Exploring Other Perspectives
Some of the lowest ranked analysts lean hard into the risk that Alfa Laval’s heavy CapEx underdelivers. They were only pencilling in SEK 85.6b of revenue and SEK 10.6b of earnings by 2029, well below consensus. You can read that as a much more cautious story that the Britvic AI success might eventually challenge. Consider exploring both sets of assumptions before deciding what makes sense to you.
Explore 3 other Alfa Laval fair value estimates, including one that suggests as much as 27% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Alfa Laval research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Alfa Laval. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alfa Laval's overall financial health at a glance.
Looking For More Investment Ideas Beyond Alfa Laval?
If the Alfa Laval story has you thinking about where else reliable cash generation, defensiveness or mispricing might show up, the Simply Wall St Screener can help you filter the broader market down to a focused watchlist that fits your style.
- For investors who care most about quality at a sensible entry point, start with a curated set of 185 high quality undervalued stocks that pair strong fundamentals with more modest market expectations.
- If capital preservation and balance sheet strength matter to you, narrow your search to a list of solid balance sheet and fundamentals (204 results) that can help cushion tougher cycles.
- Those hunting for overlooked opportunities can review a hand picked pool of 619 high quality undiscovered gems that have flown under the radar despite solid financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com