
3 Global Growth Stocks With Up To 30% Insider Ownership
In a week marked by mixed performances across major U.S. stock indexes and heightened volatility due to geopolitical tensions and fluctuating energy prices, investors are closely monitoring the global markets for signs of stability. As interest rates remain a focal point with the Federal Reserve signaling potential further tightening, identifying growth companies with substantial insider ownership can offer insights into stocks that may align well with current market dynamics.
Top 10 Growth Companies With High Insider Ownership Globally
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.9% |
| Shanghai Biren Technology (SEHK:6082) | 10.4% | 119.7% |
| Meitu (SEHK:1357) | 23.1% | 26.7% |
| KebNi (OM:KEBNI B) | 16.3% | 103.8% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 32% |
| Fulin Precision (SZSE:300432) | 10.8% | 66.5% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
We're going to check out a few of the best picks from our screener tool.
SMS (TSE:2175)
Simply Wall St Growth Rating: ★★★★★☆
Overview: SMS Co., Ltd. operates in the nursing care, medical care, career, healthcare, and elderly care sectors by providing information infrastructure both in Japan and internationally, with a market cap of ¥221.16 billion.
Operations: The company generates revenue from its operations in the nursing care, medical care, career, healthcare, and elderly care sectors within Japan and internationally.
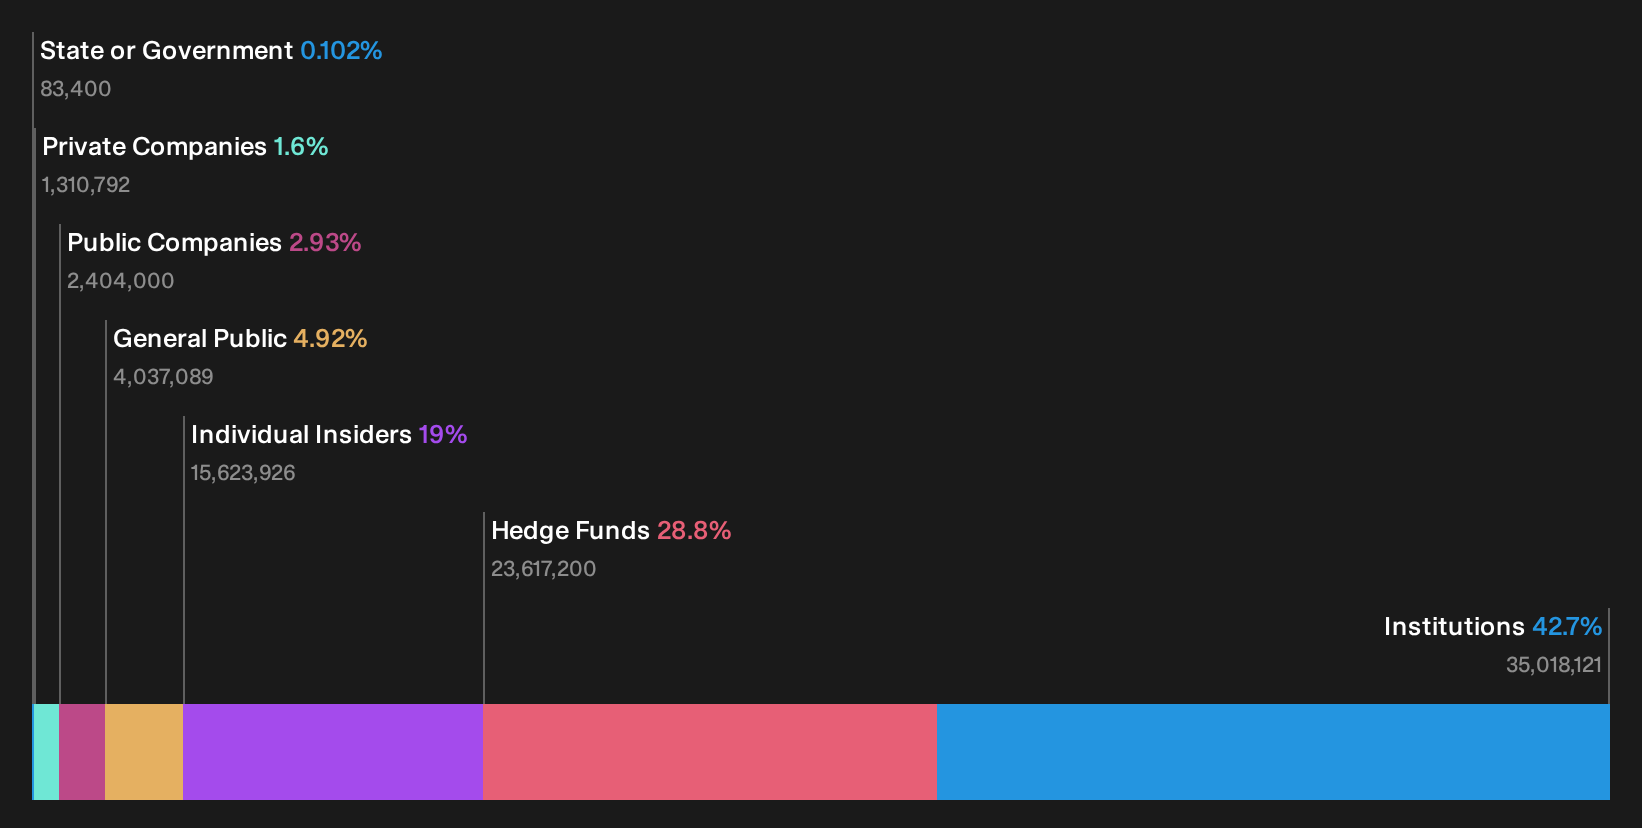
Insider Ownership: 19%
SMS Co., Ltd. is experiencing a phase of strategic shifts, highlighted by Oasis Management's recent activist involvement aiming to enhance corporate governance and value. Despite a slight dip in net income, the company reported an increase in sales for Q1 2026. With revenue growth forecasted at 9.8% annually, SMS is set to outpace the broader Japanese market's growth rate of 6.8%. Analysts expect substantial earnings growth of 56.75% per year, reflecting strong potential for profitability improvements over the next three years.
- Click here to discover the nuances of SMS with our detailed analytical future growth report.
- The valuation report we've compiled suggests that SMS' current price could be inflated.
Simplex Holdings (TSE:4373)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Simplex Holdings, Inc. offers IT solutions focused on system consulting, development, and maintenance in Japan with a market cap of ¥265.18 billion.
Operations: The company's revenue primarily comes from its IT Solutions segment, which generated ¥61.35 billion.
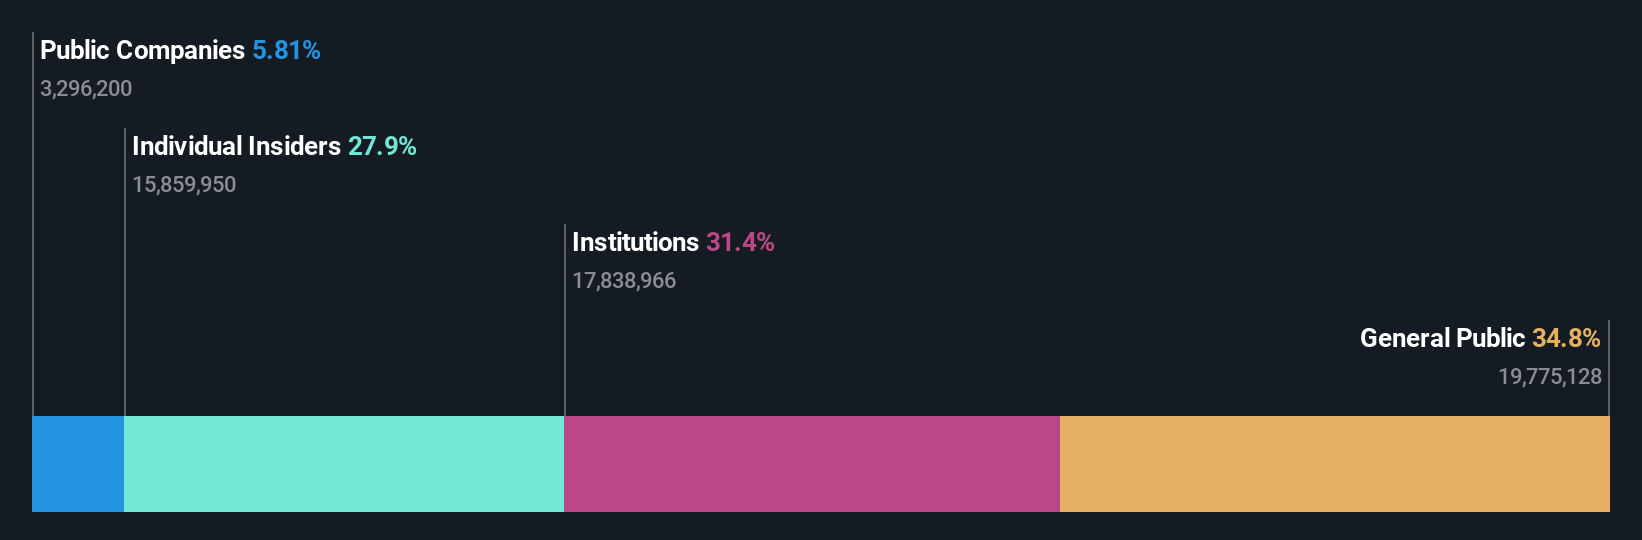
Insider Ownership: 30.3%
Simplex Holdings is poised for significant growth, with earnings forecasted to increase by 15% annually, outpacing the JP market. Revenue is expected to grow at 13% per year. Despite recent share price volatility, analysts predict a 20.3% rise in stock value. Recent earnings guidance indicates strong financial performance with projected full-year revenue of ¥70 billion and profit of ¥12.42 billion for fiscal year ending March 2027, alongside an increased dividend payout.
- Click here and access our complete growth analysis report to understand the dynamics of Simplex Holdings.
- Our expertly prepared valuation report Simplex Holdings implies its share price may be too high.
Shin Zu Shing (TWSE:3376)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Shin Zu Shing Co., Ltd. operates in Taiwan, Singapore, and China, focusing on the research, design, development, production, assembly, testing, manufacturing, and trading of precision springs and related components with a market cap of NT$33.18 billion.
Operations: The company's revenue segments include NT$9.42 billion from pivot products, NT$239.57 million from MIM products, and NT$151.53 million from turning and milling products.
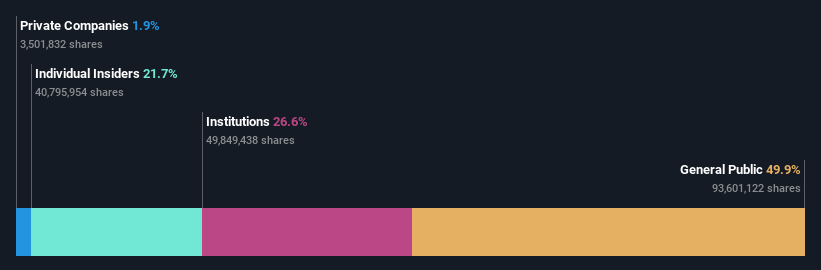
Insider Ownership: 18.4%
Shin Zu Shing is set for substantial growth, with earnings projected to rise 66.1% annually, surpassing the TW market. Revenue growth is also expected to outpace the market at 44.1% per year. Despite trading 38.5% below estimated fair value and a low return on equity forecast of 13%, analysts foresee a stock price increase of 51.2%. Recent results show improved profitability with net income reaching TWD 62 million in Q2, reversing last year's loss.
- Click to explore a detailed breakdown of our findings in Shin Zu Shing's earnings growth report.
- The valuation report we've compiled suggests that Shin Zu Shing's current price could be quite moderate.
Next Steps
- Access the full spectrum of 712 Fast Growing Global Companies With High Insider Ownership by clicking on this link.
- Looking For Alternative Opportunities? AI is about to change healthcare. These 127 stocks are working on everything from early diagnostics to drug discovery. The best part - they are all under $10b in market cap - there's still time to get in early.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com