
The Bet B&M European Value Retail Holders Made
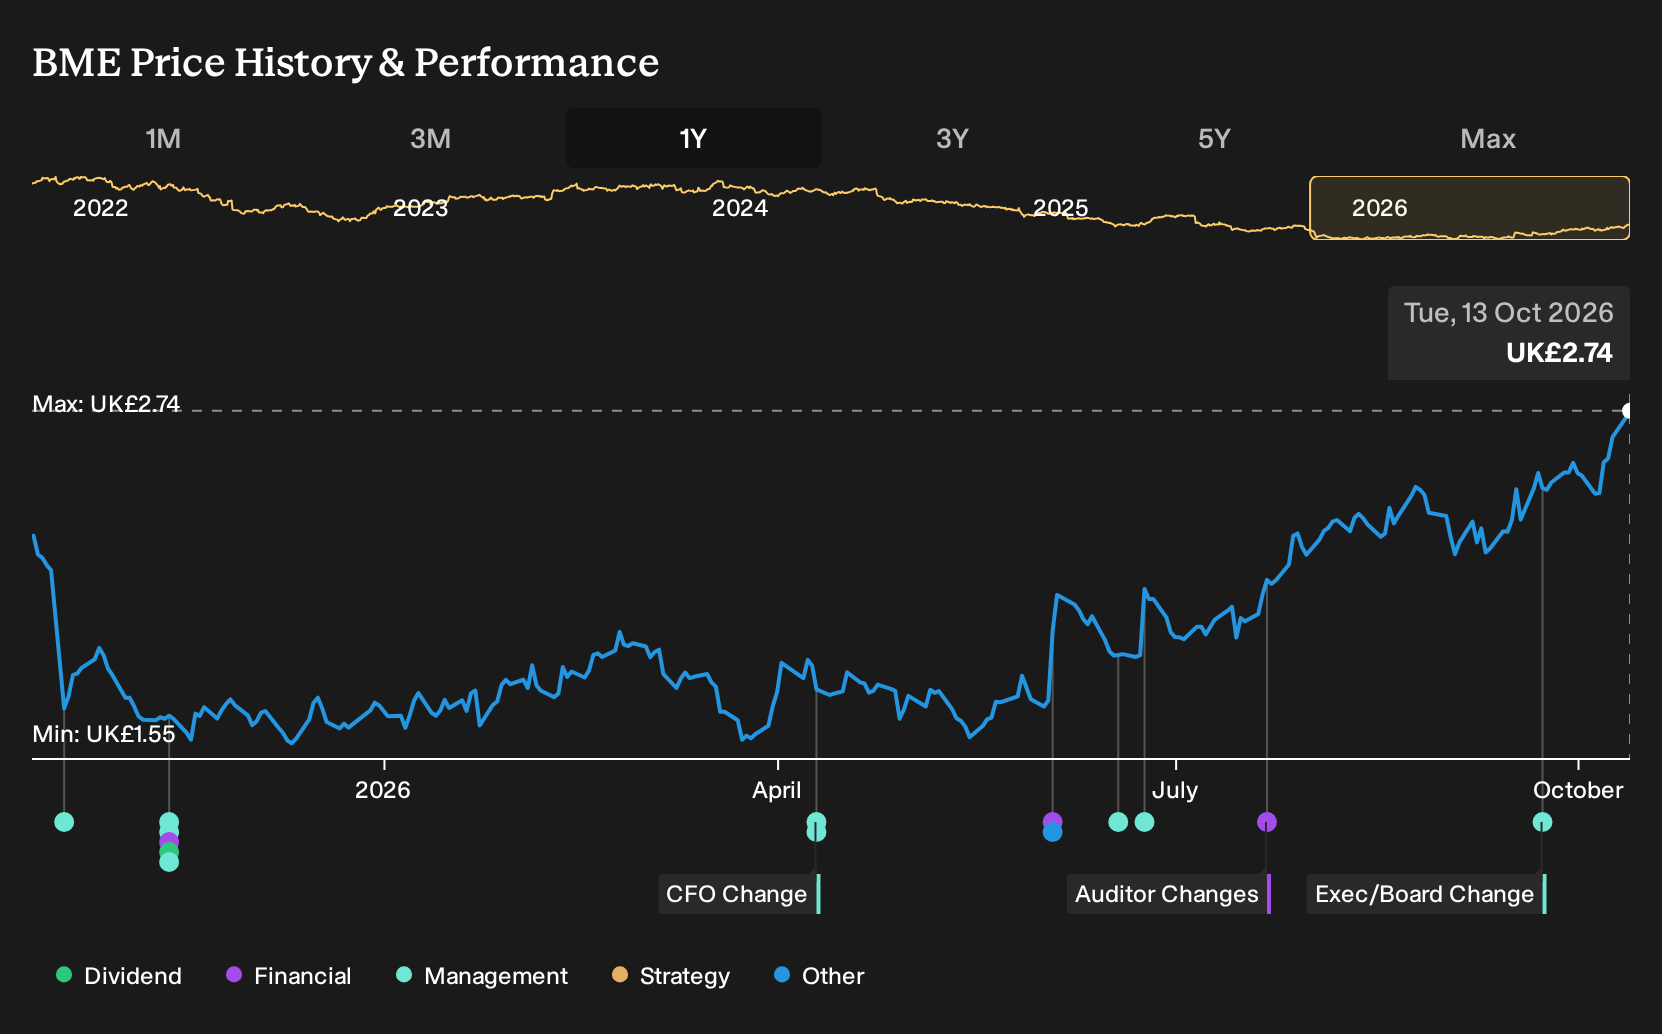
B&M European Value Retail spent the year talking about everyday low prices and new store openings while later reporting that revenue reached £3,026m in H2 2026 and net income excluding extra items came in at £111m. Investors who held B&M European Value Retail over the past year are up 29.7%, including dividends. If you were deciding back on 13 October 2025, what would you have needed to believe about those plans and pressures to buy with confidence?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind B&M European Value Retail. Zero in on 8 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing Up On B&M European Value Retail
The shares cost £2.29 at the start of the period, so any decision on B&M European Value Retail began with a simple question. Was the market underestimating its discount model or correctly flagging structural pressures?
The bullish narrative put Fair Value at £4.08, 78% above the start price. That view leaned on Everyday Low Prices, volume growth and new stores, with cost control and direct sourcing expected to support net margins, while cash returns through dividends and buybacks were seen as signalling confidence in future cash flows.
The bearish story anchored on a Fair Value of £2.07, 10% below the start price. It focused on exposure to lower income UK shoppers, pressure from e-commerce and discount rivals, and the risk that further UK expansion into an increasingly saturated market could strain profitability.
What The Results Changed For The B&M European Value Retail Thesis
The clearest new fact for B&M European Value Retail was the H2 2026 report. Revenue reached £3,026m compared with £2,927m in H2 2025, yet net income excluding extra items moved from £196m to £111m and net margin slipped from 6.7% to 3.7%. That pattern challenged the optimistic margin story and gave more weight to the cautious case around profitability pressure.
The episode turned on one assumption. Stronger sales were expected to support healthy earnings. When checking another retailer, track whether changes in net income and margin line up with top line trends, especially when the pitch leans on cost control and operating efficiency.
What Today's B&M European Value Retail Price Already Assumes
B&M European Value Retail now trades at £2.74, after a 29.7% gain over the past year. This Narrative’s Fair Value sits below the current price, reflecting a more cautious stance on what is already embedded in the valuation.
The argument leans on Back to B&M Basics, SKU cuts and better availability turning into steadier like for like sales and margin repair. A buyer today is effectively assuming that store roll outs and margin rebuilding work. The key question is how the risk of already thin FMCG pricing affects that bet.
"The current valuation implies the share price already reflects a successful margin recovery, ongoing cash generation and self funded expansion despite recent profit pressure and reduced equity research enthusiasm."
The price and this Narrative do not agree. → Uncover what this Narrative says B&M European Value Retail is actually worth
Looking Beyond B&M's Aisles
Once you understand B&M, it feels natural to look wider. Discount chains depend on strict costs and lean operations. That raises a question about who quietly powers their efficiency.
One large digital platform has been investing in smarter logistics and data tools. It aims to automate ordering, delivery and in store promotion.
That spending also extends into cloud services and digital advertising. Retailers can use those systems to target demand and adjust pricing.
If B&M keeps sharpening its stores, this other player refines the digital rails. The open question is how much retail value could tilt toward that infrastructure.
That argument has a Narrative and a number behind it. → See the company one Narrative values 74% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com