
Church & Dwight (CHD), What Is Behind The Fresh Attention?
Soft Organic Sales Put Church & Dwight Under the Microscope
Recent commentary on weak organic sales at Church & Dwight (CHD) has refocused attention on how the company plans to generate growth while peers report stronger earnings momentum.
Those soft organic sales updates are landing against a share price that has been quietly grinding higher, with a year-to-date share price return of 21.16% and a 1-year total shareholder return of 16.67%, which points to momentum still building around Church & Dwight despite questions about future demand.
Compare Church & Dwight’s momentum and valuation with a carefully filtered set of consumer-focused businesses by scanning the 32 high quality undervalued stocks.
Church & Dwight appears to be a solid consumer staples business, yet the share price has already climbed more than 20% in 2026. Are you paying up for quality, or still getting a reasonable entry point?
Most Popular Narrative: 4.7% Undervalued
On the most followed view of Church & Dwight, a fair value of about $105 sits modestly above the last close at $100.13. This places the recent share price strength against a thesis built on growth quality rather than rapid expansion.
The numbers imply the Church & Dwight share price reflects a market that remains cautious on growth and margin durability despite the company raising its 2026 organic sales, EPS and cash from operations guidance and continuing to target its evergreen model.
See why 13 investors see Church & Dwight as 5% undervalued.
Result: Fair Value of $105 (UNDERVALUED)
Still, the Church & Dwight story can crack if vitamin gummies keep dragging consumption, or if elevated SG&A and stranded costs squeeze the margin thesis.
Find out about the key risks to this Church & Dwight narrative.
Another View: What Church & Dwight’s P/E Is Telling You
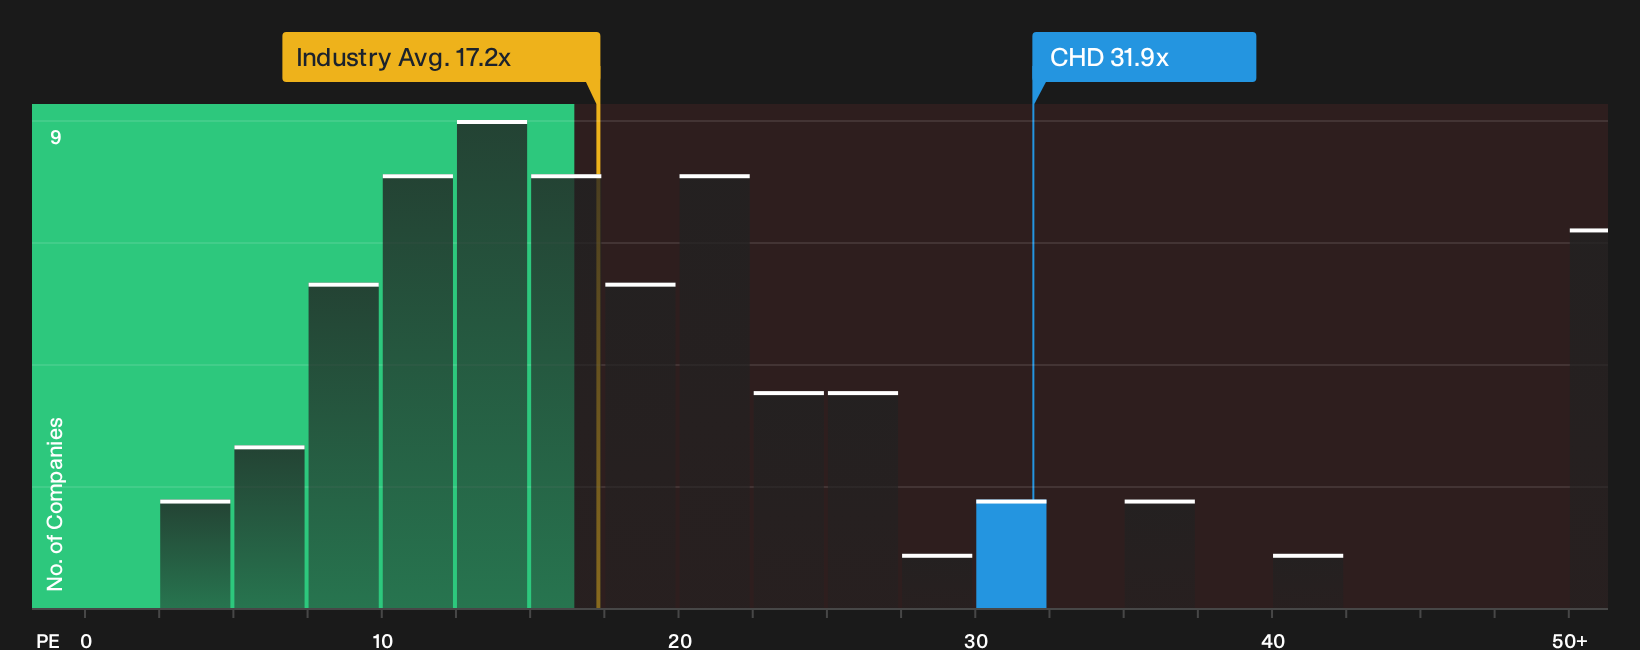
On a simple P/E check, Church & Dwight looks expensive. The stock trades at 31.9x earnings, compared with about 21.4x for peers and 17x for the wider global household products group. The fair ratio sits at 19.4x, which points to valuation risk if sentiment or execution slip.
If you prefer to anchor on earnings multiples rather than cash flow models, this gap is a useful stress test for your thesis on CHD’s quality and durability, especially with softer organic sales in the mix. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Church & Dwight so far, right? If you want to move quickly and sharpen your own take, you can weigh both sides of the debate through 3 key rewards and 1 important warning sign.
Hunting For More Ideas Beyond Church & Dwight?
Do not stop your research with Church & Dwight. Broaden your watchlist and pressure test your convictions by lining up alternatives that match your risk and return preferences.
- Target dependable income streams and stress test your yield focus with a curated set of reliable payers through the 8 dividend fortresses.
- Zero in on resilience by filtering for companies with robust finances and low leverage using the list of solid balance sheet and fundamentals (25 results).
- Hunt for tomorrow's potential standouts before the crowd notices them by scanning the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com