
Why Kimco Realty (KIM) Is Getting Fresh Attention
Fresh valuation work on Kimco Realty (KIM) has reignited attention on the stock, with analysts citing projected cash flows and firm leasing spreads as key factors supporting an intrinsic value estimate that is higher than the current share price.
Recent trading has been choppy for Kimco Realty, with the share price down 10.52% over 90 days and 3.19% over 30 days. At the same time, the year-to-date share price return of 11.91% and 3-year total shareholder return of 46.96% point to longer-term momentum that aligns with the renewed focus on cash flow driven valuation work.
Compare Kimco Realty's valuation story with a curated group of real estate driven opportunities, screened for strong fundamentals and cash flow support using the 32 high quality undervalued stocks.
Recent volatility has knocked Kimco Realty back, even as cash flow models point to an intrinsic value above the current US$22.45 share price. Is that a reason to add exposure now, or to wait for a deeper pullback before committing fresh capital?
Most Popular Narrative: 14% Undervalued
Kimco Realty's most followed narrative pegs fair value at about $26.18 a share compared with the recent $22.45 close. This puts the current debate firmly on how durable its cash flows really are under that 8.2% discount rate.
The ongoing focus on acquiring and developing grocery anchored centers in high income, necessity driven trade areas, where only about 0.2% of existing retail stock is under construction and new projects often require 30% to 60% higher rents to pencil, supports stable occupancy and pricing power that can sustain rental income and net margins.
Find out how 7 investors see Kimco Realty as 14% undervalued.
Result: Fair Value of $26.18 (UNDERVALUED)
Still, the Kimco Realty narrative can unravel quickly if refinancing around US$800 million of 2026 debt bites into earnings, or if the tenant lawsuit escalates and disrupts leasing momentum.
Find out about the key risks to this Kimco Realty narrative.
Another View: Kimco Realty On Earnings Multiples
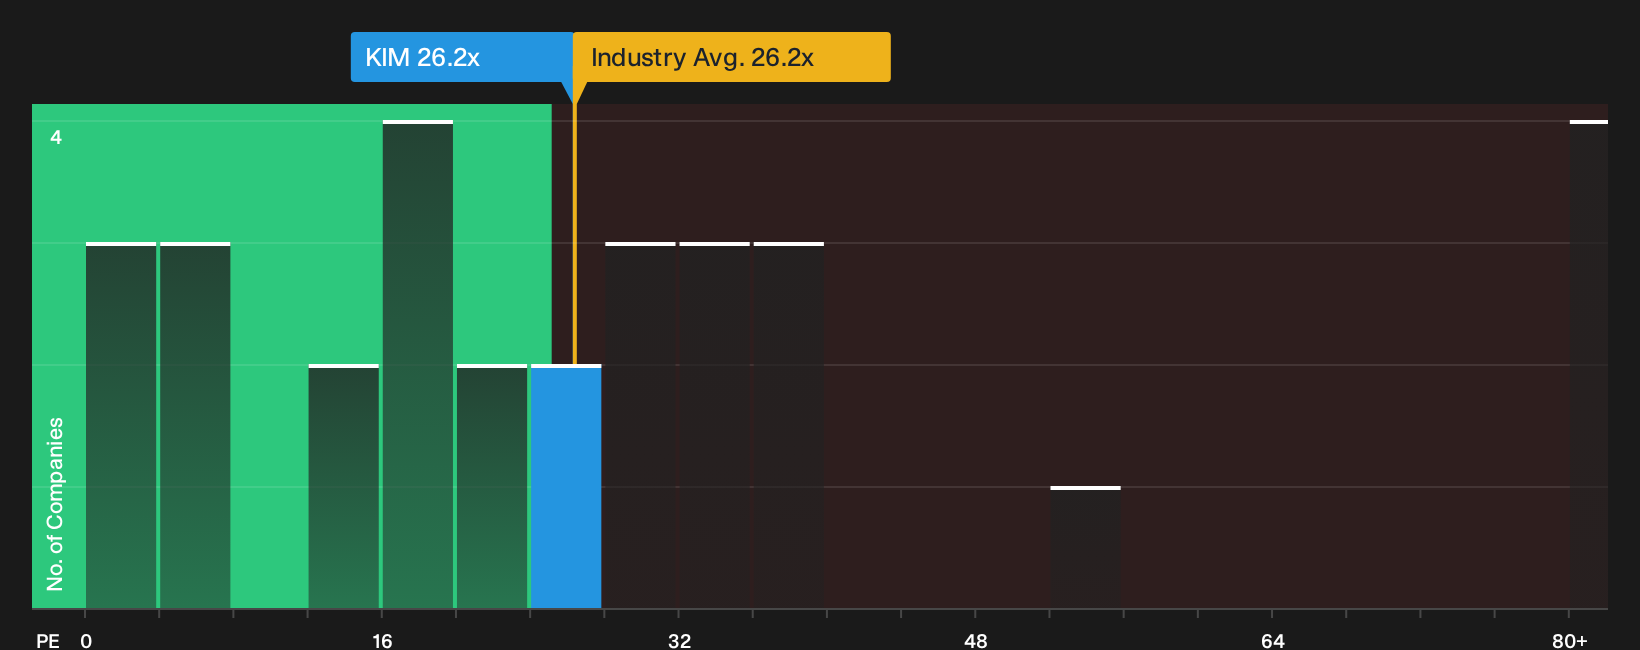
The DCF work paints Kimco Realty as undervalued, yet the earnings multiple tells a tighter story. At a 26.2x P/E, the stock is slightly more expensive than the US Retail REITs industry at 26.1x and pricier than the 21.3x peer average. It is still below a fair ratio of 31.9x that the market could move toward. Does that mix of mild premium and theoretical headroom signal limited upside or a patient opportunity if sentiment improves?
See what the numbers say about this price and how they fit together in context with the broader sector using the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
The mixed tone around Kimco Realty, split between opportunity and concern, only matters if you put the underlying facts to work. Act quickly, review both sides of the argument, and weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Kimco Realty?
Do not stop with Kimco Realty. Use the Simply Wall Street Screener to look for additional opportunities that fit your style before the market prices them in.
- Target dependable income streams by reviewing 8 dividend fortresses backed by generous payouts and balance sheets that support those distributions.
- Search for quality at a discount through the 20 high quality undiscovered gems and see which under-the-radar businesses show strong fundamentals.
- Dial down risk across your watchlist by filtering through the 32 resilient stocks with low risk scores that pair resilience with measured volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com