
Zoetis (ZTS) Stock May Sit Below Fair Value After Mixed Q2 Results
Zoetis has seen its share price weaken materially in recent years, and with earnings now in the spotlight, the question is whether the current valuation still lines up with what the business is generating.
- The stock is down 61.6% over the past 5 years, which puts real pressure on the case that today’s market price accurately reflects Zoetis’ earnings power.
- Recent mixed operating trends, including pressure in key companion animal categories alongside growth in other regions and products like Simparica Trio, can reshape expectations for how reliably future profits convert from current earnings.
- The analysts covering Zoetis have run their own numbers. See what analysts think Zoetis's shares could be worth.
For investors, the debate is whether Zoetis’ current share price is justified by its earnings when set against the Fair Ratio benchmark.
If you want to explore the same earnings question you are considering for Zoetis across a wider set of ideas, scan through our screener containing 20 high quality undiscovered gems.
Is Zoetis Still Cheap on Earnings?
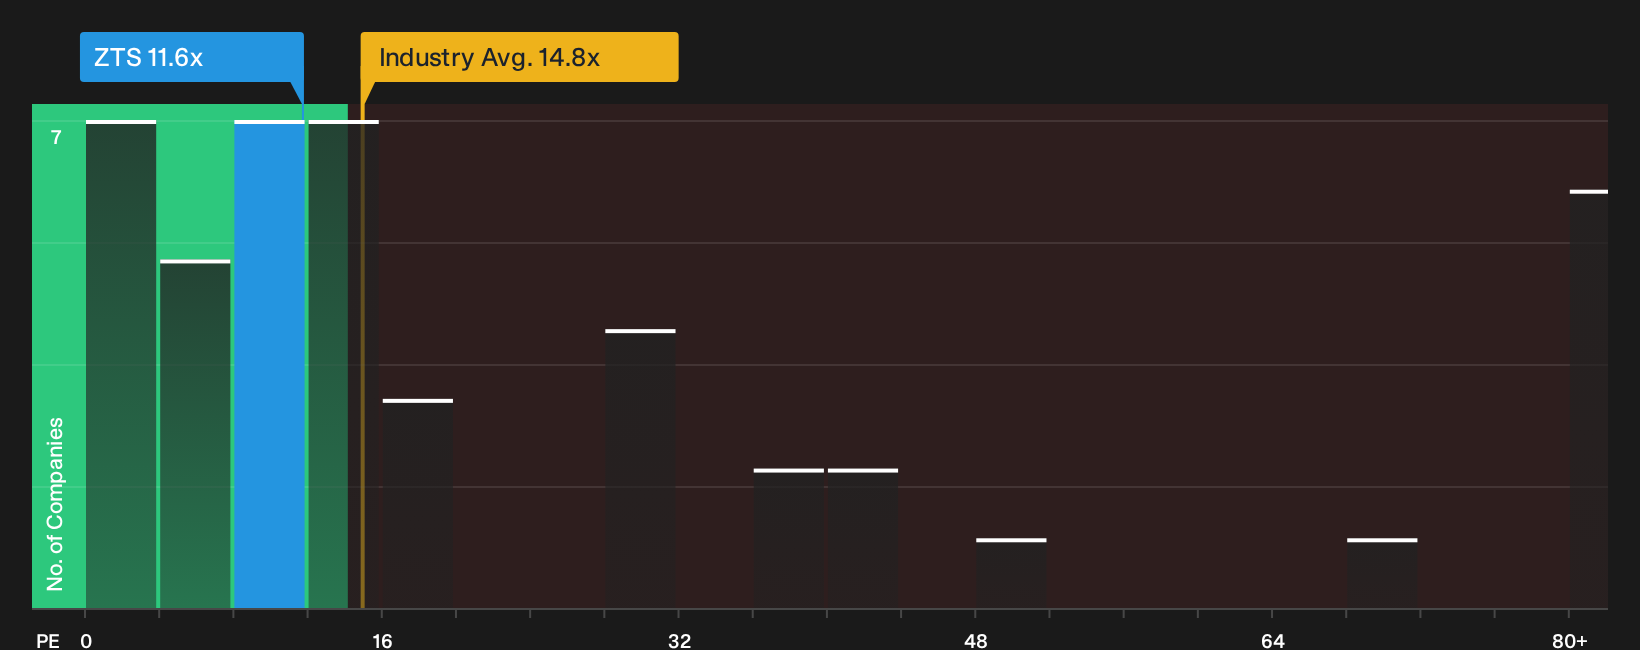
The P/E ratio suits Zoetis because earnings remain a central reference point for how investors frame this kind of animal health business. On this lens, Zoetis trades at roughly 11.6x earnings, which is below the Pharmaceuticals sector average of about 14.8x and far under the peer group around 31.5x. That gap suggests investors are assigning a lower price tag to each dollar of Zoetis profit than to many comparable drug makers.
Because the Fair Ratio captures what P/E might look like after factoring in Zoetis specific mix of growth prospects, margins, size and risk, the current multiple sits below that benchmark and screens as undervalued on this framework. Recent Q2 2026 results, with pressure in U.S. companion animal revenue and trimmed guidance, help explain why sentiment is cautious. At the same time, the valuation still prices Zoetis at a discount to what this earnings model implies. Explore the numbers behind Zoetis's P/E valuation.
The Zoetis Narrative: What Would Justify Today's Price?
Narratives pick up where Zoetis' valuation gap leaves off and spell out which combinations of future growth, profitability and earnings resilience would need to play out for the stock to be worth much more or much less than today’s quote. These narratives are available on Simply Wall St’s Community page.
Each one presents Zoetis' implied fair value as a thesis about the business that you can revisit over time to see how the story holds up against new results.
One of the top community narratives on Zoetis: 20% undervalued
"On one hand it’s not a business that’s going to grow much. On the other hand, it’s also not likely to collapse catastrophically…"
Discover why this Narrative puts Zoetis at 20% undervalued.
Zoetis’ price is only one piece of the investment puzzle
Before you make any call on Zoetis, you also need to understand who is steering the business, how their incentives are structured, and what that means for your potential outcomes. See who runs Zoetis and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com