
Maxvalu Tokai (TSE:8198) Stock Faces Margin Crunch Despite Deep Value Gap
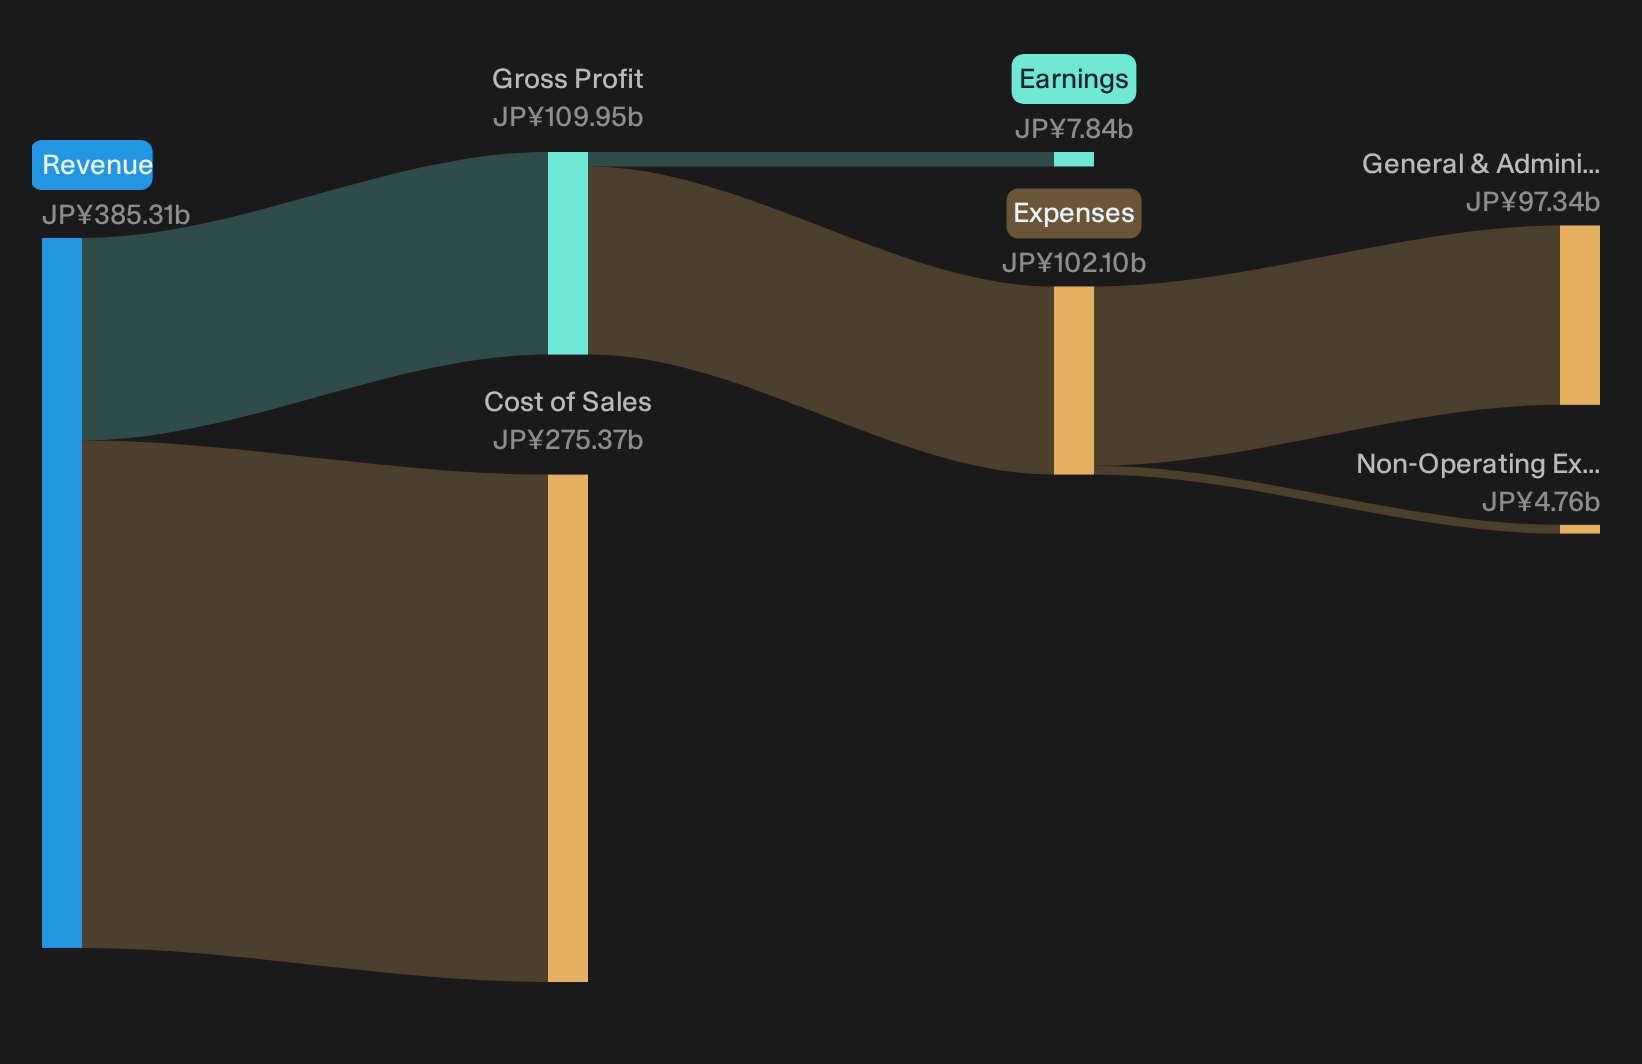
Maxvalu TokaiLtd shareholders watched the stock grind down about 3% over the past week and roughly 6% over the past month. Yet the fresh Q2 print tells a more nuanced story. Quarterly revenue held at ¥97,610m while net income reached ¥1,624m, and the trailing 12 month net margin sat at 2%. For a supermarket operator that lives on thin profitability, that squeeze in profitability is the real headline. Short term traders are reacting to the price chart. Longer term holders are likely focusing on how this margin pressure collides with a reported 12.7x P/E and a dividend yield of 2.72%.
Is Maxvalu TokaiLtd trading like a genuine bargain given the reported 67.5% discount to an estimated ¥9,596.64 fair value, or does the recent 2% net margin tell a different story? See how that gap resolves in the full valuation analysis for Maxvalu TokaiLtd.Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥97,610m vs. ¥96,879m (up about 0.8%)
- Net Income, Excl. Extra Items (Q2 2027 vs. Q2 2026): ¥1,624m vs. ¥3,654m (declined about 55.5%)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥50.93 vs. ¥114.62 (fell about 55.6%)
- Trailing 12 Month Net Margin (to Q2 2027 vs. prior year): 2.0% vs. 2.9% (compressed by 0.9 percentage points)
Prefer clean charts instead of another wall of earnings tables and footnotes? See Maxvalu TokaiLtd’s full financial picture, including how its valuation compares with the latest results, in the company report for Maxvalu TokaiLtd.
Maxvalu Tokai bullish story meets thinner profits
For investors leaning on Maxvalu Tokai as a defensive supermarket play, the top line still roughly fits that script. Revenue in Q2 2027 was ¥97,610m and sat close to the prior year, which supports the idea of steady demand for everyday groceries. The problem is what trickles down. Net income excluding extra items of ¥1,624m and a trailing 12 month net margin of 2% point to a business that is defending sales but giving up profitability to do it.
Profit squeeze gives the cautious view more weight
The more cautious story around Maxvalu Tokai gets support from these earnings. Net income excluding extra items roughly halved year on year while basic EPS fell at a similar rate. The trailing margin compressed from 2.9% to 2%. For a supermarket that already runs on tight economics, that is meaningful pressure. Recent share price performance, down over 6% across 30 days and weaker over 90 days, suggests equity holders are already treating this profit trend as a real risk, not a passing blip.
Check whether Maxvalu TokaiLtd’s thinner 2% net margin still sits on top of a robust balance sheet or a quietly eroding cash position. Verify the debt, liquidity and dividend safety math in the financial health analysis of Maxvalu TokaiLtd stock.Take Control Of Your Next Move
If Maxvalu TokaiLtd’s mix of a reported 67.5% discount to an estimated fair value and a tight 2% net margin has your attention, register for free with Simply Wall St and add it to a Watchlist to track price against valuation and wait for your preferred entry point. Once you own shares, keep your decisions grounded in data by using the Portfolio Command Center to cut through day to day noise and focus on the updates that actually affect your thesis. For a broader lens on Maxvalu TokaiLtd, lean on the Community to see how other investors are interpreting the same figures and risks. That combination can help you identify possible catalysts and potential problems early so you remain informed about developments in the wider market.
Curious About Alternatives Worth Exploring
Fresh ideas move first. Some themes are already building quiet breakout momentum while they are still under the radar for now, and the best entries get caught early, act now.
- Spot durable income themes with pricing power by scanning a curated set of strong payers using the 27 dividend fortresses.
- Chase early momentum in capital-intensive projects by reviewing infrastructure-focused names across the 43 power grid technology and infrastructure stocks before the crowd fully wakes up.
- Track quietly compounding balance sheets by filtering for resilient operators in the list of solid balance sheet and fundamentals stocks (21 results) while information still gives you a first-mover edge.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com