
Should AI Data Center Growth Require Action From Quanta Services (PWR) Investors?
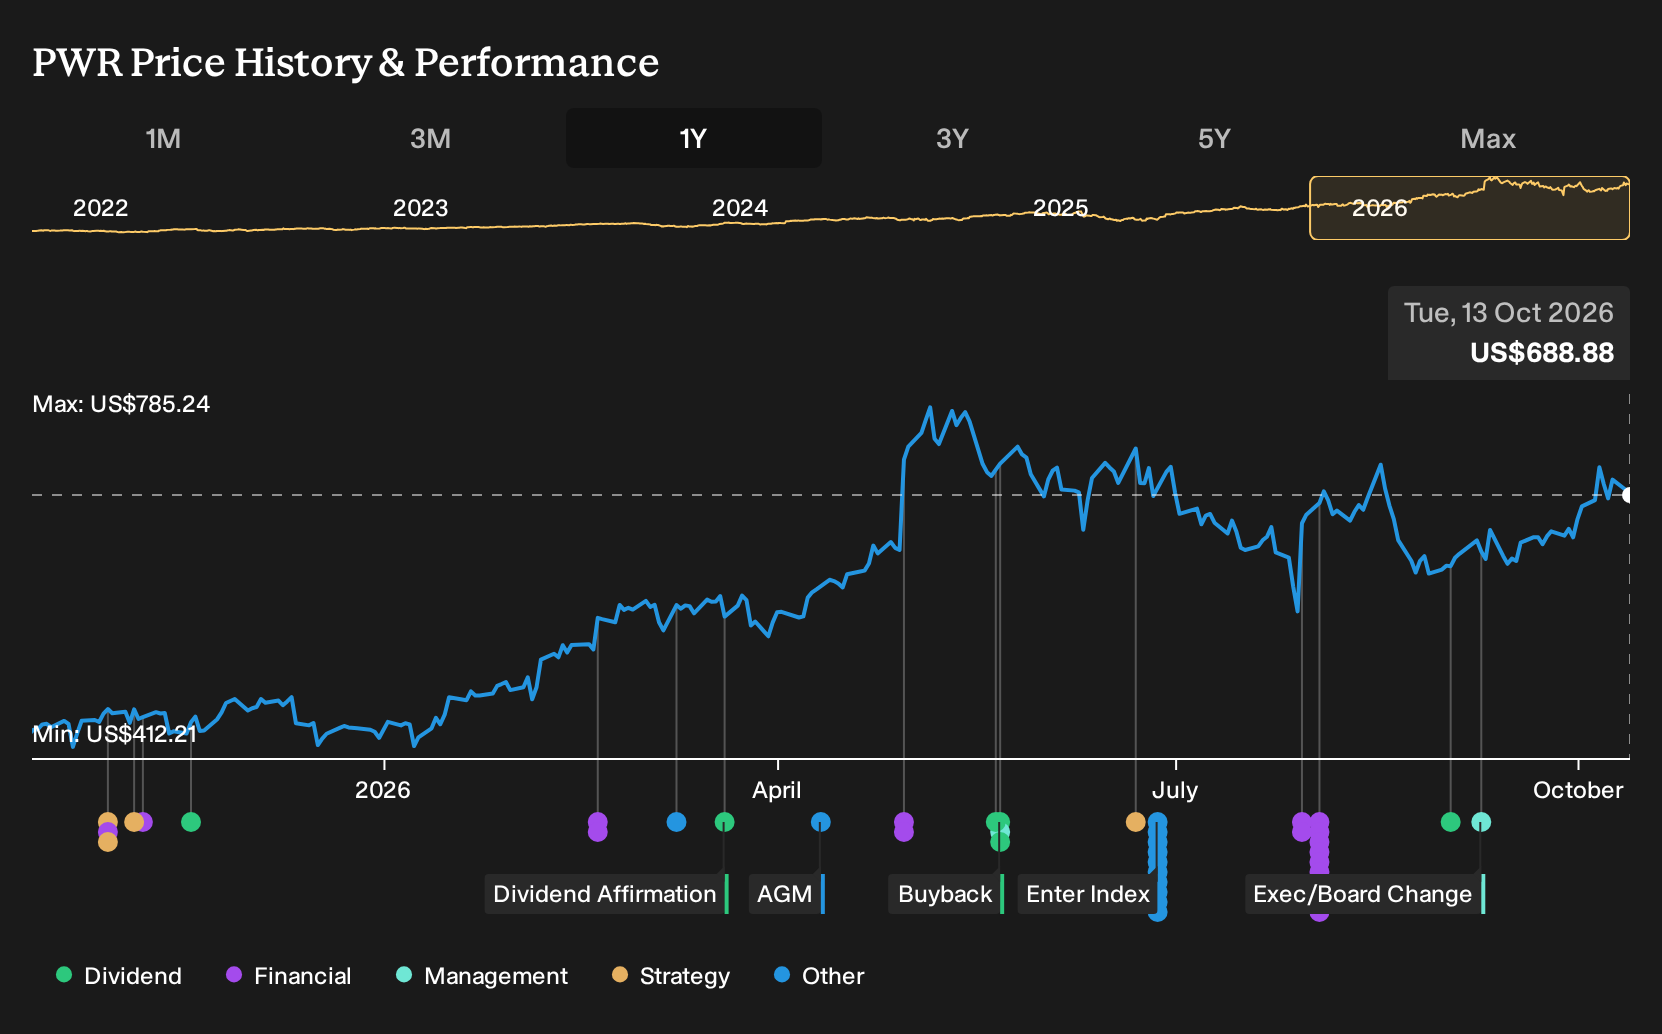
- Quanta Services recently outlined expectations for very strong revenue expansion in its Technology & Load Centers segment in 2026, tied to accelerating data center construction, AI infrastructure builds, and contributions from recent acquisitions. The company also scheduled its third quarter 2026 earnings release and webcast for October 29, 2026.
- The focus on AI powered data centers suggests Quanta Services is leaning further into large load power infrastructure work that can test execution capacity, labor availability, and integration of acquired businesses at scale.
- We will look at how Quanta Services investment narrative is affected by this projected AI driven Technology & Load Centers expansion.
Quanta Services Investment Narrative Recap
To own Quanta Services, you need to believe the company can keep turning a record backlog and AI heavy large load pipeline into projects delivered on time and at the margins it targets. The near term swing factor is execution in Technology & Load Centers as data center related work ramps and acquired businesses are absorbed into that platform.
The main risk right now is that expectations have moved higher after multiple 2026 guidance raises and a rich P/E, so any stumble on complex power infrastructure or weaker acquisition contribution could hit sentiment. The latest announcements do not fundamentally change that risk reward balance in the short term.
The most relevant update is that Quanta Services has set the date for its third quarter 2026 results and webcast on 29 October. That event becomes the next checkpoint where investors can test the AI driven Technology & Load Centers story against hard numbers on backlog mix, margins and cash conversion across the portfolio.
Attention will likely focus on how management talks about high voltage execution capacity, transformer manufacturing investments and the contribution from acquisitions such as Phalcon, Enerfab, Percheron and PSD. Any detail on labor availability, permitting delays and balance sheet flexibility could also shape how investors weigh strong project demand against valuation, leverage and guidance risk.
Quanta Services' consensus narrative points to revenues of US$54.6b and earnings of US$2.7b by 2029. That profile builds on an 18.4% yearly revenue growth assumption and an earnings move of about US$1.4b from US$1.3b today to the US$2.7b forecast level.
Explore how Quanta Services' fair value suggests a 12% potential upside to its current price before the market fully reflects that valuation.
Exploring Other Perspectives
One bullish twist on Quanta Services focuses on earnings power rather than valuation risk. The most optimistic analysts were already penciling in about US$64.6b of revenue and US$3.2b of earnings by 2029 before this AI heavy update. You might read that as a sign that views can swing widely. The upcoming October 29 earnings release could easily push those expectations in either direction, so it helps to explore several viewpoints rather than rely on a single story.
Explore 5 other Quanta Services fair value estimates, including one that suggests as much as 18% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Quanta Services research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Quanta Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Quanta Services' overall financial health at a glance.
Looking For More Ideas Beyond Quanta Services?
If the Quanta Services story has sparked new questions about where to put fresh capital to work, it can help to scan a wider set of candidates with similar or contrasting traits. The Simply Wall St Screener lets you filter for different profiles so you can build a watchlist that fits your own risk tolerance and income goals.
- For investors who care most about quality at a sensible entry point, review a 32 high quality undervalued stocks that combine solid fundamentals with pricing that screens as attractive on key metrics.
- If capital preservation and steadier profiles matter more to you than chasing every AI theme, focus on 32 resilient stocks with low risk scores that show resilient characteristics across financial health and volatility checks.
- When you want to get ahead of the crowd and hunt for tomorrow's potential leaders, start with 20 high quality undiscovered gems that pair strong balance sheets with less widely followed stories.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com