
West Pharmaceutical Services (WST) Heads To CPHI Milan As Undervalued Narrative Holds
Event spotlight at CPHI Milan
West Pharmaceutical Services (WST) is set to feature at CPHI Milan 2026, where business development and self injection systems leaders will outline the company’s drug delivery and containment offerings to a global pharmaceutical audience.
Recent trading shows momentum rebuilding in West Pharmaceutical Services. The 30-day share price return of 7.39% and year-to-date share price gain of 34.52% sit alongside a 1-year total shareholder return of 42.81%, even though the 3-year and 5-year total shareholder returns are slightly negative.
Scan beyond West Pharmaceutical Services and compare it with hand picked peers in drug delivery and healthcare exposure using the 33 healthcare AI stocks for fresh ideas in the sector.
Bulls see West Pharmaceutical Services as a quality drug delivery specialist with fresh momentum, while bears flag the weak 3 and 5 year returns. Which story does the current valuation support?
Most Popular Narrative: 8% Undervalued
At a last close of $371.82 against a narrative fair value of $405.38, the current pricing of West Pharmaceutical Services reflects an 8.3% gap that investors are weighing against its mix of high value components and GLP 1 exposure.
The continued growth in GLP-1s, which made up about 10% of West Pharmaceutical Services revenues in the second quarter and are expected by management to grow at a high teens rate for the full year, together with participation in generic GLP-1 launches in multiple countries, could support revenue growth and earnings as higher value elastomer components are supplied into a broader therapy base.
See why 14 investors see West Pharmaceutical Services as 8% undervalued.
Result: Fair Value of $405.38 (UNDERVALUED)
Still, the story can break if high value GLP 1 and biologics demand softens, or if West Vantage margin improvement arrives slower than analysts project.
Find out about the key risks to this West Pharmaceutical Services narrative.
Another View: What Multiples Say About West Pharmaceutical Services
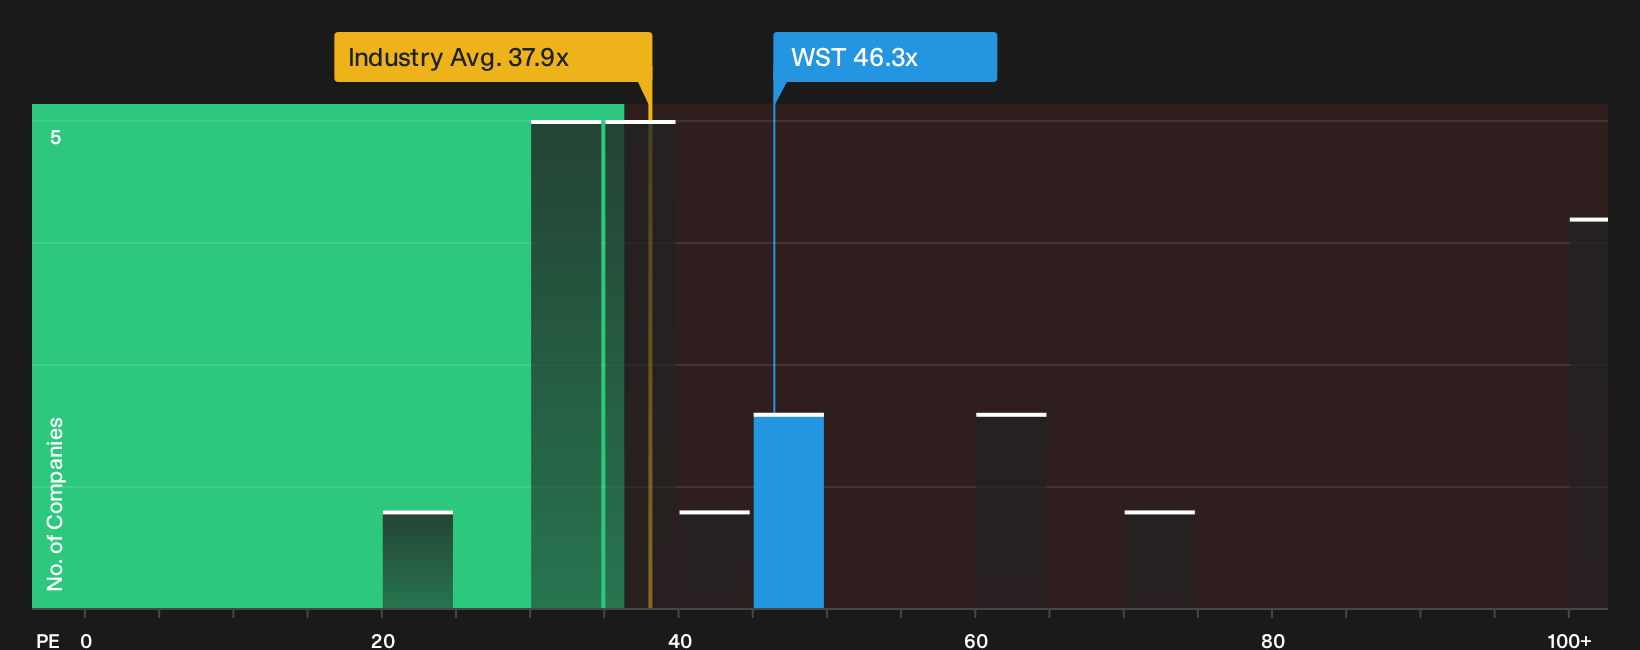
On a simple earnings multiple, West Pharmaceutical Services looks expensive. The stock trades on a P/E of 46.3x, compared with 38.4x for the global Life Sciences group and a peer average of 47.3x, while the fair ratio sits much lower at 24.4x. If the market drifts toward that fair ratio, how comfortable are you with the valuation risk on the way there?
See what the numbers say about this price in more detail in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the split views on West Pharmaceutical Services leave you undecided, move quickly, study the full breakdown, and weigh the upside yourself with 2 key rewards.
Looking for more investment ideas beyond West Pharmaceutical Services?
Do not stop with West Pharmaceutical Services. Use the wider market as your hunting ground and let data driven screeners surface opportunities you might otherwise miss.
- Target more resilient portfolios by scanning companies with stronger balance sheets and fundamentals through the list of solid balance sheet and fundamentals (25 results).
- Hunt for potential mispricings by reviewing a curated set of companies flagged as 32 high quality undervalued stocks.
- Balance growth and cash returns by checking out income focused opportunities among the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com