
Leidos Holdings (LDOS) Taps Booster Motor Supplier For Army Cruise Missile Program
- Leidos Holdings (NYSE: LDOS) selected X-Bow Systems to supply booster rocket motors for the U.S. Army's Low-Cost Cruise Missile Program.
- The collaboration supports U.S. efforts to rebuild the domestic solid rocket motor industrial base tied to precision munitions production.
- The award links Leidos to broader national security initiatives such as the Arsenal of Freedom and other high-profile defense programs.
- The X-Bow booster motor role in the Low-Cost Cruise Missile Program is important, but investors need a wider view of Leidos. We have also spotted 2 warning signs worth knowing about at Leidos Holdings.
For readers interested in more ways to play this theme across defense and infrastructure, the next stop is 92 AI infrastructure stocks.
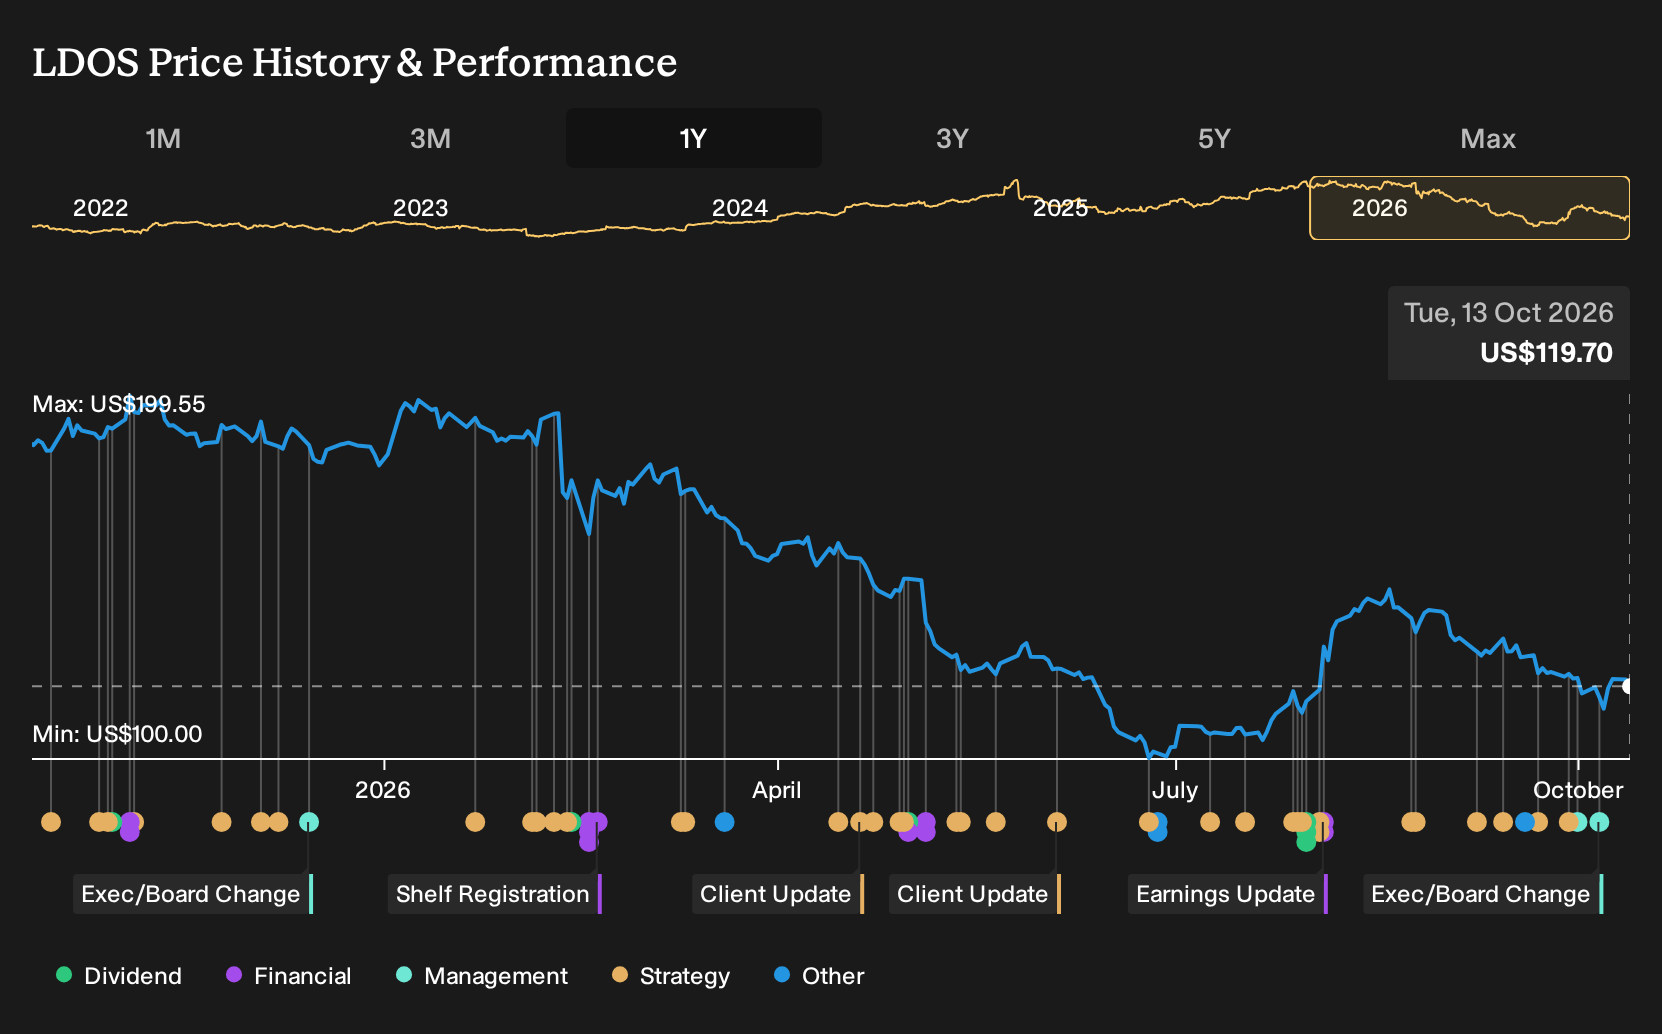
Leidos Holdings is a US professional services contractor that supplies technology and engineering solutions to government and commercial clients, so work on cruise missile components fits alongside its broader role in defense programs and mission systems. With a market cap of about $15.3b, the group operates at a scale that can support long-cycle military initiatives as well as shorter project work.
How the X-Bow deal plugs into the broader Leidos Holdings story
For Leidos Holdings, the X-Bow booster motor award reinforces an existing investment story that leans on defense technology depth, long-cycle hardware programs, and disciplined capital use rather than headline contract wins alone.
The current valuation implies the market is not fully crediting Leidos for its cash generation, low capital intensity near 1 to 1.5% of revenue, and large awarded and visible pipelines in munitions, air defense, AI-enabled platforms, and energy infrastructure...
See how the full story points towards a $158 fair value for Leidos Holdings.
This munitions work fits neatly beside Leidos Holdings' existing commitments in air defense systems and containerized cruise munitions, so it speaks directly to the defense-technology and munitions pillar of the Narrative. What may be underappreciated is that Leidos is acting as an integrator, not a capital-heavy manufacturer, which lines up with the capital-light, cash-generative model analysts already focus on.
The other side of the story is concentration risk. Bigger exposure to U.S. munitions and Arsenal of Freedom initiatives reinforces the same federal funding dependence analysts already flag as a key vulnerability, especially when peers like RTX or General Dynamics are chasing many of the same defense dollars. For an investor, this contract only really makes sense when seen alongside the health-segment margin pressures and energy-infrastructure pipeline that round out the thesis.
News like this is easiest to judge when you already have a clear view of where Leidos Holdings is trying to go and how each new contract either tightens or weakens that longer-term story.
Add Leidos Holdings to your Watchlist and get alerts as these catalysts play out.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com