
Is Coinbase Global (COIN) Cheap Following Citi’s Upgrade And Crypto Growth Call?
Citi’s upgrade of Coinbase Global (COIN) has pulled fresh attention to the stock, after the bank highlighted derivatives, prediction markets and stablecoins as key growth drivers alongside improving regulatory conditions.
Recent trading has been choppy for Coinbase Global, with the share price gaining 8.72% over 90 days and 3.73% over 30 days, yet the year to date share price return is down 23.14% and the 1 year total shareholder return has fallen 46.77%. This suggests that recent positive catalysts are nudging sentiment off a weaker longer term base.
Scan how Coinbase Global compares to other crypto related plays being moved by sentiment shifts in regulation and derivatives by starting with our curated 19 cryptocurrency and blockchain stocks.
After a sharp reset in sentiment and a fresh leg higher on Citi’s call, the real question now is whether Coinbase Global still offers enough upside to compensate for the clear risks.
Most Popular Narrative: 26.5% Undervalued
On the most followed narrative, Coinbase Global screens as undervalued with a fair value of $247.39 against a last close of $181.79, which points to a material gap that bulls see as opportunity rather than anomaly.
I think Coinbase is best understood as a leveraged bet on long-term crypto adoption, rather than a normal operating business with smooth, predictable growth.
What matters most is not whether next year looks clean, but whether crypto becomes a meaningfully larger asset class over time. If that happens, Coinbase should benefit through higher trading activity, higher asset values on the platform, and growth in its custody and subscription businesses.
See why 24 investors see Coinbase Global as 27% undervalued.
According to QuanD, the most widely followed narrative on Simply Wall St, Coinbase Global is framed less as a steady compounder and more as a geared proxy on broader crypto adoption. The fair value estimate of $247.39 is built using a discount rate of 8.07% and assumes that, if the asset class matures, the platform’s earnings power could scale faster than underlying token prices.
The narrative leans on several moving parts. Recent annual revenue of $6.04b is paired with an expectation that Coinbase Global eventually earns a 30% profit margin and trades on a future P/E of 30x, which together support the $247.39 valuation. That is a very different lens to the current fundamentals, where the group reported a net loss of $987.77m and remains unprofitable on trailing numbers.
This story also tries to simplify a complex business model into a single idea. Trading activity, asset prices, institutional custody and subscription products like Coinbase One are treated as different expressions of the same underlying variable, crypto adoption. On that view, if crypto assets broaden out as an investable class, fee streams tied to volumes and assets under custody could justify the narrative fair value even with bumpy results along the way.
There is an important caveat in the narrative itself. QuanD highlights that Coinbase Global is highly cyclical, with revenue and earnings tied to periods of weaker crypto prices and activity, and notes that a straight line discounted cash flow can feel artificial against that backdrop. The bottom line of the thesis is simple. If an investor believes crypto sits meaningfully higher in five to ten years, Coinbase Global looks interesting on this framework. Without that conviction, the cash flow cycle may be too hard to forecast with confidence.
Result: Fair Value of $247.39 (UNDERVALUED)
Still, the narrative can break if crypto adoption stalls or if tougher regulation crimps trading volumes and squeezes Coinbase Global’s fee-driven business model.
Find out about the key risks to this Coinbase Global narrative.
Another View On Coinbase Global’s Valuation
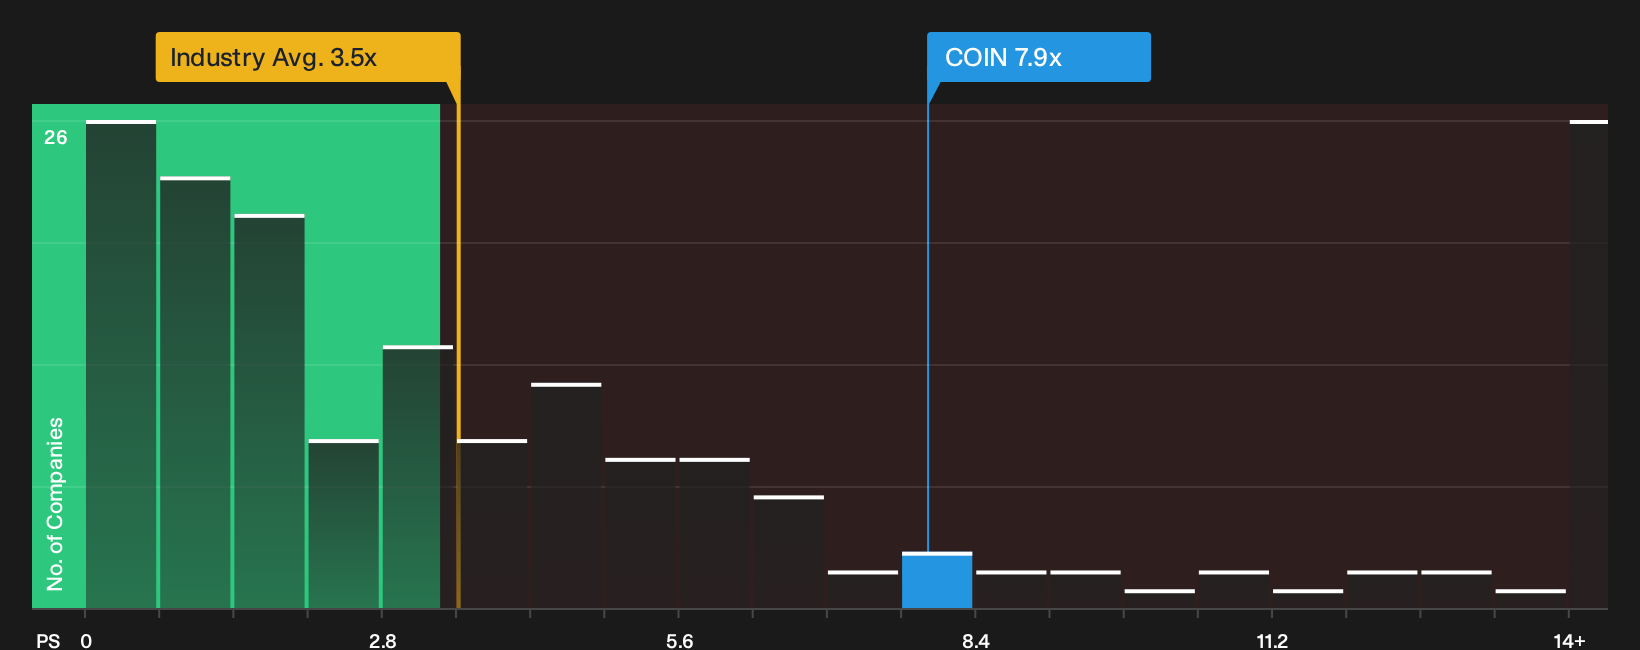
The narrative fair value presents Coinbase Global as 26.5% undervalued, yet the market’s own P/S yardsticks tell a tougher story. At roughly 7.9x sales, the stock trades above the US Capital Markets industry on 3.5x and above a fair ratio of 4.1x, even though it sits below a 9.5x peer average.
That gap means anyone buying Coinbase Global is paying a premium to the broader sector, in the hope that peers are the better comparison set and that revenue quality eventually aligns with that pricing. The key question is whether future fundamentals will justify that richer valuation or leave investors overpaying for the crypto story.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Coinbase Global can make it tempting to wait on the sidelines. Yet the sharper view belongs to those who engage with the figures and sentiment today, compare both sides of the argument, and weigh the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Coinbase Global?
If Coinbase Global feels like only part of your playbook, broaden your watchlist with a few targeted stock ideas sourced directly from the Simply Wall St screener set.
- Hunt for quality at a discount by scanning our 32 high quality undervalued stocks that combine stronger fundamentals with prices that still lag behind financial strength.
- Prioritise resilience and sleep-better-at-night potential through a 32 resilient stocks with low risk scores focused on businesses with sturdier balance sheets and fewer red flags.
- Spot tomorrow’s potential standouts early by reviewing a 20 high quality undiscovered gems that couples solid metrics with limited current attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com