
Genworth Financial (GNW) Stock Looks Pricey As Earnings Face A Higher Bar
Genworth Financial has almost doubled shareholders' money over the past five years, yet the recent pullback puts fresh focus on whether the current share price still lines up with what the insurer is earning. With new capital returns from its mortgage insurance arm and heavier investment in senior care services, the question now is how those moves filter through to the earnings power that underpins Genworth's valuation.
- Genworth's share price is up 99.8% over the last five years. That makes it important to ask whether that long stretch of gains is still supported by the earnings behind the stock.
- The latest results, including US$47 million of net income and capital returned from Enact that funds buybacks and CareScout expansion, can shape expectations for how Genworth converts its businesses into sustainable earnings over time.
- There is a second opinion on Genworth Financial worth weighing. See what analysts think Genworth Financial's shares could be worth.
The issue now is whether the earnings that Genworth Financial generates today are enough to justify where the stock trades compared with the wider insurance industry.
If you want to test the same earnings-based valuation question you are asking of Genworth Financial across a wider group of insurers, run those filters through the 32 resilient stocks with low risk scores.
Does Genworth Financial Look Pricey on Earnings?
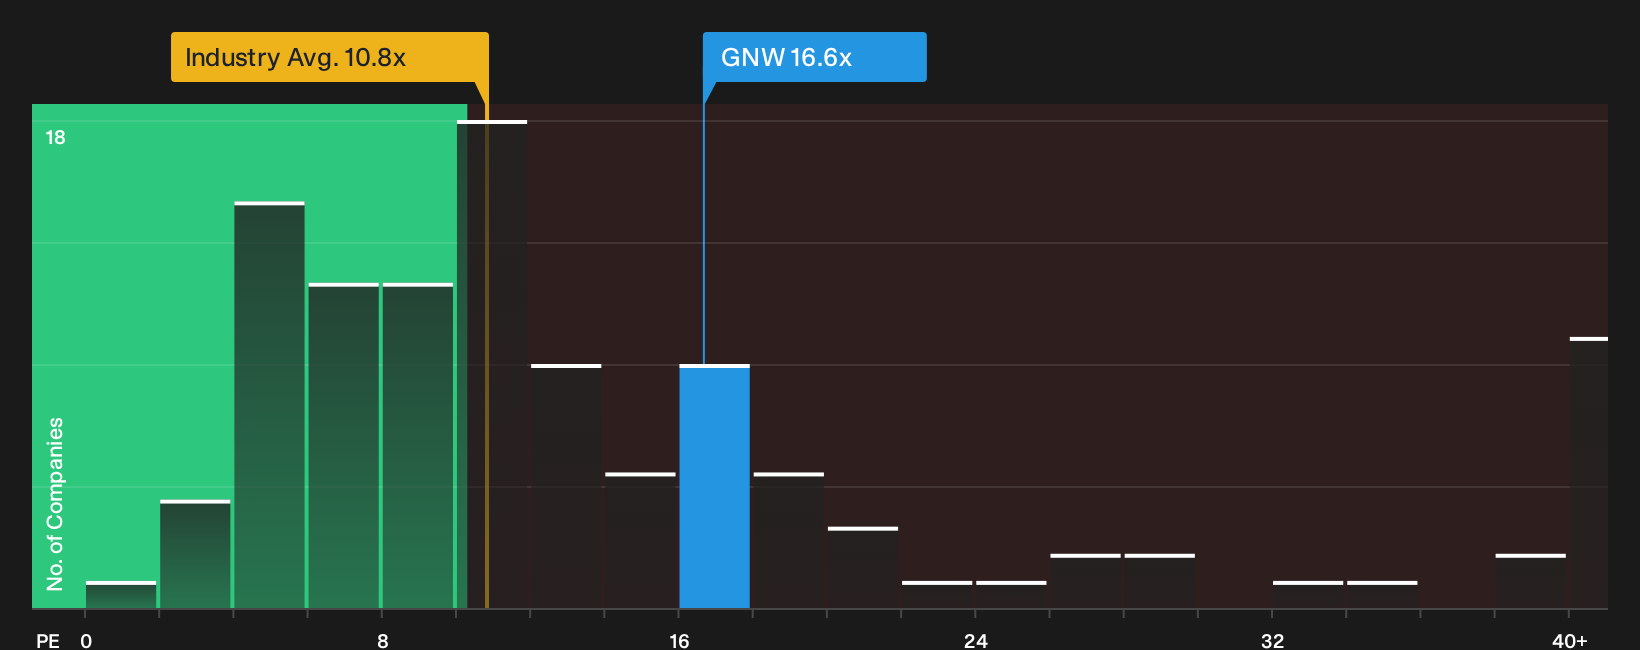
P/E makes sense for Genworth Financial because investors are weighing what they pay today against the earnings being generated from insurance and senior care services. On that yardstick, the stock trades on a P/E of about 16.6x, which is higher than both the broader insurance industry average of roughly 10.8x and a peer group around 9.6x. That gap signals investors are already paying a premium price for each dollar of Genworth Financial earnings.
Because Genworth recently reported US$47 million of quarterly net income and continues to receive capital from Enact for buybacks and CareScout investment, the market appears to be pricing in confidence that these earnings streams hold together. The current P/E level screens as overvalued against the sector, so you need to be comfortable that the mix of mortgage insurance cash flows, senior care expansion and closed block management supports paying that higher multiple. Explore the numbers behind Genworth Financial's P/E valuation.
The Genworth Financial Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Genworth Financial pick up where the P/E question leaves off by spelling out which combinations of future growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than it is today on the market. Each narrative links its number back to a specific view on how Genworth Financial's growth path, profitability and risk profile might evolve, giving you something you can revisit as new information comes through.
A written, number-driven view on Genworth Financial helps you pin down what needs to happen for the US$47 million of recent net income, Enact capital returns and CareScout expansion to line up with today's valuation. It turns loose ideas about those moves into specific assumptions that can be checked against future earnings reports and business updates.
Share your own Narrative for Genworth Financial and set out the assumptions behind your valuation.
One more angle on Genworth Financial that your checklist should not skip
The people setting Genworth Financial's priorities and the way they are rewarded can tilt how those earnings stories play out over time. It is worth checking who they are and how their pay is structured. See who runs Genworth Financial and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com