
3 Inflation Stocks Linked To AI Chips And Oil Prices
Inflation is back in the spotlight, with September CPI expectations tied to higher gasoline and semiconductor costs and a cautious Federal Reserve watching every data point. That mix can punish some stocks while giving others fresh pricing power or revenue support, which is why inflation beneficiaries are getting so much attention. This article walks through 3 stocks from our Energy and Semiconductor Producers screener that are closely linked to these pressures, helping you decide which stories deserve a closer look.
The three stocks highlighted next are just a sample, with the full Energy and Semiconductor Producers screen surfacing 39 more US-listed companies that meet the same size and quality filters and carry their own inflation-linked stories that are not covered here. To identify and analyze the setups that best match your view on gas, oil and chip pricing, head straight to the Energy and Semiconductor Producers (Inflation Beneficiaries) screener.
MACOM Technology Solutions Holdings (MTSI)
Overview: MACOM Technology Solutions Holdings supplies high frequency analog and RF semiconductors that power AI driven data centers, telecom networks and advanced industrial and defense systems worldwide.
Operations: MACOM generates about US$1.16b from designing, developing, manufacturing and marketing semiconductors and modules, with roughly US$395 million from China and US$471 million from the United States.
Market Cap: US$23.40b
MACOM Technology Solutions Holdings sits firmly in the semiconductor side of this inflation beneficiary screen, where AI heavy data traffic and high speed connectivity keep chip demand and pricing in focus.
"Accelerating AI and cloud data center demand for higher speed optical connectivity, including 800G and 1.6T products, 200G and 400G per lane photodetectors and PCIe optical interconnects, supports the view that MACOM Technology Solutions Holdings can expand revenue as these architectures scale through its optical chipset portfolio."
What happens to MACOM’s margins and cash generation depends heavily on how one less visible cost and capacity pressure ultimately plays out.
That cost pressure is only one piece of the puzzle, and the full narrative for MACOM Technology Solutions Holdings shows how MACOM Technology Solutions Holdings could balance pricing, capacity and inflation driven demand shifts.

Greenfire Resources (GFR)
Overview: Greenfire Resources develops and operates oil sands projects in Alberta, giving investors pure upstream exposure to crude-driven inflation pressures.
Operations: Greenfire Resources generates about C$581 million in revenue from oil sands operations in Canada, fully tied to Athabasca bitumen production.
Market Cap: US$1.52b
Greenfire Resources provides direct leverage to oil prices at a time when war-related supply shocks and gasoline-heavy inflation keep energy in focus, backed by Athabasca production guidance and recent capital raises aimed at supporting future output. The key consideration is how funding costs, volume plans and crude-sensitive cash flow interact when they move in different directions.
Those moving parts make Greenfire’s setup especially sensitive to funding costs. That is exactly what the Greenfire Resources financial health report unpacks before those variables really start to bite.
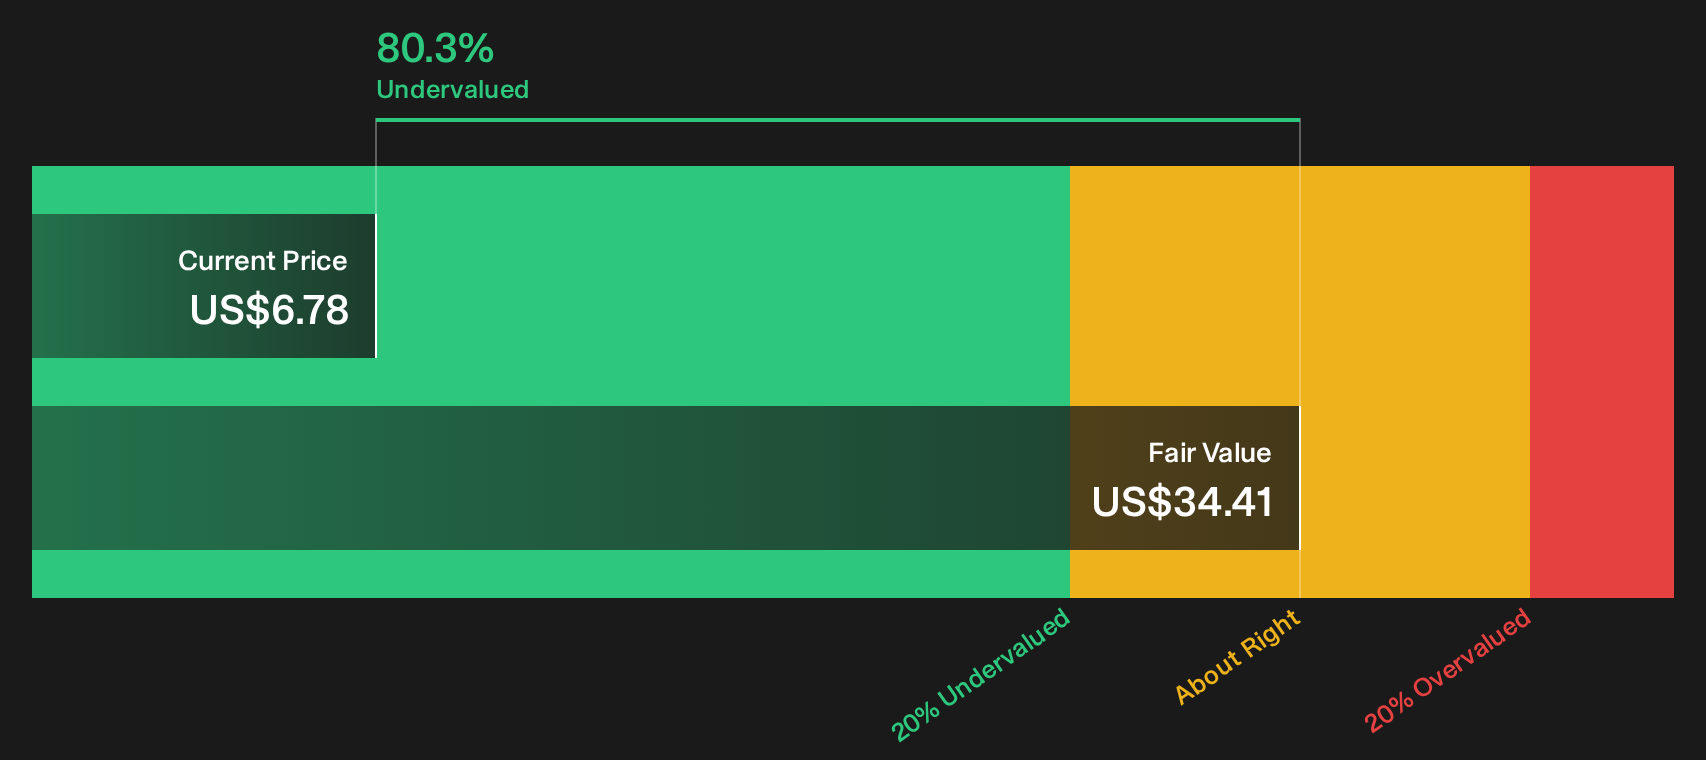
Axcelis Technologies (ACLS)
Overview: Axcelis Technologies designs and services ion implantation tools that chipmakers use to build semiconductor wafers for AI, power and memory production.
Operations: Axcelis Technologies generates about US$866 million from manufacturing semiconductor capital equipment, with reported geographic exposure across Europe and the Asia Pacific.
Market Cap: US$3.94b
Axcelis Technologies is directly connected to the inflation story on chip pricing because its ion implanters are used wherever wafer fabs commit new AI and power-device capital spending.
"Adoption of silicon carbide power devices in electric vehicles and industrial applications remains early stage, with penetration rates and silicon carbide content per vehicle still expected to rise globally and across hybrids, and Axcelis Technologies continuing to point to these applications as highly attractive for future ion implant demand that can support revenue and gross margin over time."
The outlook for Axcelis Technologies margins and order momentum depends on how one fast growing pocket of chip-related investment ultimately develops.
That fast growing pocket of chip investment is exactly what the full narrative for Axcelis Technologies unpacks, highlighting where Axcelis Technologies could accelerate or stall as capex priorities shift.

Seeking Alternatives Before The Crowd?
Fresh breakouts, early momentum and under the radar setups rarely stay quiet for long. Use these focused stock lists before the data gets stale and sentiment shifts.
- Spot underrated balance sheet strength and let the list of solid balance sheet and fundamentals (25 results) point you toward businesses that can better absorb shocks when conditions change fast.
- Scan the 92 AI infrastructure stocks for suppliers and enablers that could benefit from AI-related demand for data and compute capacity.
- Target resilient cash payers and use the 8 dividend fortresses to find income-focused ideas before yield hunters crowd into the same small pool.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com