
Take Two Interactive Software (TTWO) Stock Looks Near Fair Value Following Its 38% 3 Year Run
Take-Two Interactive Software has delivered a mixed share price story lately, which puts the focus squarely on whether the current valuation lines up with the cash the business can generate over time. With the stock pulling back this year after earlier gains, the key issue is how well the present price reflects those underlying cash flows.
- Over the past 3 years the stock has returned 38.3%, which puts real weight on the question of whether that gain is fully supported by the company’s long term cash generation.
- The business model relies heavily on converting game sales and ongoing digital spending into durable free cash flow. This can support valuation if those cash streams remain resilient through cycles in player demand and release timing.
- Prefer to judge Take-Two Interactive Software on sales? See why Take-Two Interactive Software's 5.6x P/S tells a different valuation story.
The issue now is whether Take-Two Interactive Software's current share price is appropriately aligned with its intrinsic value based on Discounted Cash Flow (DCF) analysis of its future cash flows.
If you are weighing whether Take-Two Interactive Software's current valuation is justified by its cash flows, it can help to benchmark that question against 32 high quality undervalued stocks.
Where Does Take-Two Interactive Software Sit on Cash Flow?
The Discounted Cash Flow (DCF) model here projects the cash Take-Two Interactive Software can return to shareholders over time and then brings those figures back to today. Latest twelve month free cash flow sits around $301.8m, and the forecast path assumes that this pool of cash builds over the coming decade rather than shrinks.
Projected annual free cash flow moves into the low single digit billions of $ in later years, which implies rising monetisation from the existing portfolio and pipeline. That kind of curve suits a 2 Stage Free Cash Flow to Equity framework, where the first phase allows for stronger growth before free cash flow levels off into a steadier pattern.
When those projected streams are discounted back and compared with the current share price of $200.32, the DCF output suggests Take-Two Interactive Software's estimated intrinsic value is broadly in line with where the stock trades today. Find out what Take-Two Interactive Software could be worth using our Discounted Cash Flow (DCF) estimate.
The Take-Two Interactive Software Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the DCF puzzle leaves off, by spelling out which paths for Take-Two Interactive Software's growth, margins and earnings would make the stock worth materially more or less than it trades for today. Each narrative ties a fair value to a specific storyline about catalysts and risks so you can track over time which version of events seems to be unfolding on the Community page.
One of the top community narratives on Take-Two Interactive Software: 28% undervalued
"The current excitement around Take-Two Interactive Software Inc. is to do with the upcoming launch, scheduled for November 19, 2026..."
Discover why this Narrative puts Take-Two Interactive Software at 28% undervalued.
One more check on Take-Two Interactive Software that belongs beside the valuation work
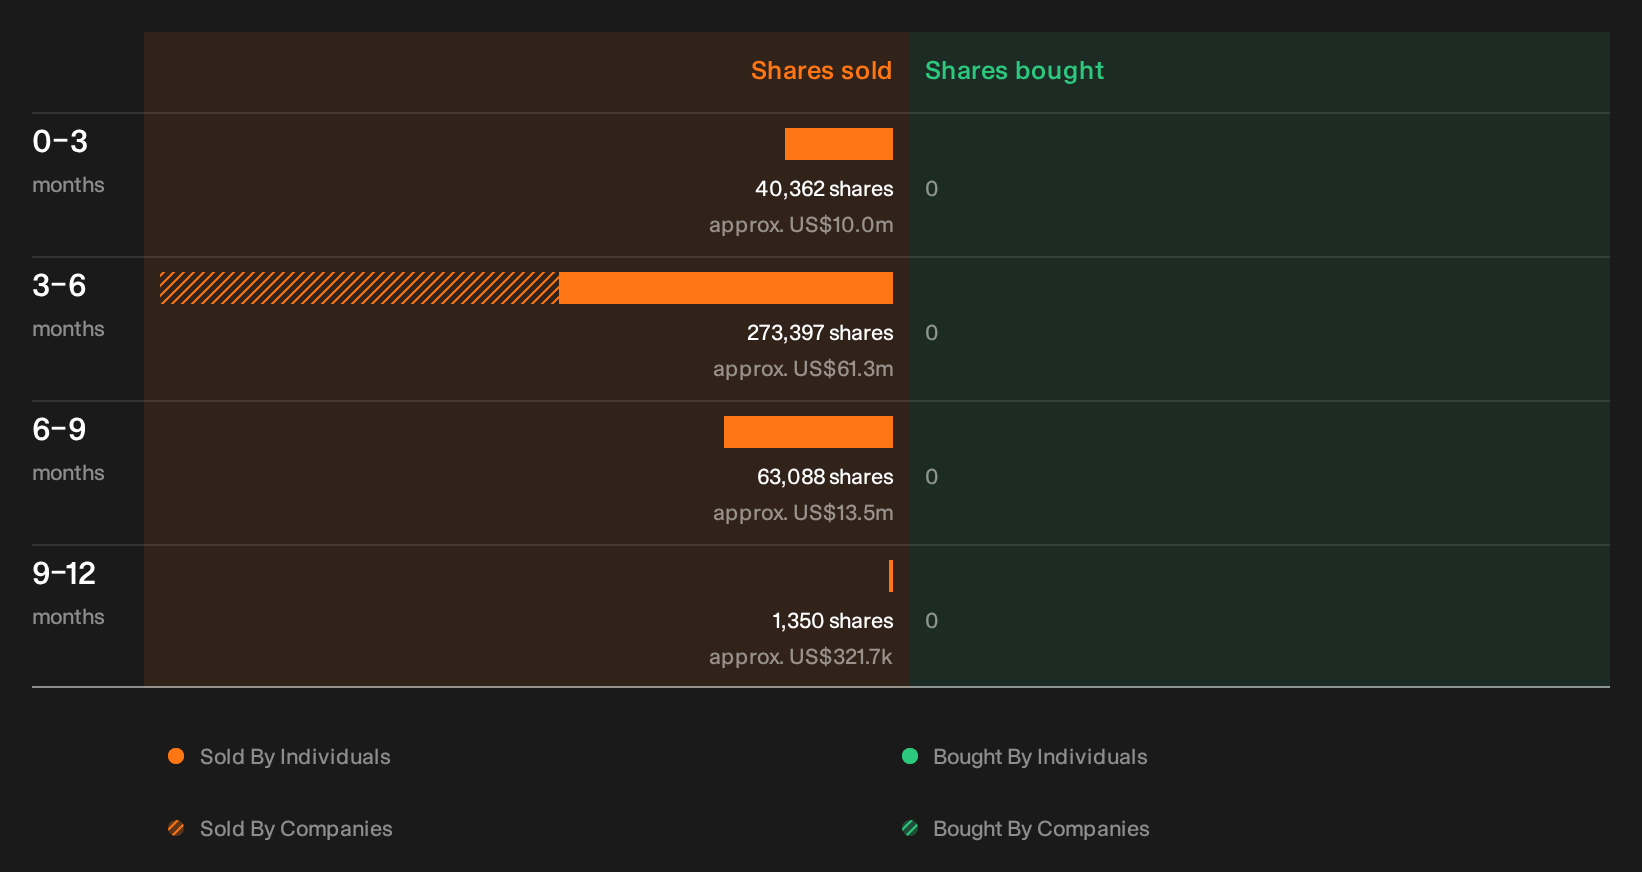
Price and cash flows tell only part of the story. Recent insider transactions have also been flagged by our checks, and the specific sellers, trade sizes and potential meaning are there for you to assess. See the recent insider selling flagged for Take-Two Interactive Software.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com