
Allient (ALNT) Stock Could Be Overvalued Despite Record Margin Results
Allient has been on a powerful multi year run, and with the stock now around US$105, the real question is whether that price still lines up with what the business earns.
- Over the past 3 years the share price has climbed about 2.6x, which puts weight on the idea that Allient’s earnings can justify a much bigger market value than before.
- Recent updates highlighted double digit revenue growth and record gross margins, which can support the case for stronger and potentially more resilient profit streams that matter for any earnings based valuation.
- Your read on Allient is one view; the desks covering it have another. See what analysts think Allient's shares could be worth.
The stock’s next move may depend on whether Allient’s current earnings are strong enough to support today’s valuation or whether recent price gains have moved ahead of the underlying profit power.
If you are weighing Allient against other earnings driven stories, it can help to compare it with companies in similar territory using the 43 power grid technology and infrastructure stocks.
Does Allient Look Pricey on Earnings?
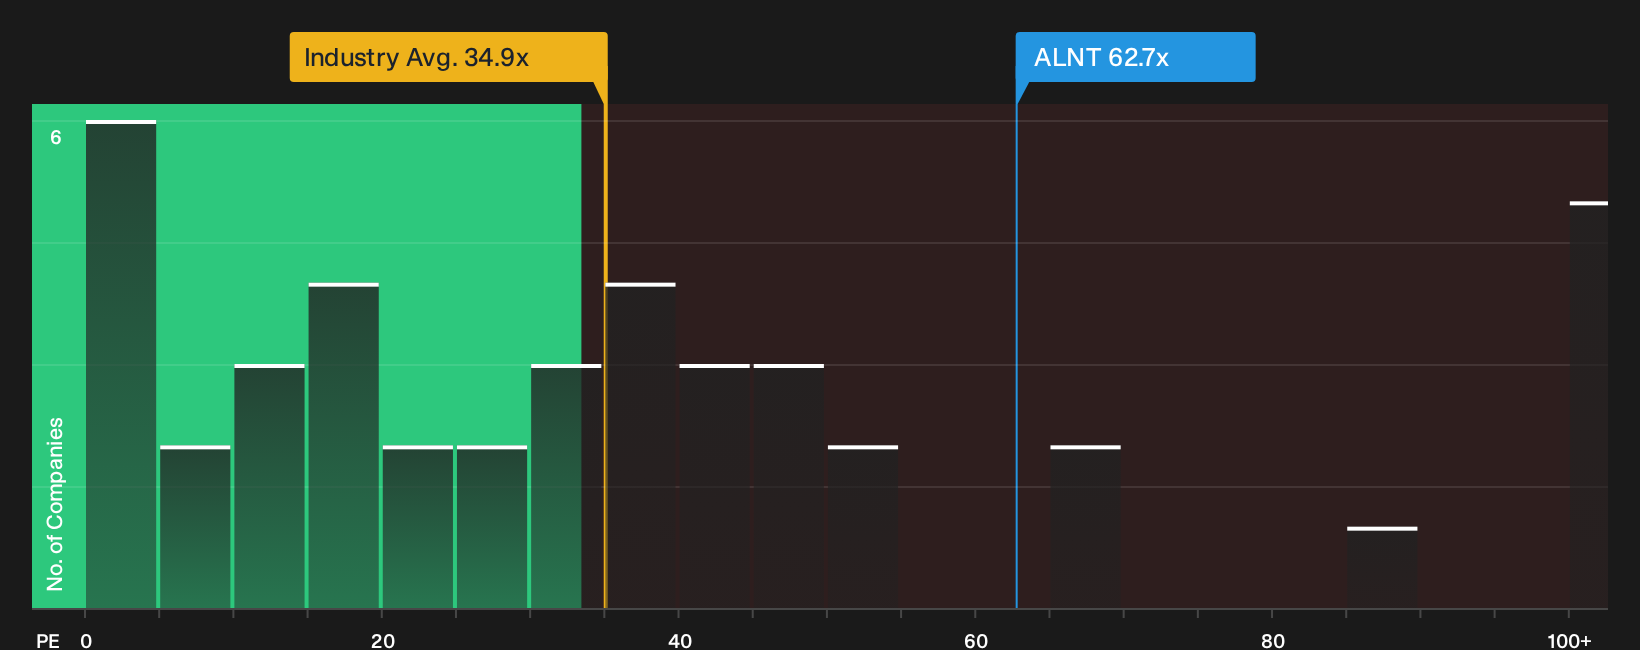
The P/E ratio suits Allient because earnings are a central focus for how investors are already framing the story. At roughly 62.7x, the stock trades on a much richer multiple than the Electrical industry average of about 34.9x and a peer group nearer 32.9x. That kind of gap indicates buyers are currently willing to pay a high price for each dollar of profit the business is reporting.
The fair P/E level that takes Allient’s growth profile, margins, size and risk into account sits well below the current 62.7x, which suggests the shares screen as overvalued on this metric. Because the recent Q2 2026 update flagged 10% revenue growth and record gross margins, the earnings story now has to keep working hard to support a P/E that already reflects a strong narrative. Explore the numbers behind Allient's P/E valuation.
The Allient Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Allient pick up where the valuation question leaves off and explain what kind of future growth, profitability and earnings power would need to hold for the stock to appear meaningfully higher or lower than today’s price based on those assumptions. Rather than a single P/E or model output, each narrative sets out the moving parts behind its view of fair value so you can test those inputs against Allient's reported numbers over time on the Community page.
Bulls and bears on Allient are looking at the same backlog and margin story but reaching very different conclusions about what is already priced in.
Bull case: 11% undervalued
"Market confidence in sustained margin expansion from operational improvement and product mix shift is now underpinned by record Q2 2026 gross margin of 34.9%..."
Discover why this Narrative puts Allient at 11% undervalued.
Bear case: 17% overvalued
"Allient's current valuation, after a share price that has more than doubled over the past year while several independent models suggest the stock trades well above estimated intrinsic value, implies the share price already reflects very optimistic expectations for future cash flow and margin improvement..."
Explore why this Narrative puts Allient at 17% overvalued.
Analyst expectations for Allient could change how you read today's price
Valuation work only tells part of the story, because professional forecasts for Allient over the next few years offer a separate benchmark to compare with the current market view. Explore where analysts expect Allient to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com