
Subsea 7 (OB:SUBC) Could Be 32% Below Fair Value As Ginger Project Moves Ahead
Subsea 7 (OB:SUBC) has been in focus after awarding EnerMech a pre commissioning services contract for the Ginger subsea development offshore Trinidad and Tobago, highlighting ongoing activity in its offshore project portfolio.
Recent trading has been strong, with a 7-day share price return of 7.29% and a 30-day share price gain of 6.96% taking Subsea 7 to NOK344.4. The year to date share price return of 65.58% sits alongside a 1-year total shareholder return of 84.26% and a 5-year total shareholder return of 442.44%. This suggests momentum has been building over both shorter and longer horizons as the project pipeline, including the Ginger award, continues to progress.
Scan for other offshore energy contractors showing similar contract momentum by reviewing the curated list of solid balance sheet and fundamentals (204 results) that match Subsea 7's project driven profile.
After a 65.58% year to date run that puts Subsea 7 at NOK344.4, the market is only modestly below both analyst targets and intrinsic estimates. So where does fair value really sit in that spread?
Most Popular Narrative: 5% Undervalued
Subsea 7's most followed valuation storyline points to a fair value of NOK363.15, sitting above the last close at NOK344.4 and framing the current price as a modest discount based on cash flow and margin assumptions.
The continued robustness of Subsea 7's order intake ($2.5 billion this quarter, 1.4x book-to-bill) and rising backlog (nearly $12 billion) reflect high global demand for offshore oil & gas and brownfield redevelopments, underpinned by persistent growth in energy needs and the push to maximize output from existing infrastructure. This supports revenue visibility and long-term earnings growth.
See why 17 investors see Subsea 7 as 5% undervalued.
Result: Fair Value of NOK363.15 (UNDERVALUED)
Still, the Subsea 7 story can change quickly if the Saipem merger leads to legacy liabilities or if tighter project competition compresses margins and cash generation.
Find out about the key risks to this Subsea 7 narrative.
Another Angle On Subsea 7’s Valuation
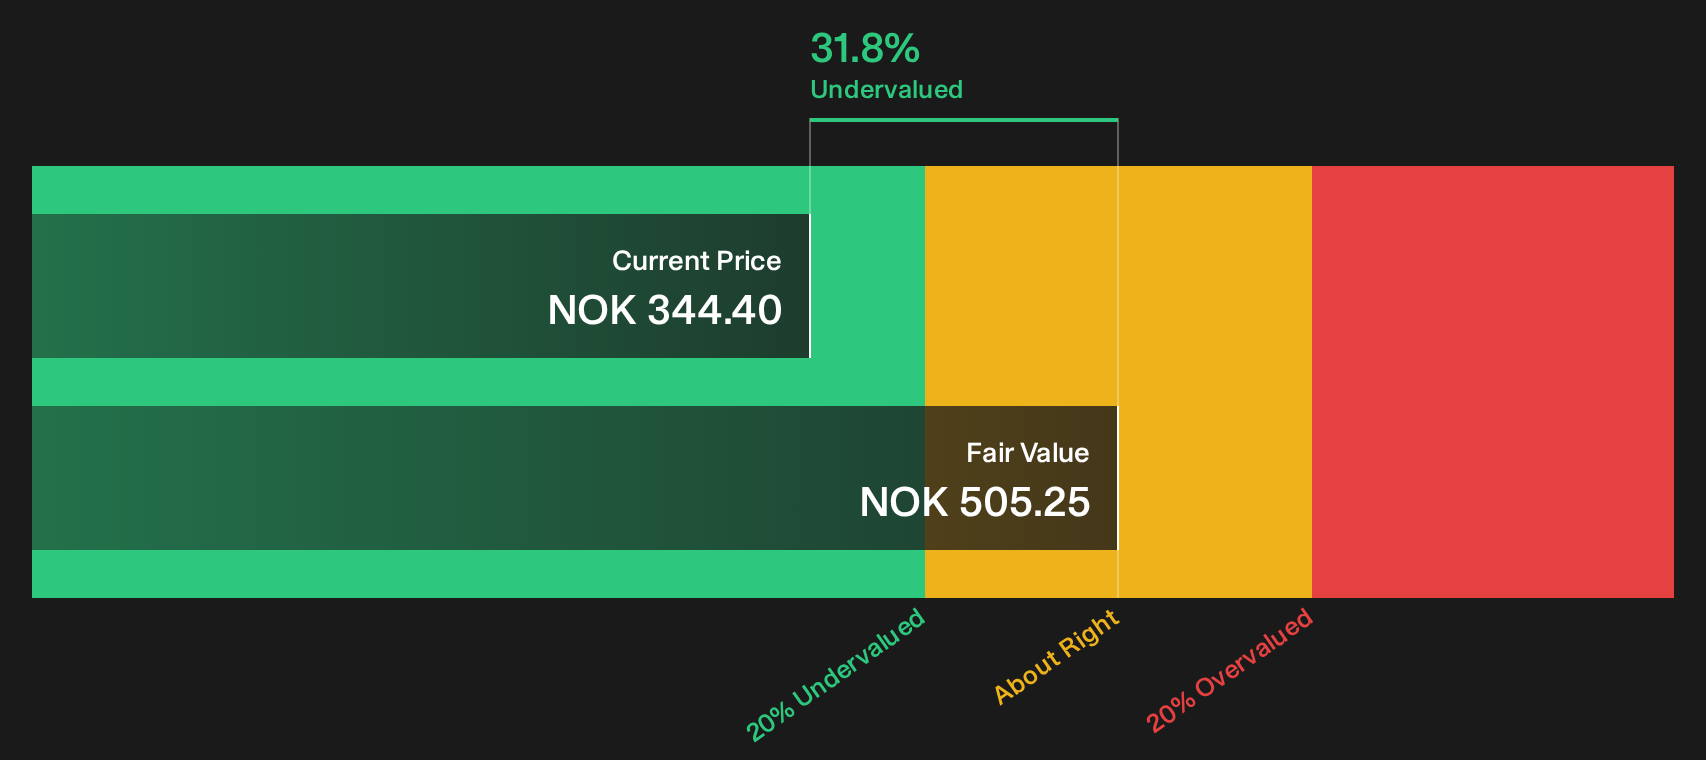
Subsea 7 looks inexpensive on future cash flows in the SWS DCF model, with NOK344.4 trading 31.8% below an estimated fair value of NOK505.25. That points to a lower share price relative to its own projected cash generation. So which signal should you trust more, the narrative fair value or the cash flow math?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on Subsea 7 so far? If you want to move quickly and build your own take on the trade off between concerns and optimism, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Subsea 7?
If Subsea 7 has caught your attention, broaden your watchlist now with a few focused idea lists that could help you decide how to allocate your next kroner.
- Target resilience first and stress test your portfolio against shocks by reviewing a curated mix of 225 resilient stocks with low risk scores that aim to keep volatility in check.
- Look for pricing gaps and put value front and centre by scanning the 185 high quality undervalued stocks that pair fundamental strength with discounted market expectations.
- Build a sturdier core and anchor your holdings with the 223 dividend fortresses that focus on income potential and balance sheet support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com