
What United Parcel Service Buyers Were Betting On
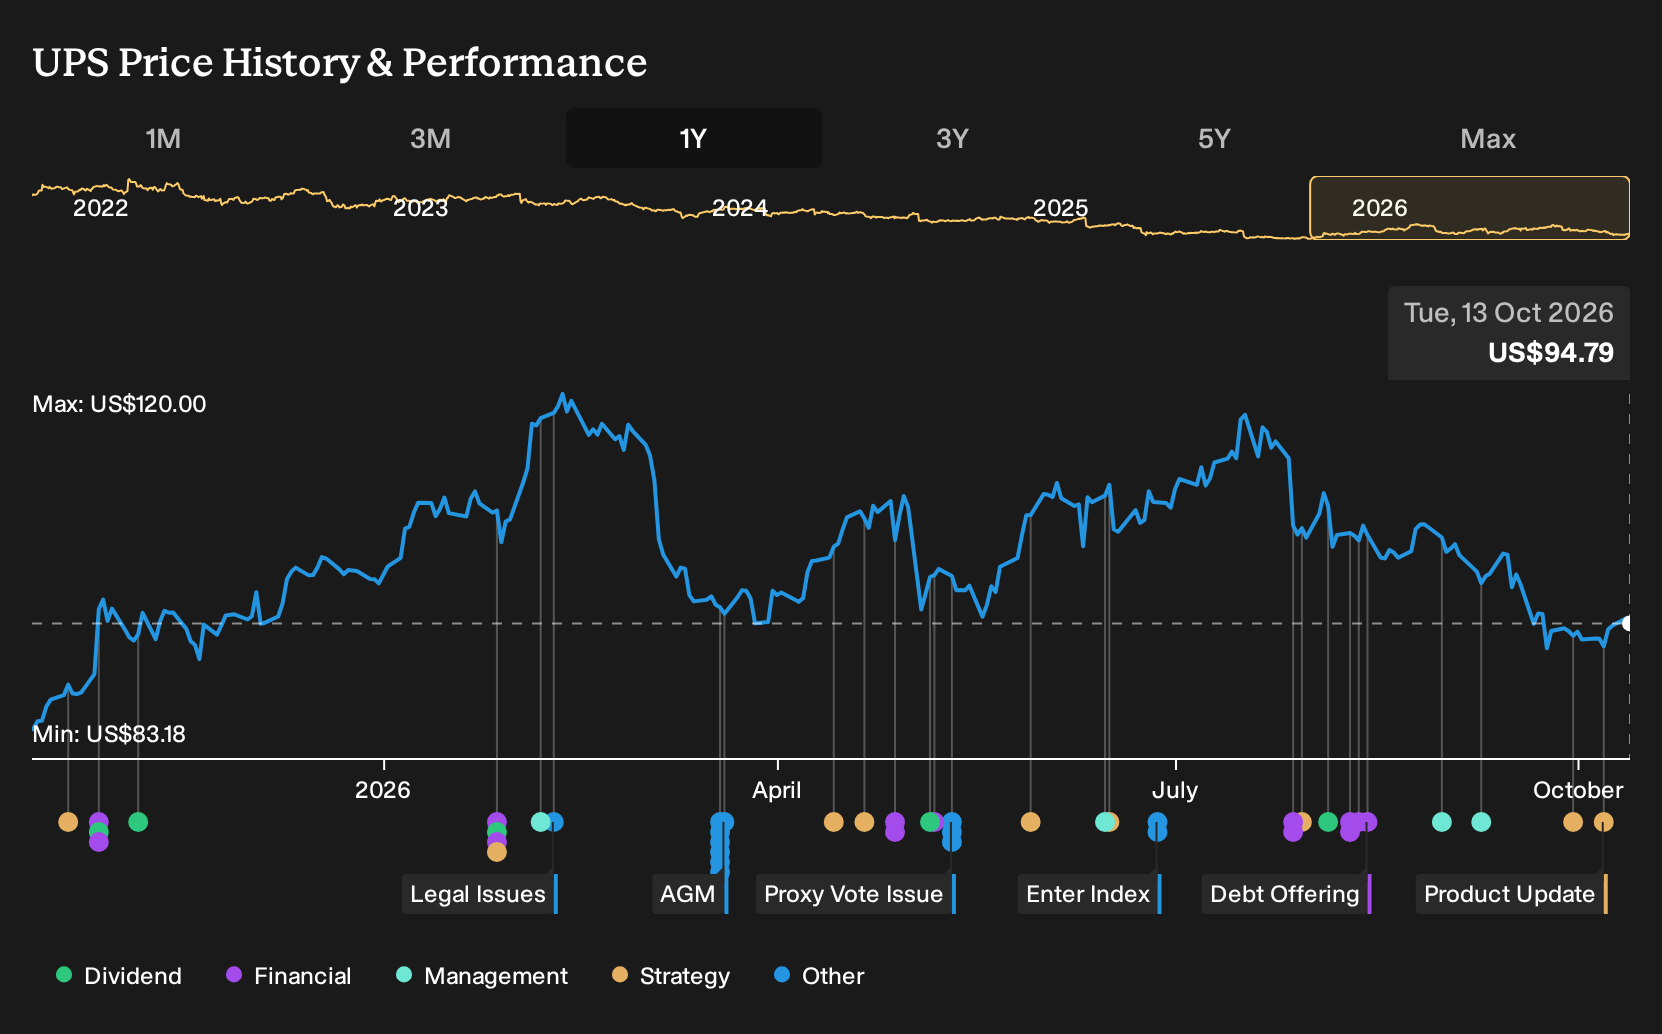
Amazon’s new Supply Chain Services offering gave United Parcel Service investors a clear, concrete shock when the stock dropped sharply on the announcement. Yet the full story for holders looked very different. Holding United Parcel Service over the past year would have returned 20.2%, including dividends. If you were deciding back on 2025-10-13, what would you have needed to believe about UPS’s pivot away from Amazon and into automation and healthcare for that outcome to feel reasonable?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind United Parcel Service. Zero in on 32 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing Up On United Parcel Service
The shares cost US$83.18 at the start of the period, so any view on United Parcel Service had to begin with whether that looked low or full against the two main stories in the market.
The bullish Narrative put Fair Value at US$103. It leaned on the idea that reducing low margin Amazon parcels and pushing automation could support 1.5% annual revenue growth and a 7.5% profit margin over three years.
The bearish view pointed to a Fair Value of US$75. It focused on trade policy uncertainty and higher labor, sustainability, and automation costs that could keep pressure on profitability even if reported margins drifted only modestly higher.
What The Evidence Did To The UPS Argument
Amazon Supply Chain Services entering UPS’s small business backyard directly challenged the bullish assumption that Amazon volumes could quietly run down. At the same time, UPS’s reported figures showed revenue at US$22,221m in Q2 2025 and US$22,834m in Q2 2026, while net income fell from US$1,283m to US$604m and net margin slipped from 6.0% to 2.6%. The evidence cut both ways.
The key lesson is simple. When a story leans on margin repair, track net margin quarter by quarter and compare it with any promised cost savings and mix shifts toward higher yielding segments.
What Today’s UPS Price Already Bakes In
UPS now trades at US$94.79, after returning 20.2% over the past year. The selected Narrative’s Fair Value sits below the current price, which frames today’s level as already pricing in a lot of what automation, healthcare and small business mix shift are supposed to achieve.
The question for you is what must keep going right for that to hold. A buyer at today’s price needs confidence that UPS can deepen higher yielding SMB and healthcare relationships while keeping labor, automation limits and heavy capital commitments from squeezing flexibility.
"The main thing that has to go right is that United Parcel Service continues to shift its mix toward higher yielding SMB, B2B and healthcare customers while using automation, RFID and AI to keep cost per piece in check. The numbers imply the current United Parcel Service share price already reflects a balanced view of these mix, technology and capital allocation trends, consistent with a fairly valued and bullish stance."
The price and this Narrative do not agree. → Uncover what this Narrative says United Parcel Service is actually worth
Looking Beyond UPS’s Sorting Belts
UPS is rebuilding its mix around higher yielding parcels and automation. Investors can also examine another piece of the delivery puzzle.
Those parcels do not move only through brown trucks. They increasingly arrive through on demand couriers handling food, groceries and local retail orders.
One large platform runs that courier network, matching riders with merchants and drop off points. It focuses on software, routing and payment flows instead of owning fleets.
That creates a different freight story to UPS, centred on local logistics and customer data. The unresolved issue is how much of each delivery dollar such platforms can keep.
That argument has a Narrative and a number behind it. → See the company one Narrative values 63% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com