
Veeco Instruments (VECO) Pulled Back Sharply, Is It Cheap Or Still Expensive?
Veeco Instruments (VECO) has moved without a clear single headline to point to, which shifts attention back to its fundamentals, recent share performance, and where the business currently sits in the semiconductor equipment cycle.
The recent pullback, with a 7 day share price return down 12.3% and a 90 day share price retreat of 14.29%, comes against a much stronger backdrop. Veeco Instruments still shows a year to date share price return of 59.86% and a 1 year total shareholder return of 75.55%, indicating that while momentum has cooled, longer term holders remain well ahead.
Scan beyond Veeco Instruments and size up other semiconductor equipment players showing fresh momentum with a curated set of 92 AI infrastructure stocks in one place.
Veeco Instruments now trades well below the average analyst target after a sharp pullback. The key tension is whether that discount reflects opportunity or serves as a fair warning on risk.
Most Popular Narrative: 20.4% Undervalued
Veeco Instruments closed at $48.82 against a narrative fair value of $61.33, which frames the recent pullback as a gap between booked projects and what the market is currently willing to pay.
Ongoing AI and high performance computing build outs are feeding multi year demand for Veeco Instruments annealing and advanced packaging tools, with management pointing to served markets that they size at about US$1.3b for annealing and about US$1b for advanced packaging by 2030, which directly targets future equipment revenue and earnings.
See why 10 investors see Veeco Instruments as 20% undervalued.
Result: Fair Value of $61.33 (UNDERVALUED)
Still, the Veeco Instruments story can change quickly if export controls delay more shipments or if the Axcelis merger introduces integration and cost surprises.
Find out about the key risks to this Veeco Instruments narrative.
Another View: Veeco Instruments Looks Expensive On Earnings
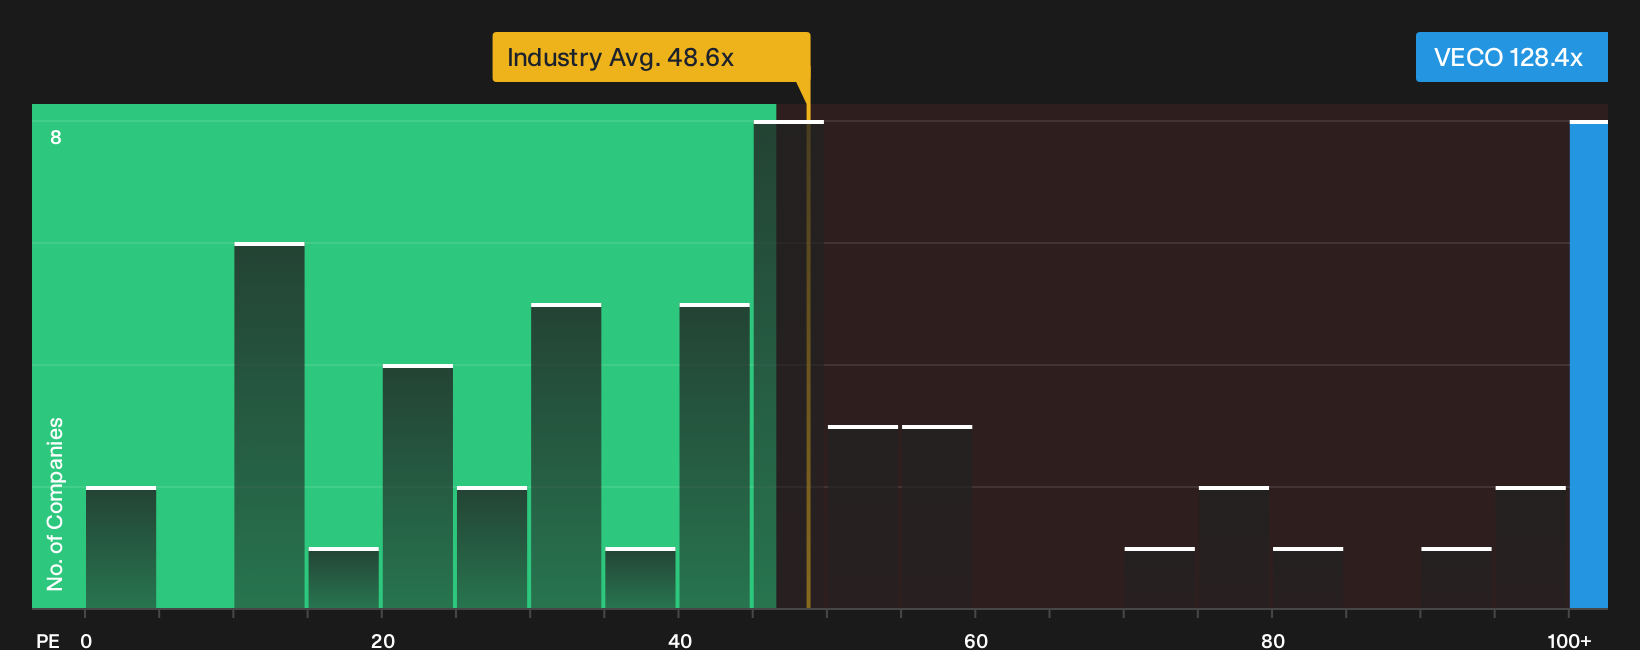
That 20.4% narrative discount presents Veeco Instruments as undervalued, yet its P/E of 128.4x suggests something different. The fair ratio is 65x, while the US Semiconductor industry averages 48x and peers are around 30.9x. Is this simply growth optimism, or valuation risk building up?
See what the numbers indicate about this price gap in our valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Veeco Instruments can be confusing, so move quickly, review the full data set yourself, and weigh both 2 key rewards and 3 important warning signs
Looking for more Veeco Instruments investment ideas?
Veeco Instruments highlights how quickly a story can shift. Do not stop here. Broaden your watchlist now and give yourself more options before the next move.
- Target sturdier balance sheets and steadier financial profiles by scanning a focused list of solid balance sheet and fundamentals (25 results) that keeps risk in clear view.
- Stack potential value on your side by searching through a curated pool of 32 high quality undervalued stocks that combine quality metrics with appealing prices.
- Hunt for future market favorites by tracking a tight set of 20 high quality undiscovered gems that most investors are still overlooking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com