
Whitbread (LSE:WTB) Could Be 5% Undervalued Following Dividend News And Corvex Pressure
Dividend confirmation and activist pressure put Whitbread in focus
Whitbread (LSE:WTB) has moved into the spotlight after confirming its interim dividend, reporting half year results, and facing fresh pressure from activist investor Corvex over capital allocation and board representation.
Recent price action has been firm, with a 9.25% 1 month share price return and a 9.57% 3 month share price return as investors react to Whitbread’s half year figures, dividend confirmation and Corvex’s challenge on capital spending and board representation, although the 1 year total shareholder return is still down 18.16%.
Scan how Whitbread compares on balance sheet strength and fundamentals against a curated list of solid balance sheet and fundamentals (9 results) that are also in the market’s spotlight after fresh news and capital allocation debates.
Whitbread shares have bounced on the dividend and Corvex headlines, yet the 1-year return is still in double-digit decline. Is this a moment to step in, or a reason to hold fire until the valuation resets?
Most Popular Narrative: 5% Undervalued
Against a last close of £25.64, the most followed narrative pegs Whitbread’s fair value at about £26.86, which implies modest upside once investors factor in property recycling, German expansion and the extended efficiency programme.
Whitbread's plan to recycle £1.5b of freehold property and shift towards a capital lighter hotel estate is intended to reduce net capex to £200 to £250m a year. This can support future earnings by directing more cash towards projects that aim to lift returns and net margins. The extended Accelerating Growth Plan, which converts 197 remaining branded restaurants into hotel capacity, adds around 3,000 new extension rooms and targets about £100m of incremental profit before tax by FY31 on £660m of spend, is set up to support revenue growth and higher return on capital.
See why 30 investors see Whitbread as 5% undervalued.
Result: Fair Value of £26.86 (UNDERVALUED)
Still, higher UK business rates and the increased fixed lease commitments from £1.5b of property recycling could unsettle the Whitbread narrative if trading conditions soften.
Find out about the key risks to this Whitbread narrative.
Another View On Whitbread’s Value
There is a very different read across from the SWS DCF model. On that measure, Whitbread at £25.64 is trading above an estimated future cash flow value of £18.91, which points to the shares looking expensive rather than modestly undervalued. Which lens do you trust more when cash flows and earnings disagree?
Our DCF work lets you see exactly how sensitive that view is to small shifts in forecasts and discount rates, and where the biggest pressure points might be for Whitbread’s long term valuation story. Look into how the SWS DCF model arrives at its fair value.
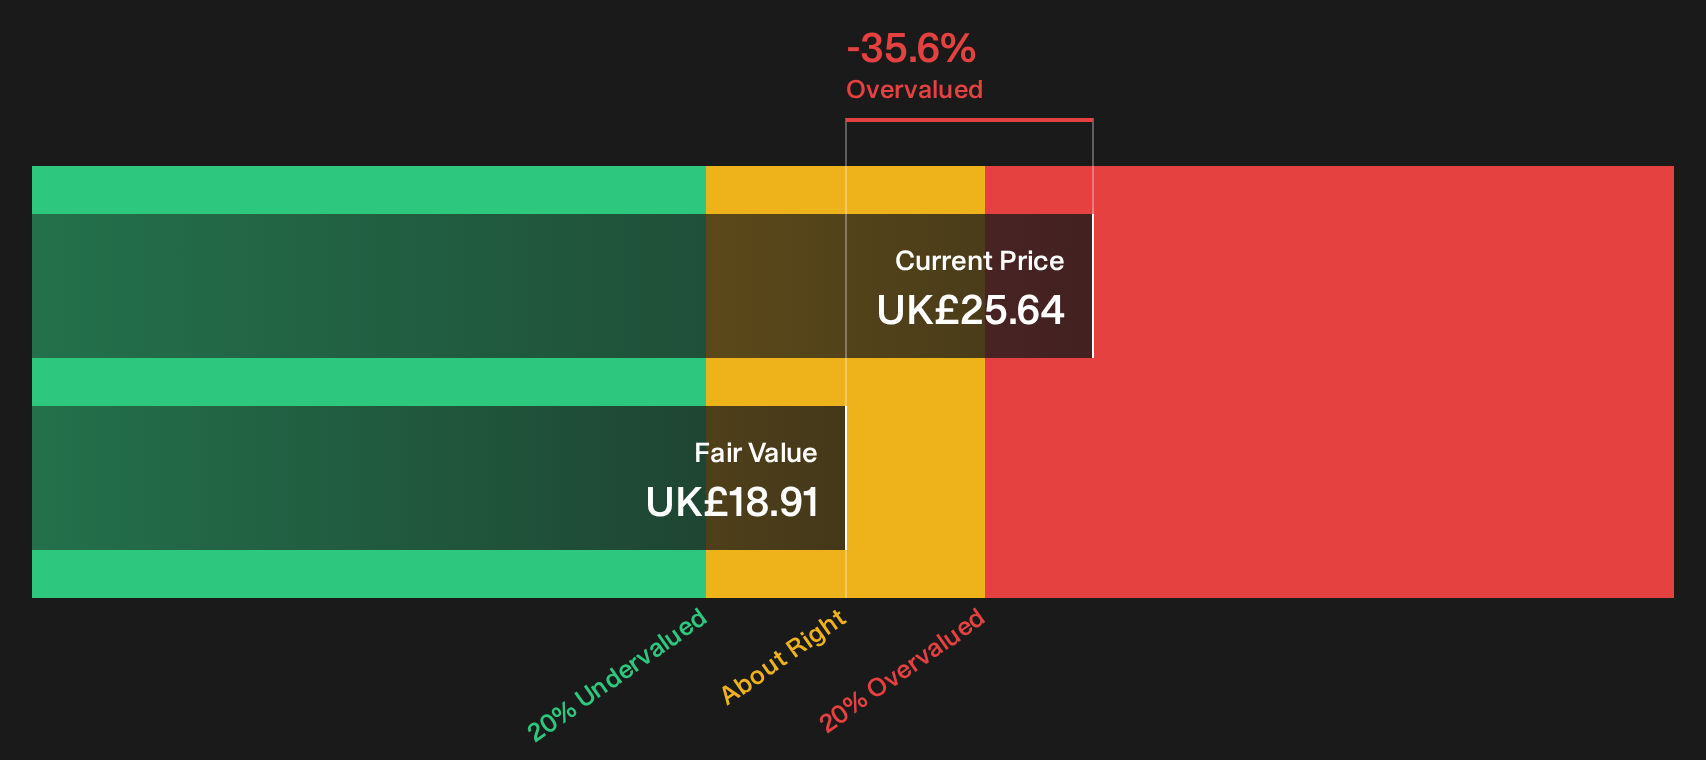
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Whitbread for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 8 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Whitbread can feel confusing, so move quickly to review both the upside and the downside and build your own stance using the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Whitbread?
Do not stop at Whitbread. Use the Simply Wall Street screener to uncover other opportunities that fit your risk, income, and value preferences in minutes.
- Target steadier potential returns by lining up companies with stronger balance sheets and fundamentals through the list of solid balance sheet and fundamentals (9 results).
- Hunt for mispriced opportunities by scanning a 8 high quality undervalued stocks that may trade below their estimated worth.
- Build an income focused watchlist by zeroing in on 2 dividend fortresses that aim to combine yield with resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com