
Following $400 Million AI Capacity Push, Is TTM Technologies (TTMI) Still Undervalued?
TTM Technologies (TTMI) has put a fresh US$400 million on the table to scale advanced interconnect production in China and Malaysia, targeting AI data center demand and testing investor appetite for heavier capital spending.
The fresh capex headline lands after a choppy run for TTM Technologies, with a 1-day share price return of 5.23% to US$116.10 coming on the heels of a 7-day share price decline of 12.52% and a 90-day slide of 19.16% that followed sector selling and concern about higher leverage from the Epiq Solutions acquisition. Yet the broader picture remains strong, with a year-to-date share price return of 64.42% and a 1-year total shareholder return of 110.14%, while the 3-year and 5-year total shareholder returns are both extremely high, signalling powerful long-term momentum even as recent moves reflect investors recalibrating growth potential against rising balance sheet and execution risk.
Scan how TTM Technologies fits into the broader AI buildout, and compare it with a curated group of 92 AI infrastructure stocks powering similar data center and interconnect demand.
After a 110.14% 1-year return and a sharp pullback around the fresh US$400 million capex plan, TTM Technologies now raises a simple question: Is meaningful upside still ahead, or has most of it already been priced in?
Most Popular Narrative: 43% Undervalued
On the most followed view, TTM Technologies screens as materially below a fair value of $203 compared with the last close at $116.10, which puts the current price up against very aggressive growth and margin assumptions embedded in that narrative.
Ongoing expansion into higher-value engineered solutions and advanced manufacturing capabilities, particularly through new capacity in Penang and Syracuse and through product mix shifts, increases pricing power and drives gross margin improvements over time, enhancing net margin profile. Growing industry-wide emphasis on supply chain resiliency and secure domestic sourcing is likely to shift PCB market share toward North American providers like TTM, potentially leading to persistent outperformance in revenue and free cash flow as customers prioritize domestic production.
See why 44 investors see TTM Technologies as 43% undervalued.
Result: Fair Value of $203 (UNDERVALUED)
Still, that upbeat TTM Technologies story collides with real friction, from slower Penang ramp effects on margins to the risk of underused, high cost U.S. capacity.
Find out about the key risks to this TTM Technologies narrative.
Another View: TTM Technologies Looks Rich On Earnings Multiple
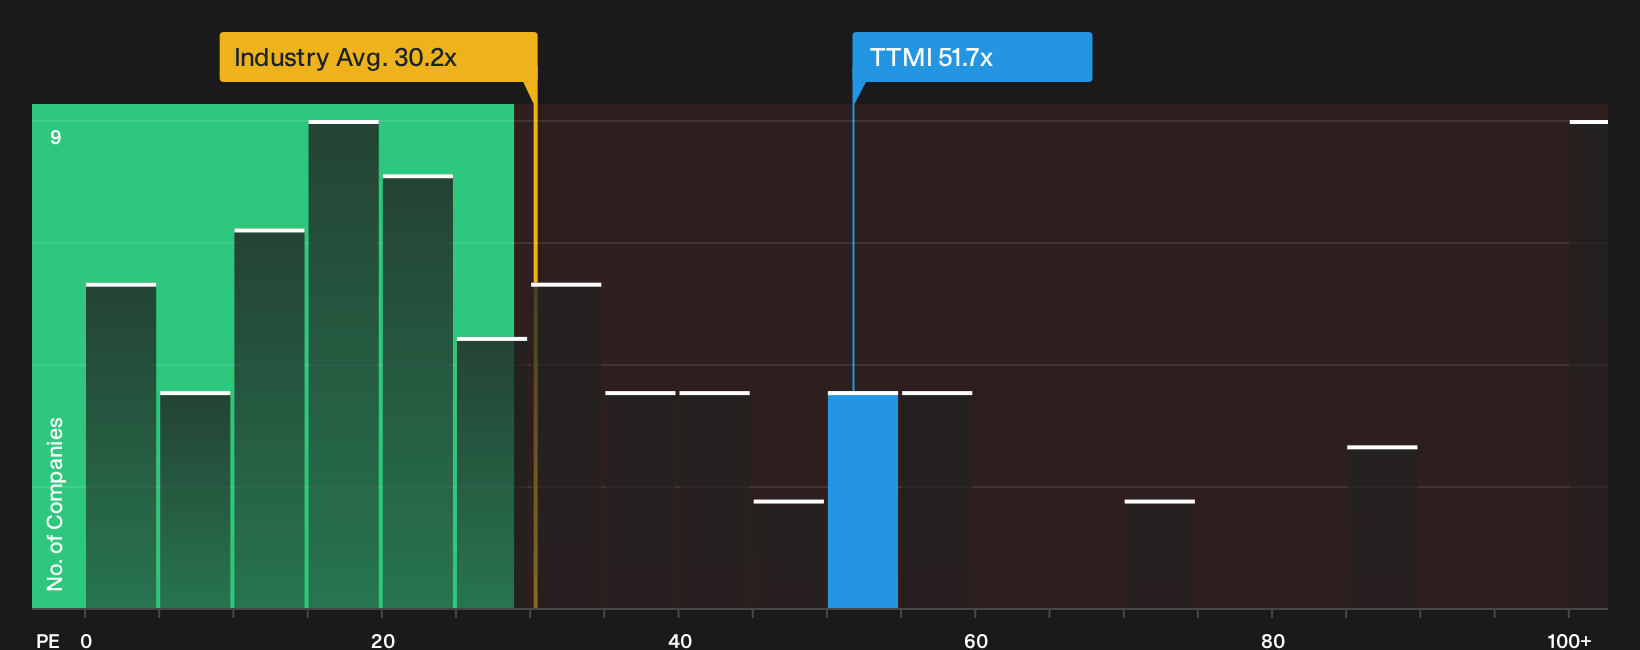
A different lens on TTM Technologies comes from its current P/E of 51.7x. That is higher than both the US Electronic industry at 30.2x and the peer average at 34.6x, even though the fair ratio points closer to 65.1x as a level the market could move toward over time.
This gap means anyone buying today is paying a premium compared with the sector and peers, while still not paying as much as the fair ratio implies. The question is whether you see that as a stretch worth paying for or a margin of safety that is thinner than it looks.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out TTM Technologies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The debate around TTM Technologies is clear enough. With both risks on one side and clear potential rewards on the other, move fast, review the underlying data, and weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond TTM Technologies?
If you stop at TTM Technologies, you only see part of the picture. Broaden your watchlist now, or risk missing opportunities sitting in plain sight.
- Target potential future breakthroughs at an earlier stage by scanning the 11 elite penny stocks with strong financials, which pair smaller company size with relatively stronger financial underpinnings than typical speculative trades.
- Prioritise value and quality together by reviewing the 32 high quality undervalued stocks, which focus on companies with solid cash flows and balance sheets that many investors may overlook.
- Seek to reduce portfolio volatility by focusing on the 32 resilient stocks with low risk scores, designed to help keep downside risk in check while you search for upside potential.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com