
Enerflex Stock Gets Data Center Power Contract Boost
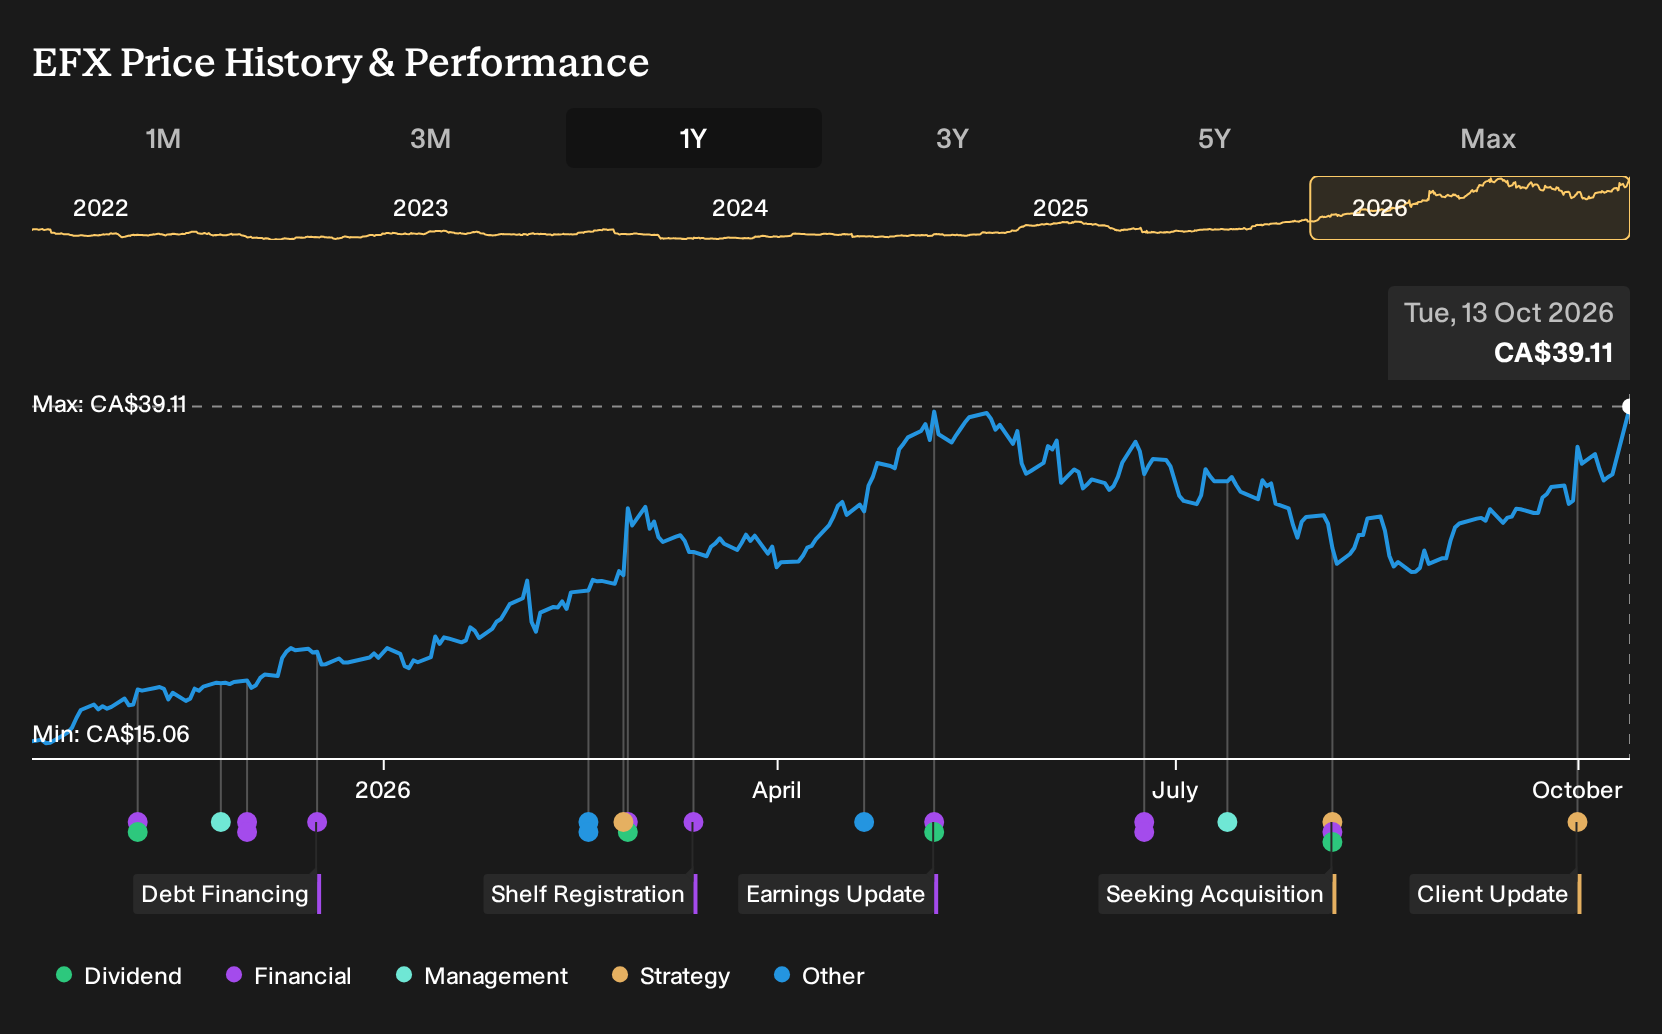
- Enerflex announced in October 2026 that it had secured major Engineered Systems contracts for over 1 gigawatt of low emission behind the meter natural gas power units for large North American data center projects, lifting its total behind the meter generation backlog to more than 1.75 gigawatts with deliveries running through 2028.
- The expanded backlog ties directly into Enerflex’s planned US$100 million of Engineered Systems facility and capability spending, which aims to lift revenue capacity while opening higher value commissioning, installation, digital monitoring, and after market service opportunities over the full lifecycle of these data center power assets.
- The next area of focus is how Enerflex’s expanded low emission data center power backlog could reshape its investment narrative around growth and services.
Enerflex Investment Narrative Recap
To own Enerflex, you need to believe the energy infrastructure story still has legs and that natural gas backed power remains a viable bridge for data centers and global projects. The recent data center awards extend revenue visibility in Engineered Systems, which can help while margins normalize and net profit margins remain relatively low at 2.1%.
The near term swing factor is execution on this much larger backlog and on the US$100 million facility expansion, without creating cost overruns or underused capacity if conditions soften. The biggest risk is still concentration in traditional gas infrastructure and a young management team, especially if energy transition policies tighten faster than Enerflex’s offering evolves.
The October 13 award for over 1 gigawatt of low emission behind the meter natural gas power units for a North American data center development looks central to that thesis. It lifts the behind the meter backlog to more than 1.75 gigawatts, with deliveries stretching to 2028 and anchored in Enerflex’s North American manufacturing footprint.
This contract also plugs directly into the planned US$100 million of ES facility and capability spending, including the previously guided US$15 million in 2026 and about US$85 million mostly in 2027. Execution quality here feeds into the key catalysts investors watch, such as growth in higher margin after market services tied to ReliaCore Asset Performance Management and the stability of recurring infrastructure style revenue streams.
Enerflex's narrative projects $3.1b revenue and $270.0 million earnings by 2029. This implies 6.7% yearly revenue growth and an earnings increase of about 5 times from $53.0 million today.
Uncover why Enerflex's fair value indicates a 20% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
For Enerflex, the wild card in the alternate narrative is execution risk on that expanding data center and AI power push. The most cautious analysts were only penciling in flat revenue to about $2.7b and earnings of $204.1 million by 2029. Those forecasts came before this backlog news, so views on the story could shift.
Explore 3 other Enerflex fair value estimates, including one that suggests it could be worth just CA$42.00.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Enerflex research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Enerflex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Enerflex's overall financial health at a glance.
Looking for more Enerflex style investment ideas?
If Enerflex has sharpened your interest in energy infrastructure and long-horizon projects, broaden your watchlist by using the Simply Wall St Screener to spot other stocks that fit your approach.
- If resilience matters most to you, start with a 8 resilient stocks with low risk scores that aims to keep risk scores in check while still offering equity upside.
- If you want strong finances backing the story, focus on a curated list of solid balance sheet and fundamentals (8 results) that can support long term capital plans and downturns.
- If you prefer underfollowed potential, survey a 10 high quality undiscovered gems that combines quality fundamentals with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com