
Admiral Group (LSE:ADM) Shares Climbed, So What Is Driving Attention Now?
Admiral Group (LSE:ADM) has begun a sizeable share repurchase programme that could retire or reallocate up to 10% of its issued share capital. This gives investors a fresh angle on the insurer’s capital return approach.
Recent sector tailwinds have helped Admiral Group’s share price, with a 1-day share price return of 2.18% and a year-to-date share price return of 19.12%, alongside wider gains in banking and insurance as investors reassess interest rate risks.
Scan other insurers and financials benefiting from the same backdrop as Admiral Group by checking our hand picked list of solid balance sheet and fundamentals (9 results) for comparison.
After a near 20% year to date climb and a fresh buyback in motion, the question for Admiral Group now is whether meaningful upside still lies ahead or whether the easy gains have already passed.
Most Popular Narrative: 6% Undervalued
Against a last close of £37.50, the most followed narrative pegs Admiral Group’s fair value at £40.05, which implies modest upside once future earnings, margins and capital returns are taken into account.
Investor optimism appears to be driven by Admiral's significant investment in advanced data platforms, machine learning, and generative AI, which have already led to measurable efficiency gains and are expected to deliver further operating leverage and improved cost ratios, potentially increasing net margins going forward.
Expectations around Admiral's strong position in the growing market for usage-based and personalized insurance products (such as telematics and EV policies), combined with the expansion of digital distribution, are fueling projections for continued customer growth and higher policy sales per customer, supporting revenue growth.
See why 35 investors see Admiral Group as 6% undervalued.
Result: Fair Value of £40.05 (UNDERVALUED)
Still, the narrative can crack if Admiral Group struggles to replicate UK profitability in Europe, or if new tech driven competitors squeeze motor pricing power faster than expected.
Find out about the key risks to this Admiral Group narrative.
Another View: Admiral Group Through Market Multiples
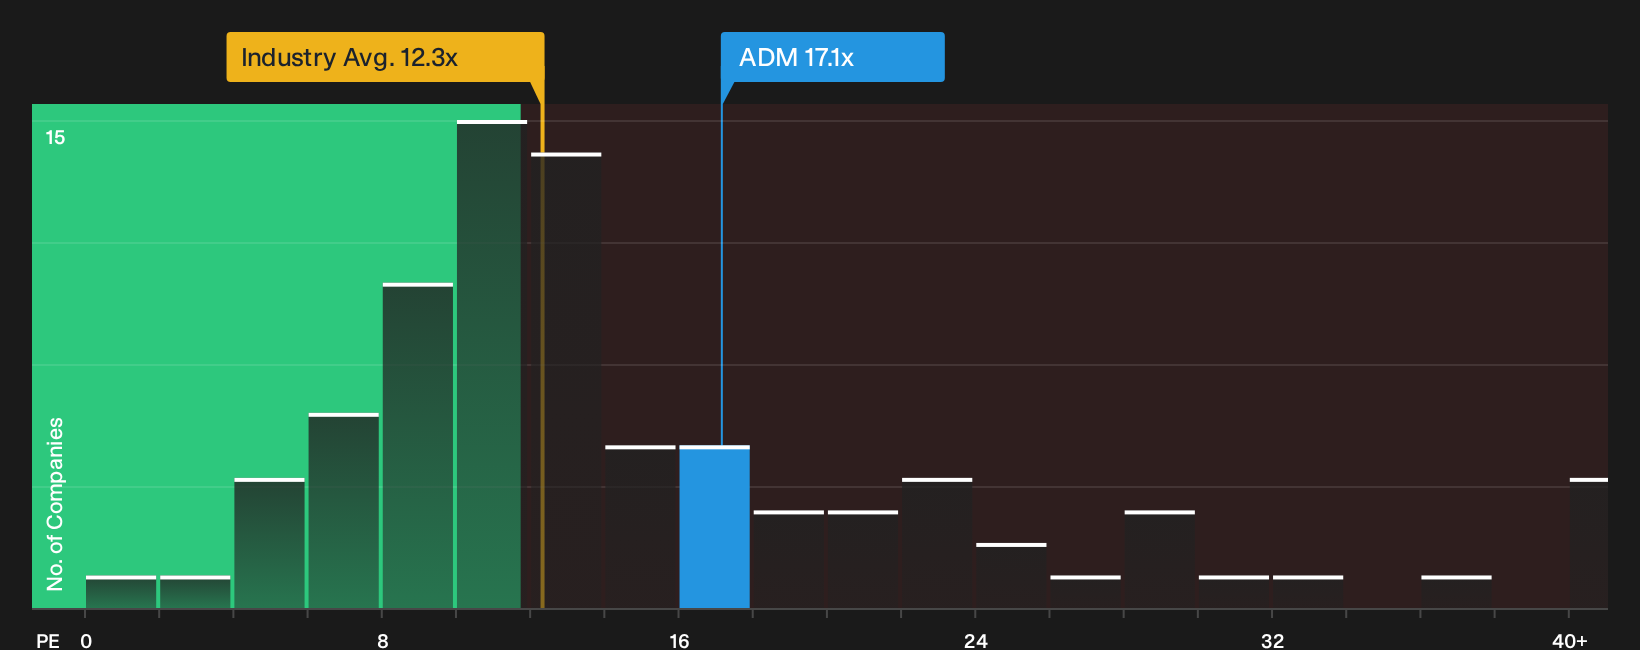
Analysts calling Admiral Group modestly undervalued encounter a different story when looking at what investors are already paying. The shares trade on a P/E of 17.1x, a touch above the peer average of 17x and well ahead of the wider European insurance sector at 12.3x.
The fair ratio for Admiral Group is 14.7x, which is below the current P/E. That gap points to some valuation risk if sentiment cools or sector multiples compress, even if the underlying business continues to execute. Do you see that premium as justified or as room for the market to re-rate lower?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Admiral Group story so far. If you want to move fast and rely on your own judgement, weigh up the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Admiral Group?
If Admiral Group has sharpened your focus on quality, do not stop here. Broader opportunity often appears where others have not looked yet.
- Target strong cash generators by reviewing the 8 high quality undervalued stocks that pair solid fundamentals with prices that still look reasonable.
- Prioritise resilience by scanning the 4 resilient stocks with low risk scores that aim to keep volatility and financial risk in check.
- Get ahead of the crowd by assessing the 5 high quality undiscovered gems that combine quality metrics with relatively low investor attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com