
Did Board Renewables Oversight Just Shift CLP Holdings' (SEHK:2) Investment Narrative?
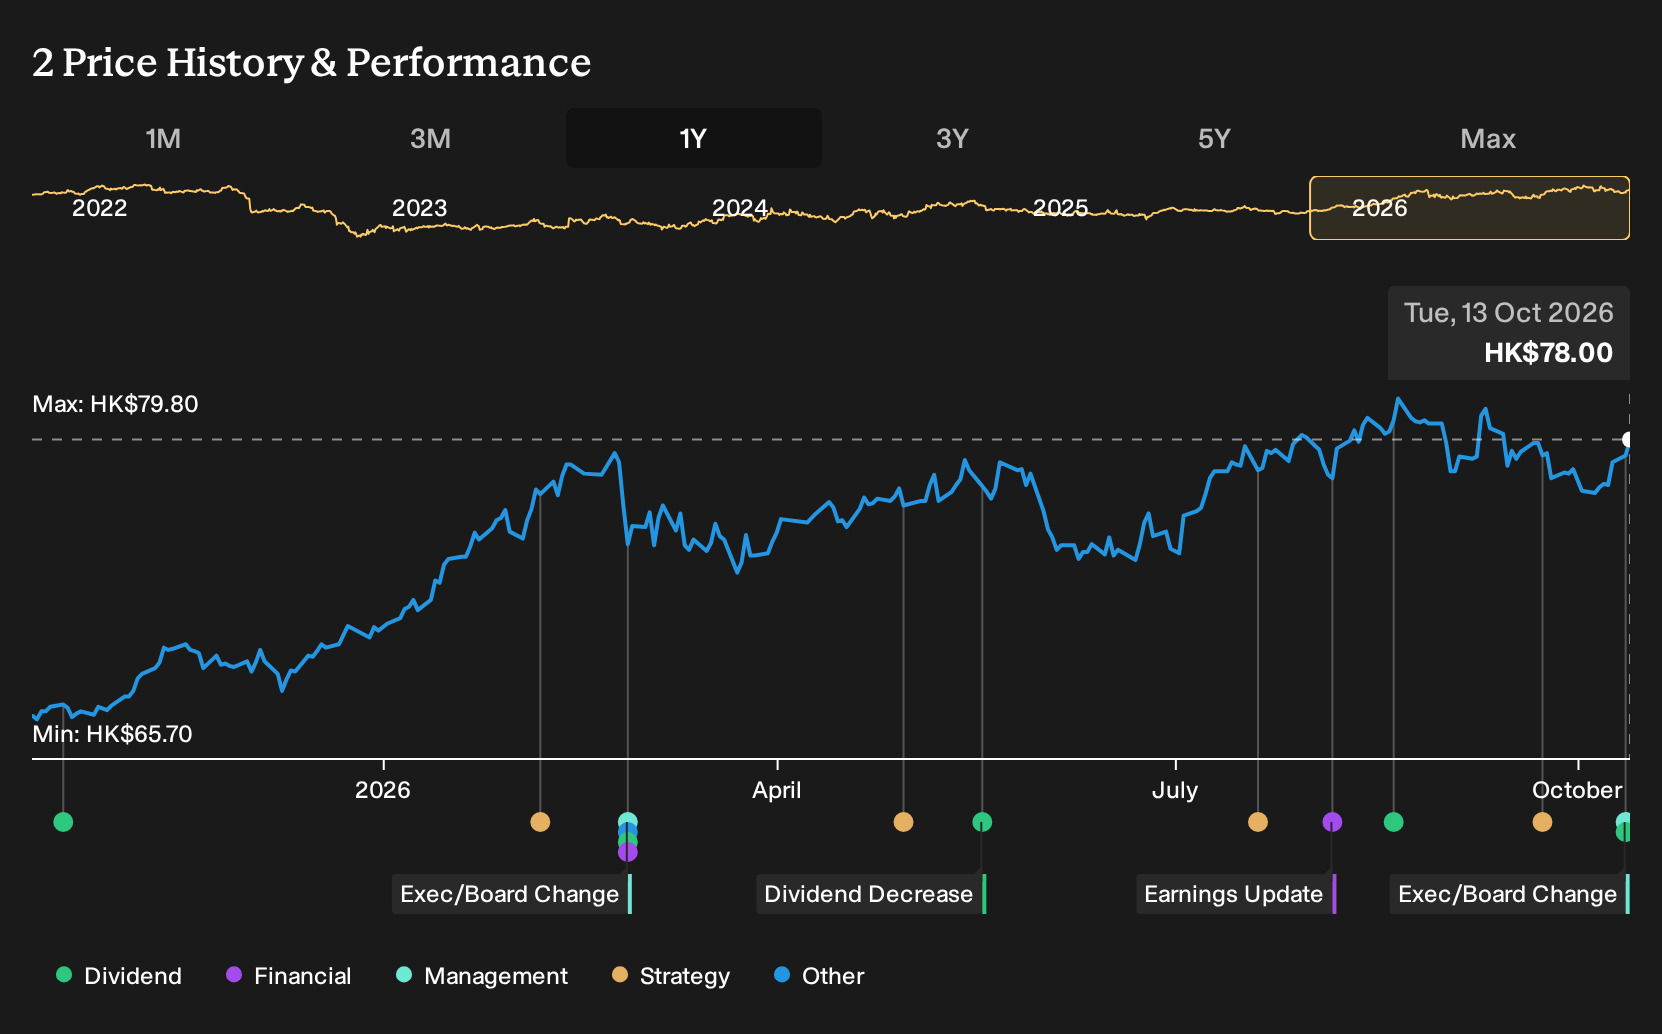
- CLP Holdings announced that effective 13 October 2026, Mr. Philip Lawrence Kadoorie has served as an additional Vice Chairman and has joined a newly created Renewables Business Committee overseeing China renewables (excluding nuclear) and Growth Markets operations.
- The dedicated Renewables Business Committee reflects more focused board attention on execution risk, capital allocation, and project discipline across CLP Holdings' non nuclear clean energy and overseas portfolios.
- We will now assess how CLP Holdings' new renewables focused board committee could reshape the investment narrative that investors have been using.
CLP Holdings Investment Narrative Recap
To own CLP Holdings, you need to be comfortable with a regulated Hong Kong grid backbone alongside more volatile overseas and renewables exposure. The key short term swing factor still sits in execution quality in Australia and growth markets, where tariffs, competition and project returns can quickly affect earnings stability.
The biggest risk remains pressure on margins and returns in Mainland China and international projects, especially as policy details and curtailment risk play through. The new renewables committee and extra vice chairman role may help oversight, but on their own do not materially change the near term risk reward balance.
The dividend decision on 12 October 2026 is the most directly relevant data point. A third interim payout of HK$0.63 per share, with an ex dividend date on 2 December 2026, indicates that CLP Holdings is still prioritising regular cash returns while it spends heavily on decarbonisation and grid assets.
For you as an investor, that distribution sits against earlier indications that free cash flow cover is tight and debt levels are high. The catalyst question is whether earnings from Hong Kong’s regulated grid and renewables projects can support this dividend profile over time without requiring significantly higher leverage or weaker returns on new investments.
CLP Holdings' analyst narrative points to revenues of HK$91.4b and earnings of HK$12.0b by 2029, based on revenue growth of 1.3% per year and an earnings increase of HK$1.5b from today’s HK$10.5b base.
Uncover why CLP Holdings' fair value indicates that CLP Holdings is in line with its current price.
Exploring Other Perspectives
Only two fair value estimates from the Simply Wall St Community cluster in a tight HK$73.63 to HK$79.49 band, yet you still see how sharply opinions on CLP Holdings can separate. Fresh board oversight of renewables, set against tariff pressure and heavy decarbonisation spend, gives plenty of room for very different conclusions. Explore them.
Explore another CLP Holdings fair value estimate, including one that suggests as much as 6% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your CLP Holdings research is our analysis highlighting 2 important warning signs that could impact your investment decision.
- See our latest analysis for CLP Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CLP Holdings' overall financial health at a glance.
Looking For More Ideas Beyond CLP Holdings?
Once you have a view on CLP Holdings, it can help to set that opinion against other opportunities on your radar. Use the Simply Wall St Screener to build a watchlist that matches the kind of risk, income, or quality profile you actually want.
- If your priority is resilient balance sheets and fundamentals, start with a curated list of solid balance sheet and fundamentals (204 results) that can help you focus on financially robust businesses.
- For investors hunting for mispriced opportunities, widen your search with a 185 high quality undervalued stocks that could broaden the pool of ideas beyond CLP Holdings.
- If income is front and centre for your portfolio, zero in on a 223 dividend fortresses that screens for higher yield potential with an emphasis on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com