
CFO Change Could Be A Big Moment For Dauch (DCH)
- Dauch Corporation reported a planned finance leadership transition, with Nathan Iles joining as Senior Vice President of Finance on November 2, 2026, and succeeding Christopher May as Chief Financial Officer on December 1, 2026, while May moves into an Executive Vice President and Chief Administrative Officer role overseeing IT and HR.
- The reshuffle concentrates financial oversight with a new CFO who has deep auto supplier experience and reallocates Christopher May toward IT and people infrastructure that are central to Dauch's cost synergy and productivity ambitions.
- The focus now shifts to how Dauch's investment narrative might change as Nathan Iles steps in to lead the finance organization.
Scan how Dauch's leadership reshuffle compares with peers by reviewing list of solid balance sheet and fundamentals (25 results) that may be positioned for their own finance-led inflection points.
Dauch Investment Narrative Recap
To own Dauch, you need to believe it can turn a larger driveline and metal forming platform into steadier cash generation while managing a still meaningful exposure to General Motors truck and SUV programs. The near term story is still about integrating Dowlais, extracting the planned US$300m cost savings, and supporting an unprofitable base business that is working through a loss of US$163.5m on US$8.2b of revenue.
This CFO transition looks more like an execution risk than a new catalyst. The key swing factor remains delivery on the multi year cost and productivity program while keeping quoting momentum in internal combustion and hybrid drivetrains. Customer concentration, high leverage around US$4.1b of net debt, and rising labor and logistics costs continue to frame the main operational risk.
The most relevant development is Nathan Iles stepping in as CFO after a period running finance at Standard Motor Products and UCI International. Dauch is in the middle of a complex integration with Dowlais, an active US$2b quoting pipeline, and a cost synergy target of US$300m, so the finance function sits close to the main levers that influence margins and cash flow.
Investors will likely watch how quickly Iles embeds into capital allocation, debt management, and cost tracking, given Dauch is still loss making and relies on higher risk funding sources. The handoff also frees Christopher May to focus on IT and HR, areas tied to productivity and restructuring execution, which are central to whether the cost program, SDS joint venture earnings contribution, and North American reshoring opportunities feed through cleanly into reported results.
Dauch's current analyst storyline points to US$12.3b revenue and US$180.9m earnings by 2029. This implies 14.4% yearly revenue growth and an earnings swing of about US$344m from a loss of US$163.5m today to the forecast consensus level in that year.
Uncover why Dauch's fair value indicates a 69% potential upside to its current price that could close sooner than many investors expect.
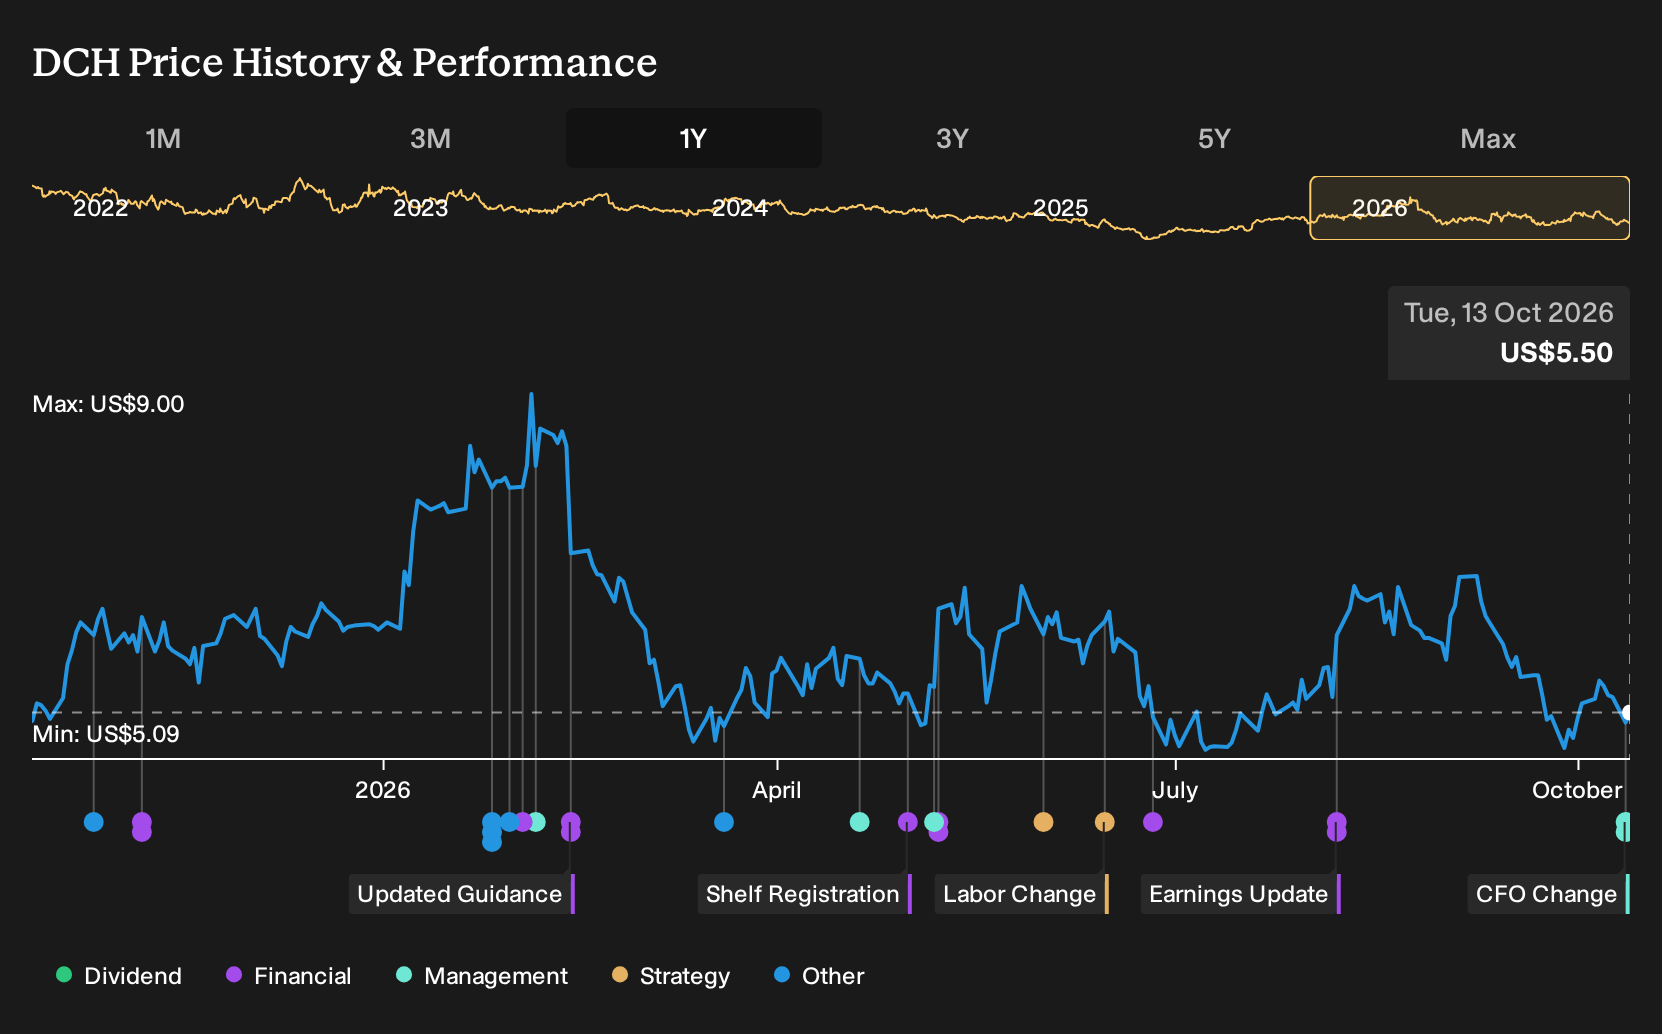
Exploring Other Perspectives
For Dauch, bullish analysts focus on the potential catalyst of lower net leverage over time. Before this CFO news, the most optimistic forecasts already pointed to US$12.3b revenue and about US$289.2m earnings by 2029, while the most cautious views sat near a loss of roughly US$250m. That spread shows how far opinions can diverge. This leadership change could push those narratives in new directions, so treat it as a prompt to compare several viewpoints rather than rely on a single forecast path.
Explore another Dauch fair value estimate, including one that suggests up to 165% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Dauch research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Dauch. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dauch's overall financial health at a glance.
Looking For More Investment Ideas Beyond Dauch?
If Dauch has sharpened your thinking about balance sheets, cash flow, and risk, it can be useful to set it alongside a wider watchlist built from companies with different financial profiles. The Simply Wall St Screener can help you quickly surface other stocks that fit clear, rules based criteria so you are not relying on a single story.
- If capital preservation is a priority, start with companies that pair resilient earnings with modest risk metrics by reviewing 32 resilient stocks with low risk scores that meet those filters.
- Income focused investors can hunt for payout strength and balance sheet support by scanning 8 dividend fortresses that combine higher yields with supporting fundamentals.
- For those looking for mispriced quality, widen the lens beyond Dauch by assessing 32 high quality undervalued stocks that match your preferred mix of financial strength and valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com