
Jabil (JBL) After The Adani AI Deal Is The Stock Still Undervalued
Jabil (JBL) is back in focus after signing a non binding 50:50 joint venture MoU with Adani Enterprises to manufacture AI and data center hardware in India, alongside fresh earnings and guidance.
The fresh MoU news comes after a strong run, with Jabil’s share price up 32.23% year to date and a 1-day share price return of 1.87% around the announcement. The 1-year total shareholder return of 58.65% indicates that momentum has been building rather than fading.
Scan beyond Jabil and see which other AI infrastructure players are already moving fast with the 92 AI infrastructure stocks.
So is this sharp move in Jabil simply investors chasing an AI story, or does the new joint venture and recent results line up with what you are actually paying for today?
Most Popular Narrative: 25% Undervalued
Jabil last closed at $317.86, while the most followed narrative anchors fair value at $425, which implies a material valuation gap if that view proves accurate. The same storyline leans heavily on AI infrastructure, regulated industries and cash returns as the pillars that need to keep working together.
The main thing that has to go right is that Jabil converts the guided ramp in AI infrastructure, regulated industries programs and automation into sustained margins while managing supply constraints and working capital.
The numbers on AI-related revenue growth, segment guidance, free cash flow generation and large ongoing buybacks together imply that the current share price treats Jabil as undervalued and does not fully reflect this bullish setup.
See why 36 investors see Jabil as 25% undervalued.
Result: Fair Value of $425 (UNDERVALUED)
Still, the story can break if AI hardware orders hit component bottlenecks or if elevated inventory days drag on Jabil’s free cash flow and buyback capacity.
Find out about the key risks to this Jabil narrative.
Another View: What Jabil’s P/E Says
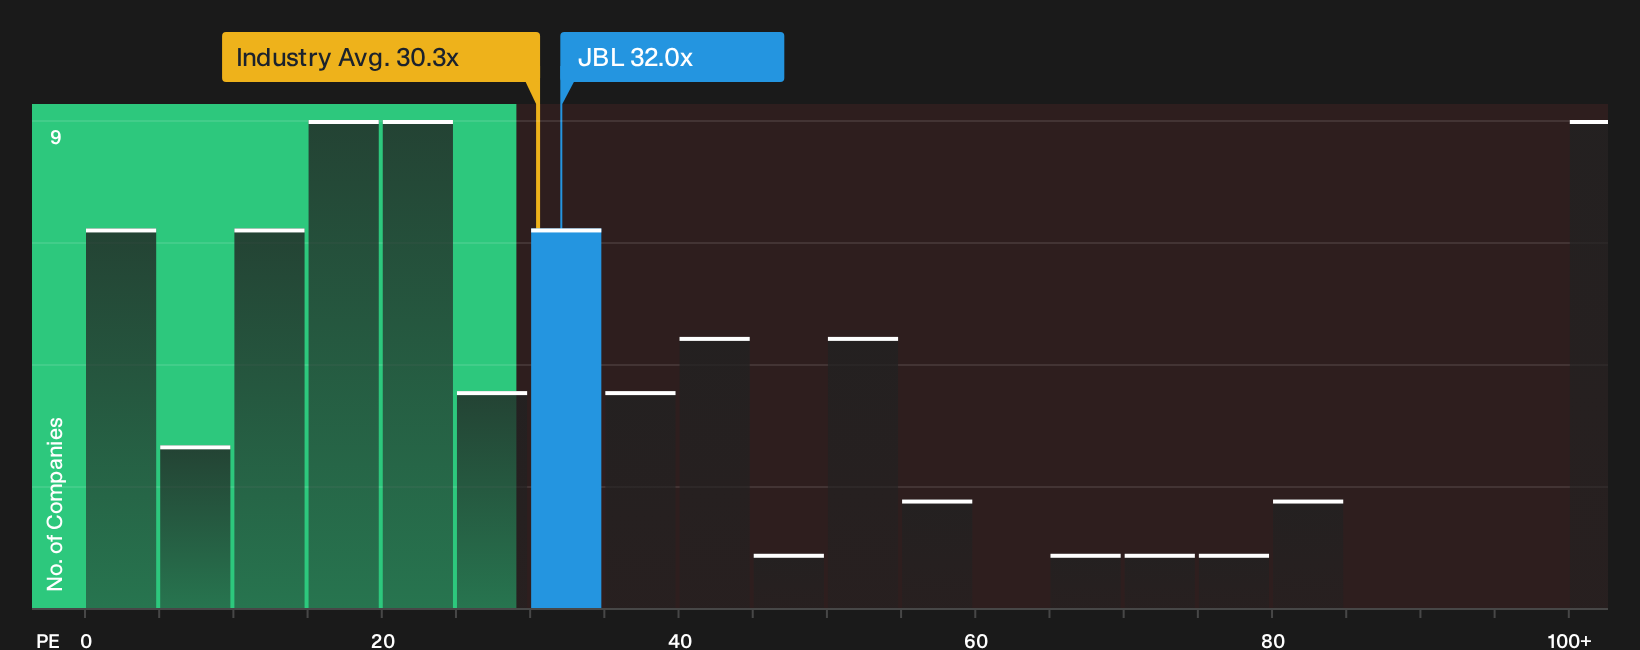
The story looks different when you shift from fair value estimates to the plain P/E that Jabil trades on today. The stock changes hands at about 32x earnings, above the US Electronic industry on 30.3x and below the peer average on 36.7x, while the fair ratio sits even higher at 37.5x.
That mix suggests the market already prices in a premium to the wider sector but still leaves a gap to both peers and the fair ratio. The share price could move toward those levels over time. The question is how much valuation risk you are comfortable carrying if expectations around AI or cash returns start to wobble.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Jabil in this piece cuts both ways, and the clock is always ticking when momentum and risk sit this close together. Pressure test the data yourself and see how you feel about the balance of 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Jabil?
Do not stop your research with Jabil. Broaden your watchlist with fresh ideas surfaced by Simply Wall Street screeners that target quality, value and resilience.
- Target potential value opportunities by scanning companies that combine strong fundamentals with appealing pricing using the 32 high quality undervalued stocks.
- Strengthen your income stream by focusing on businesses with substantial yields and robust profiles through the 8 dividend fortresses.
- Dial down portfolio risk by concentrating on financially resilient businesses with the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com