
YIT Oyj (HLSE:YIT) Is In Focus Again, But What Is The Market Weighing?
YIT Oyj (HLSE:YIT) has drawn fresh attention after agreeing to a €70 million life cycle contract with the municipality of Tuusula to design, build, and service a large Lahela education hub.
YIT Oyj’s latest life cycle deal lands as the share price trades at €4.13, with a 30-day share price return of 10.28% and a strong 90-day gain of 65.53%. The 1-year total shareholder return of 47.61% and 3-year total shareholder return of 123.00% indicate that momentum has been building over time rather than fading.
Scan beyond YIT Oyj and this Tuusula contract by comparing it with a curated list of solid balance sheet and fundamentals (204 results) that have also caught investor attention through resilient fundamentals and project pipelines.
After a 65% jump in three months and fresh contract headlines, the obvious wins on YIT Oyj might feel already captured. The real issue now is whether the current price still lags the underlying value.
Most Popular Narrative: 8% Overvalued
The most followed narrative puts YIT Oyj’s fair value at €3.84, slightly below the recent €4.13 close, so the market is already paying a premium to those assumptions.
Favorable demographic and urban growth trends in CEE markets, where YIT is strategically expanding with a pipeline of nearly €400 million in projects and a plot portfolio supporting 13,000+ new homes, position the company to benefit from higher demand and above-industry-average revenue growth. Strategic investments in operational efficiency, such as improved supply chain and customer insight tools, together with a growing focus on green, energy-efficient construction, provide a competitive advantage that should support higher net margins and earnings resilience amidst sector digitalization and sustainability trends.
See why 5 investors see YIT Oyj as 8% overvalued.
Result: Fair Value of €3.84 (OVERVALUED)
Still, pressure on YIT Oyj from a weak Finnish residential backdrop and high gearing above 80% could easily upset the current fair value narrative.
Find out about the key risks to this YIT Oyj narrative.
Another View: What YIT Oyj’s Sales Multiple Signals
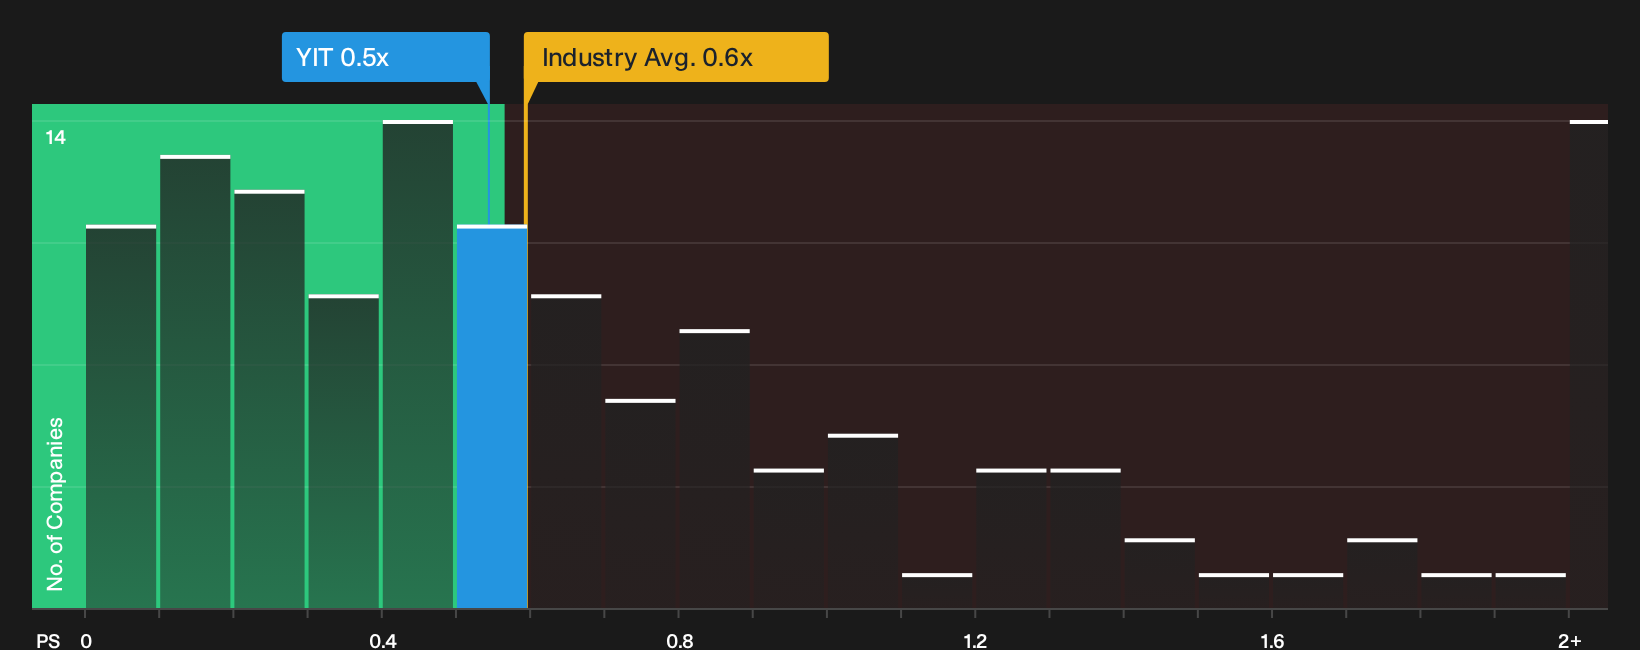
There is a twist once you move away from the analyst fair value of €3.84 and look at what the market is paying for YIT Oyj’s revenue. The shares trade on a P/S of 0.5x compared with a peer average of 1.8x, an industry average of 0.6x, and a fair ratio of 3x that the market could move towards.
That gap suggests investors are paying a far lower price for each euro of YIT Oyj’s sales than both peers and the fair ratio imply, even though the stock is trading above the SWS DCF estimate of €2.75. The question for investors is which signal to prioritise when the picture is this mixed.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings about YIT Oyj after all this. If that rings true, move fast, explore both sides of the story in depth, and carefully weigh the 2 key rewards and 2 important warning signs.
Looking for more ideas beyond YIT Oyj?
You do not need to stop with YIT Oyj. Use the screener to uncover fresh opportunities, compare quality, and pressure test your next moves before capital goes to work.
- Target potential bargains by focusing on strong businesses trading below estimated worth through the 185 high quality undervalued stocks.
- Prioritise resilience by filtering for companies with sturdier finances using the 225 resilient stocks with low risk scores.
- Spot future contenders early by scanning a 620 high quality undiscovered gems before the wider market pays attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com