
Westinghouse Air Brake Technologies (WAB) On Analyst Upgrades And The Case For More Value
Analyst upgrades have pushed Westinghouse Air Brake Technologies (WAB) into focus after Louis Navellier raised its rating and Zacks moved the shares to Rank #2, citing stronger institutional interest and a revised earnings outlook.
At a share price of US$286.51, Westinghouse Air Brake Technologies has logged a 32.47% year to date share price return and a 46.86% total shareholder return over the past year. The 175.40% three year total shareholder return points to momentum that recent upgrades and rising earnings estimates are now catching up to.
Scan for other potential beneficiaries of this upgrade-driven momentum by comparing Westinghouse Air Brake Technologies with our curated list of 20 high quality undiscovered gems.
Westinghouse Air Brake Technologies has already rewarded holders in a big way, yet the stock still trades below the current analyst price target. Is most of the upside already behind it, or does valuation still leave room?
Most Popular Narrative: 13% Undervalued
Westinghouse Air Brake Technologies closed at $286.51, while the most followed narrative pegs fair value closer to $329.58. This frames today’s strength as still short of what long term earnings power could support.
Sustained global investment in rail infrastructure and modernization across freight and transit, including large international awards in regions such as Australia and Latin America, is feeding into Westinghouse Air Brake Technologies’ multiyear backlog above US$30b and could support more stable revenue and earnings over several years.
See why 22 investors see Westinghouse Air Brake Technologies as 13% undervalued.
Result: Fair Value of $329.58 (UNDERVALUED)
Still, the bull story around Westinghouse Air Brake Technologies can be knocked off course if tariffs continue to pressure margins or if insider selling signals valuation fatigue.
Find out about the key risks to this Westinghouse Air Brake Technologies narrative.
Another View: What Westinghouse Air Brake Technologies’ P/E Is Telling You
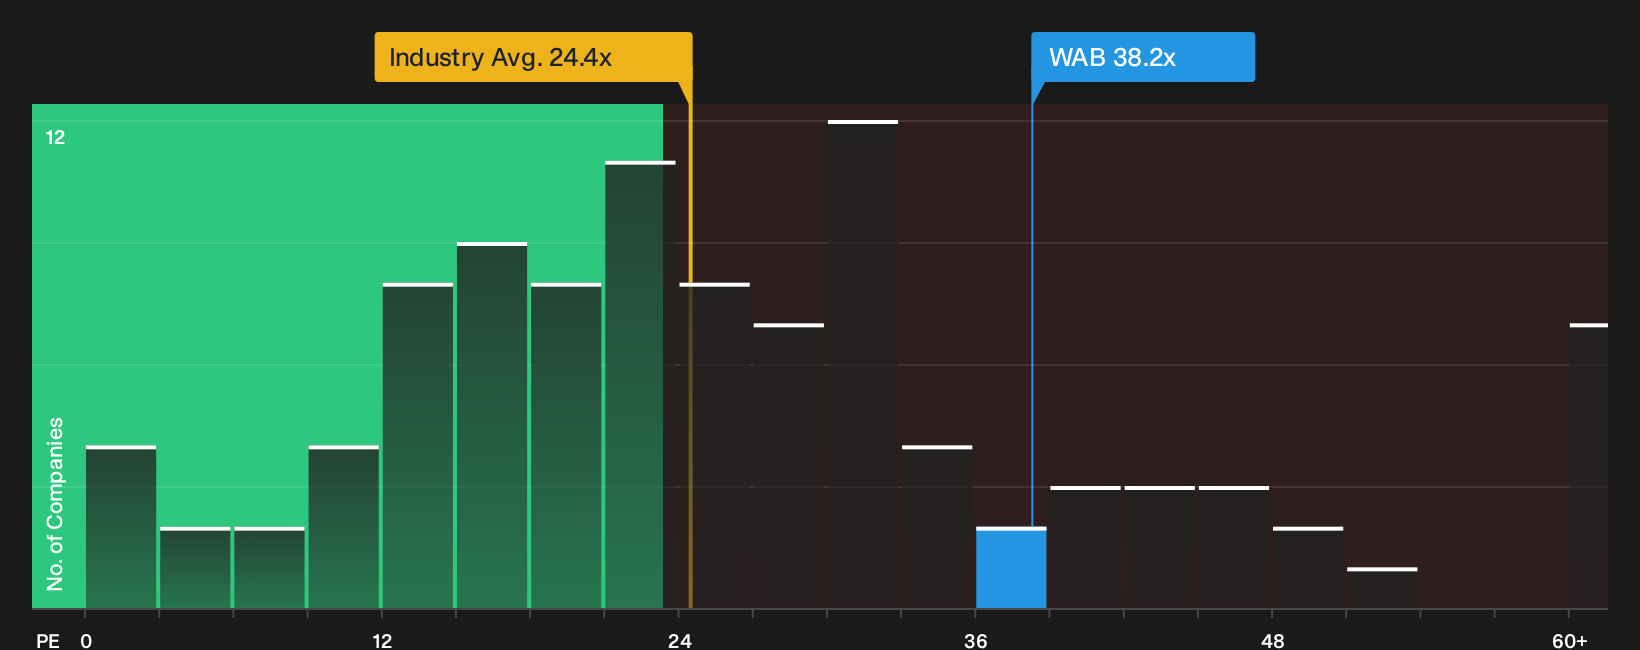
The DCF-driven fair value of $329.58 paints Westinghouse Air Brake Technologies as undervalued. The P/E ratio tells a tougher story. At 38.2x earnings, WAB trades well above the US Machinery group on 24.4x and above its own fair ratio of 31.9x. This implies investors are paying a premium that could magnify any disappointment. Which yardstick do you trust more when expectations are this full?
See what the numbers say about this price and how they stack up in context in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Westinghouse Air Brake Technologies so far, or a clear message in disguise? Put the data to work for you and weigh both sides through 2 key rewards and 2 important warning signs.
Looking for more Westinghouse Air Brake Technologies investment ideas?
If Westinghouse Air Brake Technologies has you thinking harder about pricing power and risk, then widening your net with focused screeners can help refine your next move.
- Target potential future mispricings by scanning a curated set of 32 high quality undervalued stocks that pair stronger balance sheets with cash flows the market may not be fully pricing.
- Prioritise resilience and sleep-better-at-night holdings by reviewing 32 resilient stocks with low risk scores that score well on financial strength and earnings stability.
- Hunt beyond the usual tickers by tracking 11 elite penny stocks with strong financials that already show solid fundamentals instead of relying purely on story or hype.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com